

Key Takeaways
- Bernstein has kept its Outperform rating and $650 price target on Dell Technologies. That’s 103% above the Nov. 16 close, with the stock 46% below its September high.
- A Barclays downgrade, Texas’s turn against new data centers and the resignation of NVIDIA’s CEO all hit the stock, while analysts kept raising Dell’s earnings estimates.
- Dell trades at about 11x forward earnings, near its 5-year average. $650 works out to 18x what analysts expect it to earn in the year ending January 2029.
- Bernstein sees the selloff as overdone. But Dell is lending more and more money to its own customers, and that makes 18x a hard sell until cash flow catches up. The Nov. 24 report is the first test.
Dell Technologies (DELL) closed at $320.55 on Nov. 16, 46% below its Sept. 17 closing high, and Bernstein still thinks it can double from here. In a note based on the Nov. 12 close, analyst Mark Newman kept his Outperform rating and his $650 price target, 103% above that latest close.
Three hits in five weeks
None of the damage came from Dell’s own numbers. On Oct. 14, Barclays downgraded Dell to Equal Weight and cut its target to $574 from $603.
Then came Texas. Gov. Greg Abbott paused grid approvals for new data centers in August and extended the pause to all state permits on Sept. 21, and Gina Hinojosa, who won the Nov. 3 governor’s race, has promised a moratorium on all data center approvals until the Legislature passes new protections. She takes office in January.
And on Nov. 12, NVIDIA (NVDA) announced Jensen Huang’s resignation as CEO, effective immediately. Dell’s AI servers are built on NVIDIA’s chips, and Dell fell 7.2% on Nov. 13 and another 7.0% on Nov. 16 as the AI trade sold off.
TIKR tracks 29 analysts on Dell Technologies. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Dell Technologies, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Dell Technologies’ Analyst Ratings
Bernstein hasn’t blinked
Other firms cut on Nov. 16: Citi lowered its target to $550 from $600 and kept its Buy rating, and Morgan Stanley cut its target to $403 from $511 and kept its Equal Weight rating.
Newman’s argument is that the market is pricing the wrong risk. Bernstein estimates that emerging AI cloud providers make up roughly 27% of Dell’s fiscal 2027 revenue but only about 12% of its operating profit, since most of the profit still comes from traditional servers, storage and enterprise customers. Demand backs that up: Dell booked a record $60.9 billion of AI server orders in its July quarter and ended it with a $95 billion AI backlog.
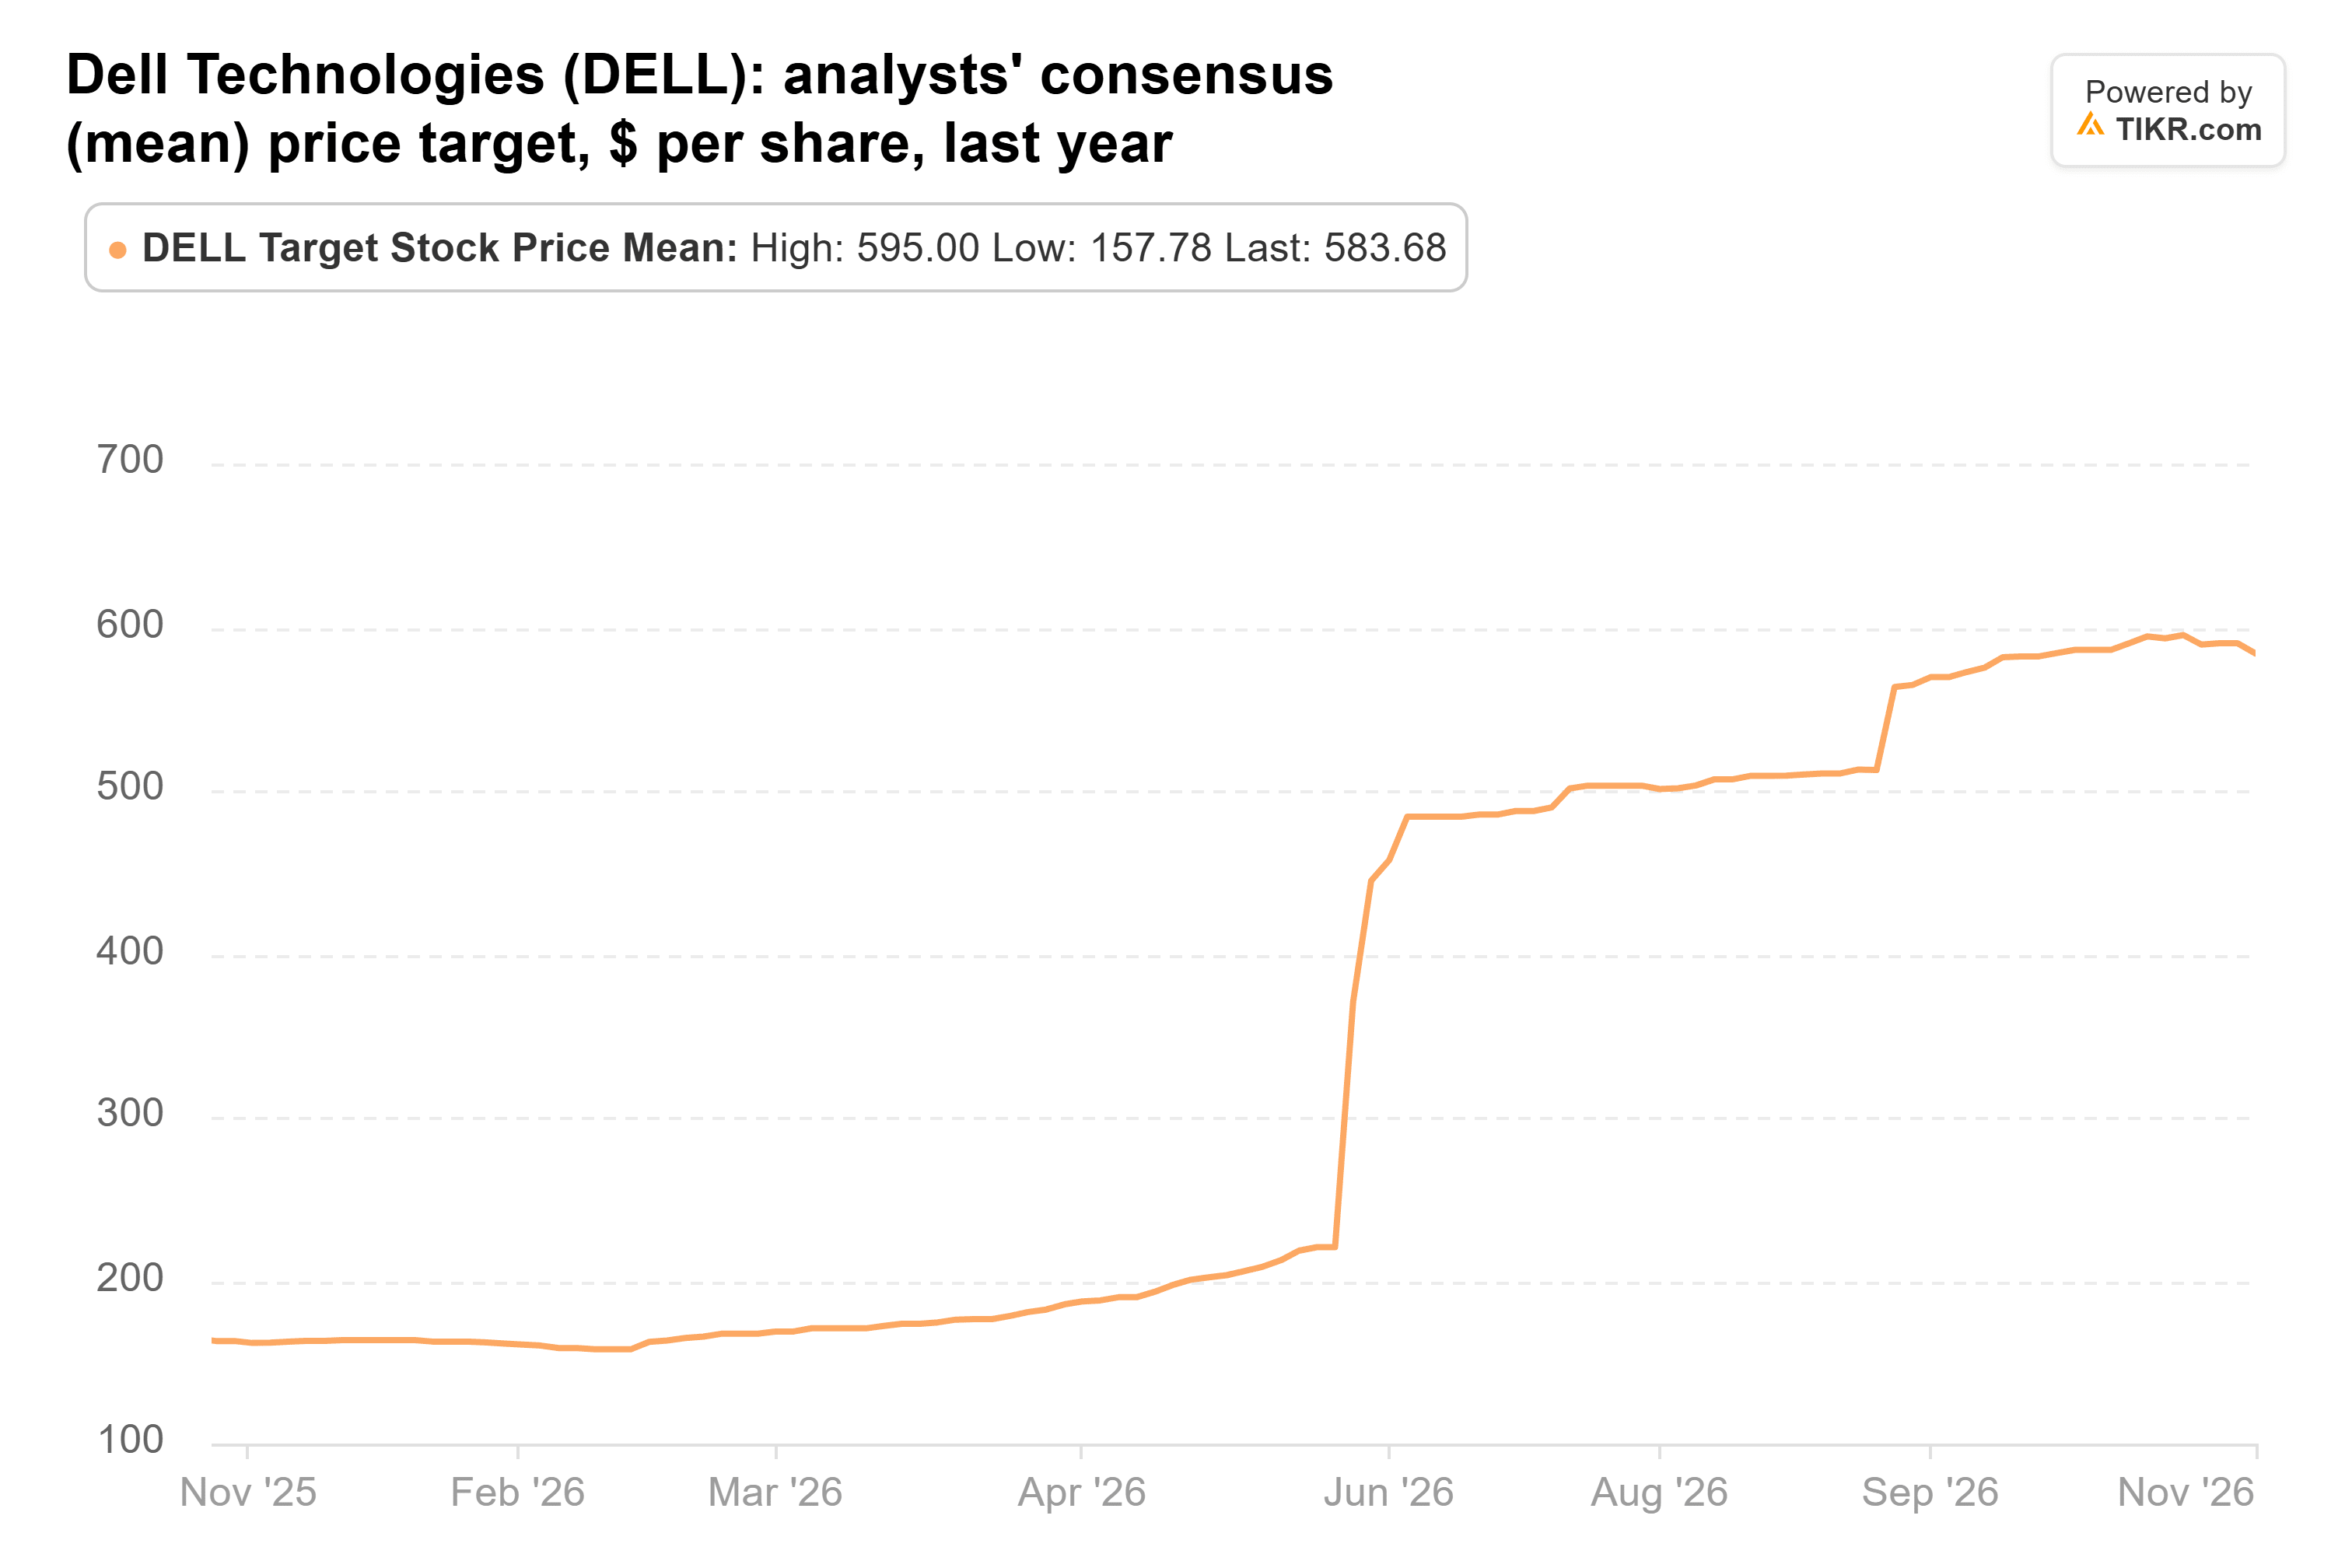
Even with those cuts, the consensus target is $584, just below its $595 peak on Oct. 27:
Does $650 add up?
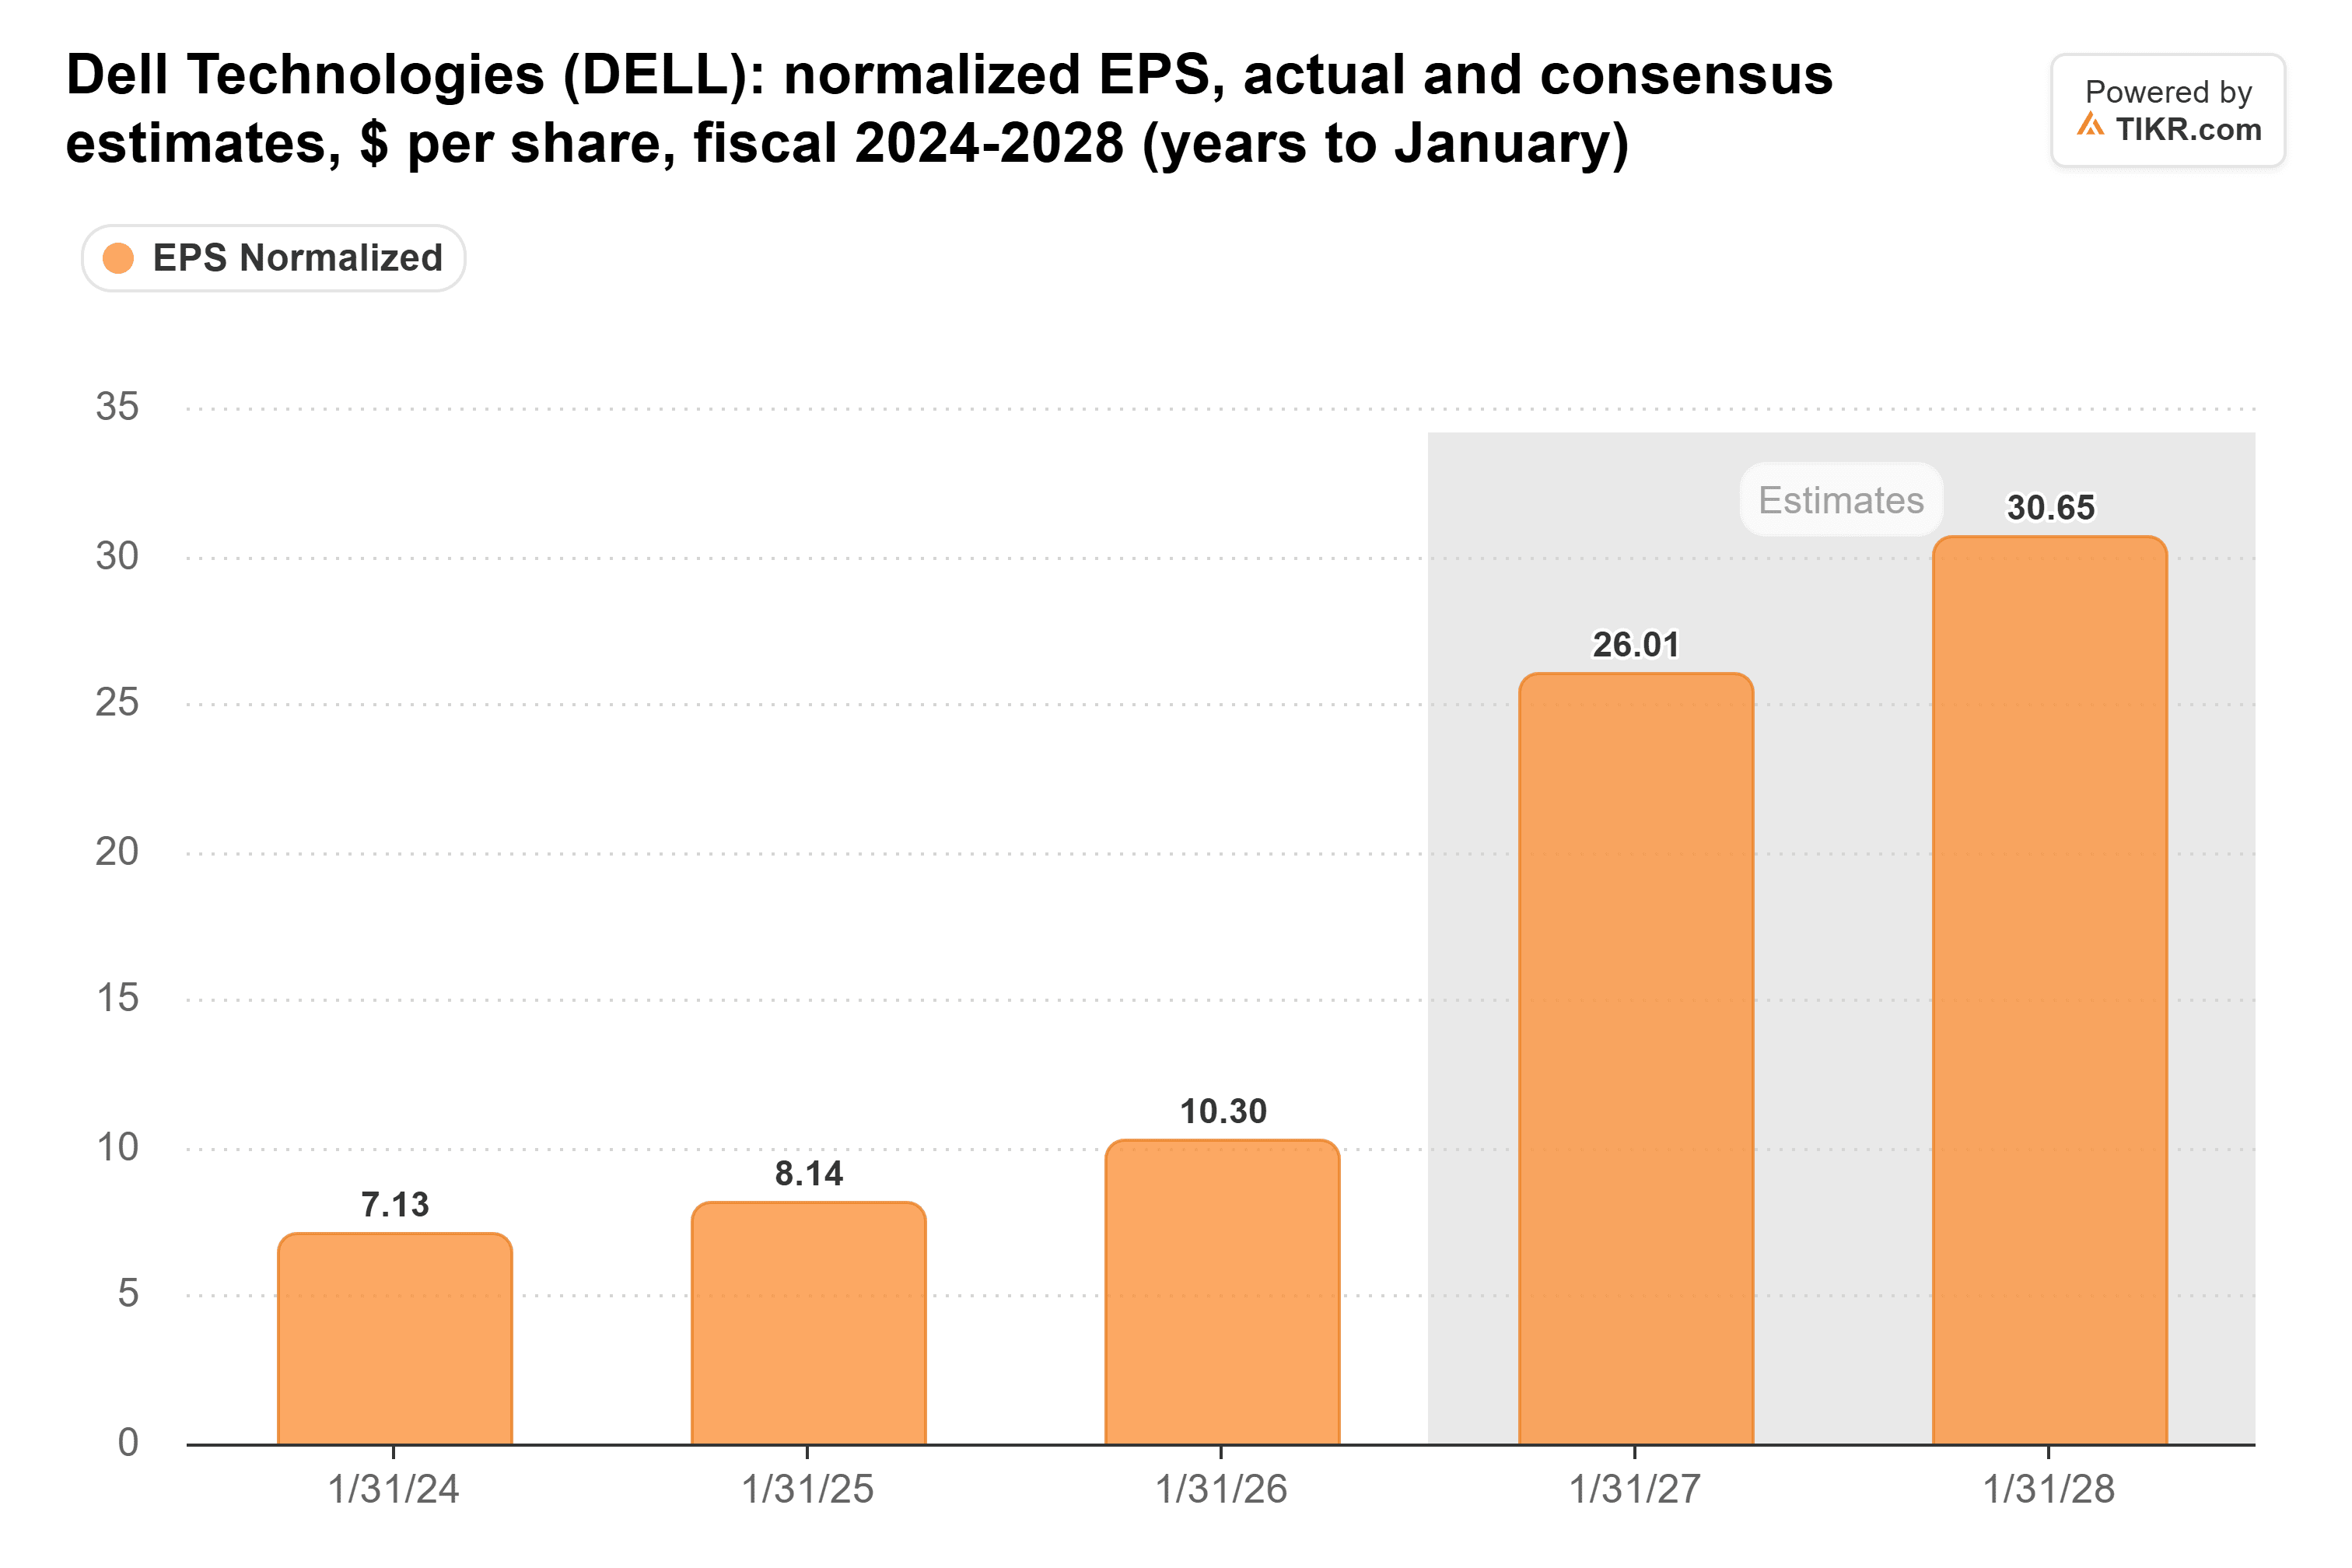
Analysts kept raising their estimates while the stock slid. TIKR’s consensus for normalized EPS in the year ending January 2028 is $30.65, up from $21.40 at the end of June. This year’s $26.01 is a touch above Dell’s own non-GAAP guidance of $25.50:
That has pushed Dell’s forward P/E down to about 11x. That’s a bit under its 5-year average of 12x and far below the 26x it hit in August:

The public summary of Bernstein’s note doesn’t show the multiple behind $650, so here is the math on consensus. Analysts expect $36.03 in the year ending January 2029, and $650 is 18x that. If the multiple stays where it is, earnings growth alone gets the stock about 27% higher. On top of that, the multiple has to rise about 60%.
The catch is Dell’s lending
Dell is financing more of what it sells. Its financing receivables rose to $20.4 billion at July 31 from $14.3 billion six months earlier, and it wrote $10.3 billion of new financing in the first half, up from $4.0 billion a year earlier. Cash from operations rose 18% to $6.3 billion over those six months, while GAAP net income more than tripled to $7.6 billion from $2.1 billion.
Bernstein is right that the selloff went further than the business news justified. But 18x is a price for earnings the market trusts, and that multiple is hard to earn while Dell lends customers the money to buy its racks.
On Nov. 24, Dell has to show three things: AI server revenue at or above its $19 billion guidance, an AI backlog near $95 billion, and free cash flow well above the second quarter’s $986 million.
So what is Dell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Dell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



