Key Takeaways
- Credo Technology (CRDO) stock fell 8% in the past week as turmoil at Nvidia (NVDA) hit AI chip stocks, Marvell included.
- Credo’s patent settlement with Marvell Technology (MRVL) protects the cables behind most of its growth.
- At 17x forward earnings against a three-year average of 61x, Credo looks like a buy ahead of its Dec. 1 report.
Credo Technology stock is down 7% in the past week, and very little of that came from Credo.
The selling started at Nvidia. Jensen Huang’s resignation and Treasury Secretary Scott Bessent’s weekend call for a “dramatic shakeup” at the company hit AI chip stocks ahead of Nvidia’s earnings.
Nvidia is flat in the past week, while Marvell Technology is down 8%. Credo’s cables go into the same AI buildout that Nvidia’s chips anchor, so it got swept up too.
Credo’s own news: a lower target and a settlement
TD Cowen cut its Credo target to $175 from $300 on Monday and kept its Buy rating.
After Tuesday’s close, Credo settled its patent dispute with Marvell over active electrical cables (AECs), which also ends Marvell’s challenges to Credo’s patents at the patent office. The terms weren’t disclosed.
That matters, since AECs drove more than 90% of Credo’s Q1 revenue growth, and MaxLinear wants 20% to 30% of the next generation, 1.6T.
My read: Marvell would rather compete in optics, the target of its $115 billion all-stock deal for Lumentum.
That deal isn’t expected to close until the first half of 2028. Marvell reports on Dec. 1 too, and what it says about copper against optics will show how much fight it has left for Credo’s core business.
TIKR tracks 20 analysts on Credo Technology. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Credo Technology, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Credo Technology’s Analyst Ratings
17x is cheap if Dec. 1 delivers
Analysts expect Credo’s normalized EPS to nearly triple, from $3.46 in fiscal 2026 to $9.71 in fiscal 2028:
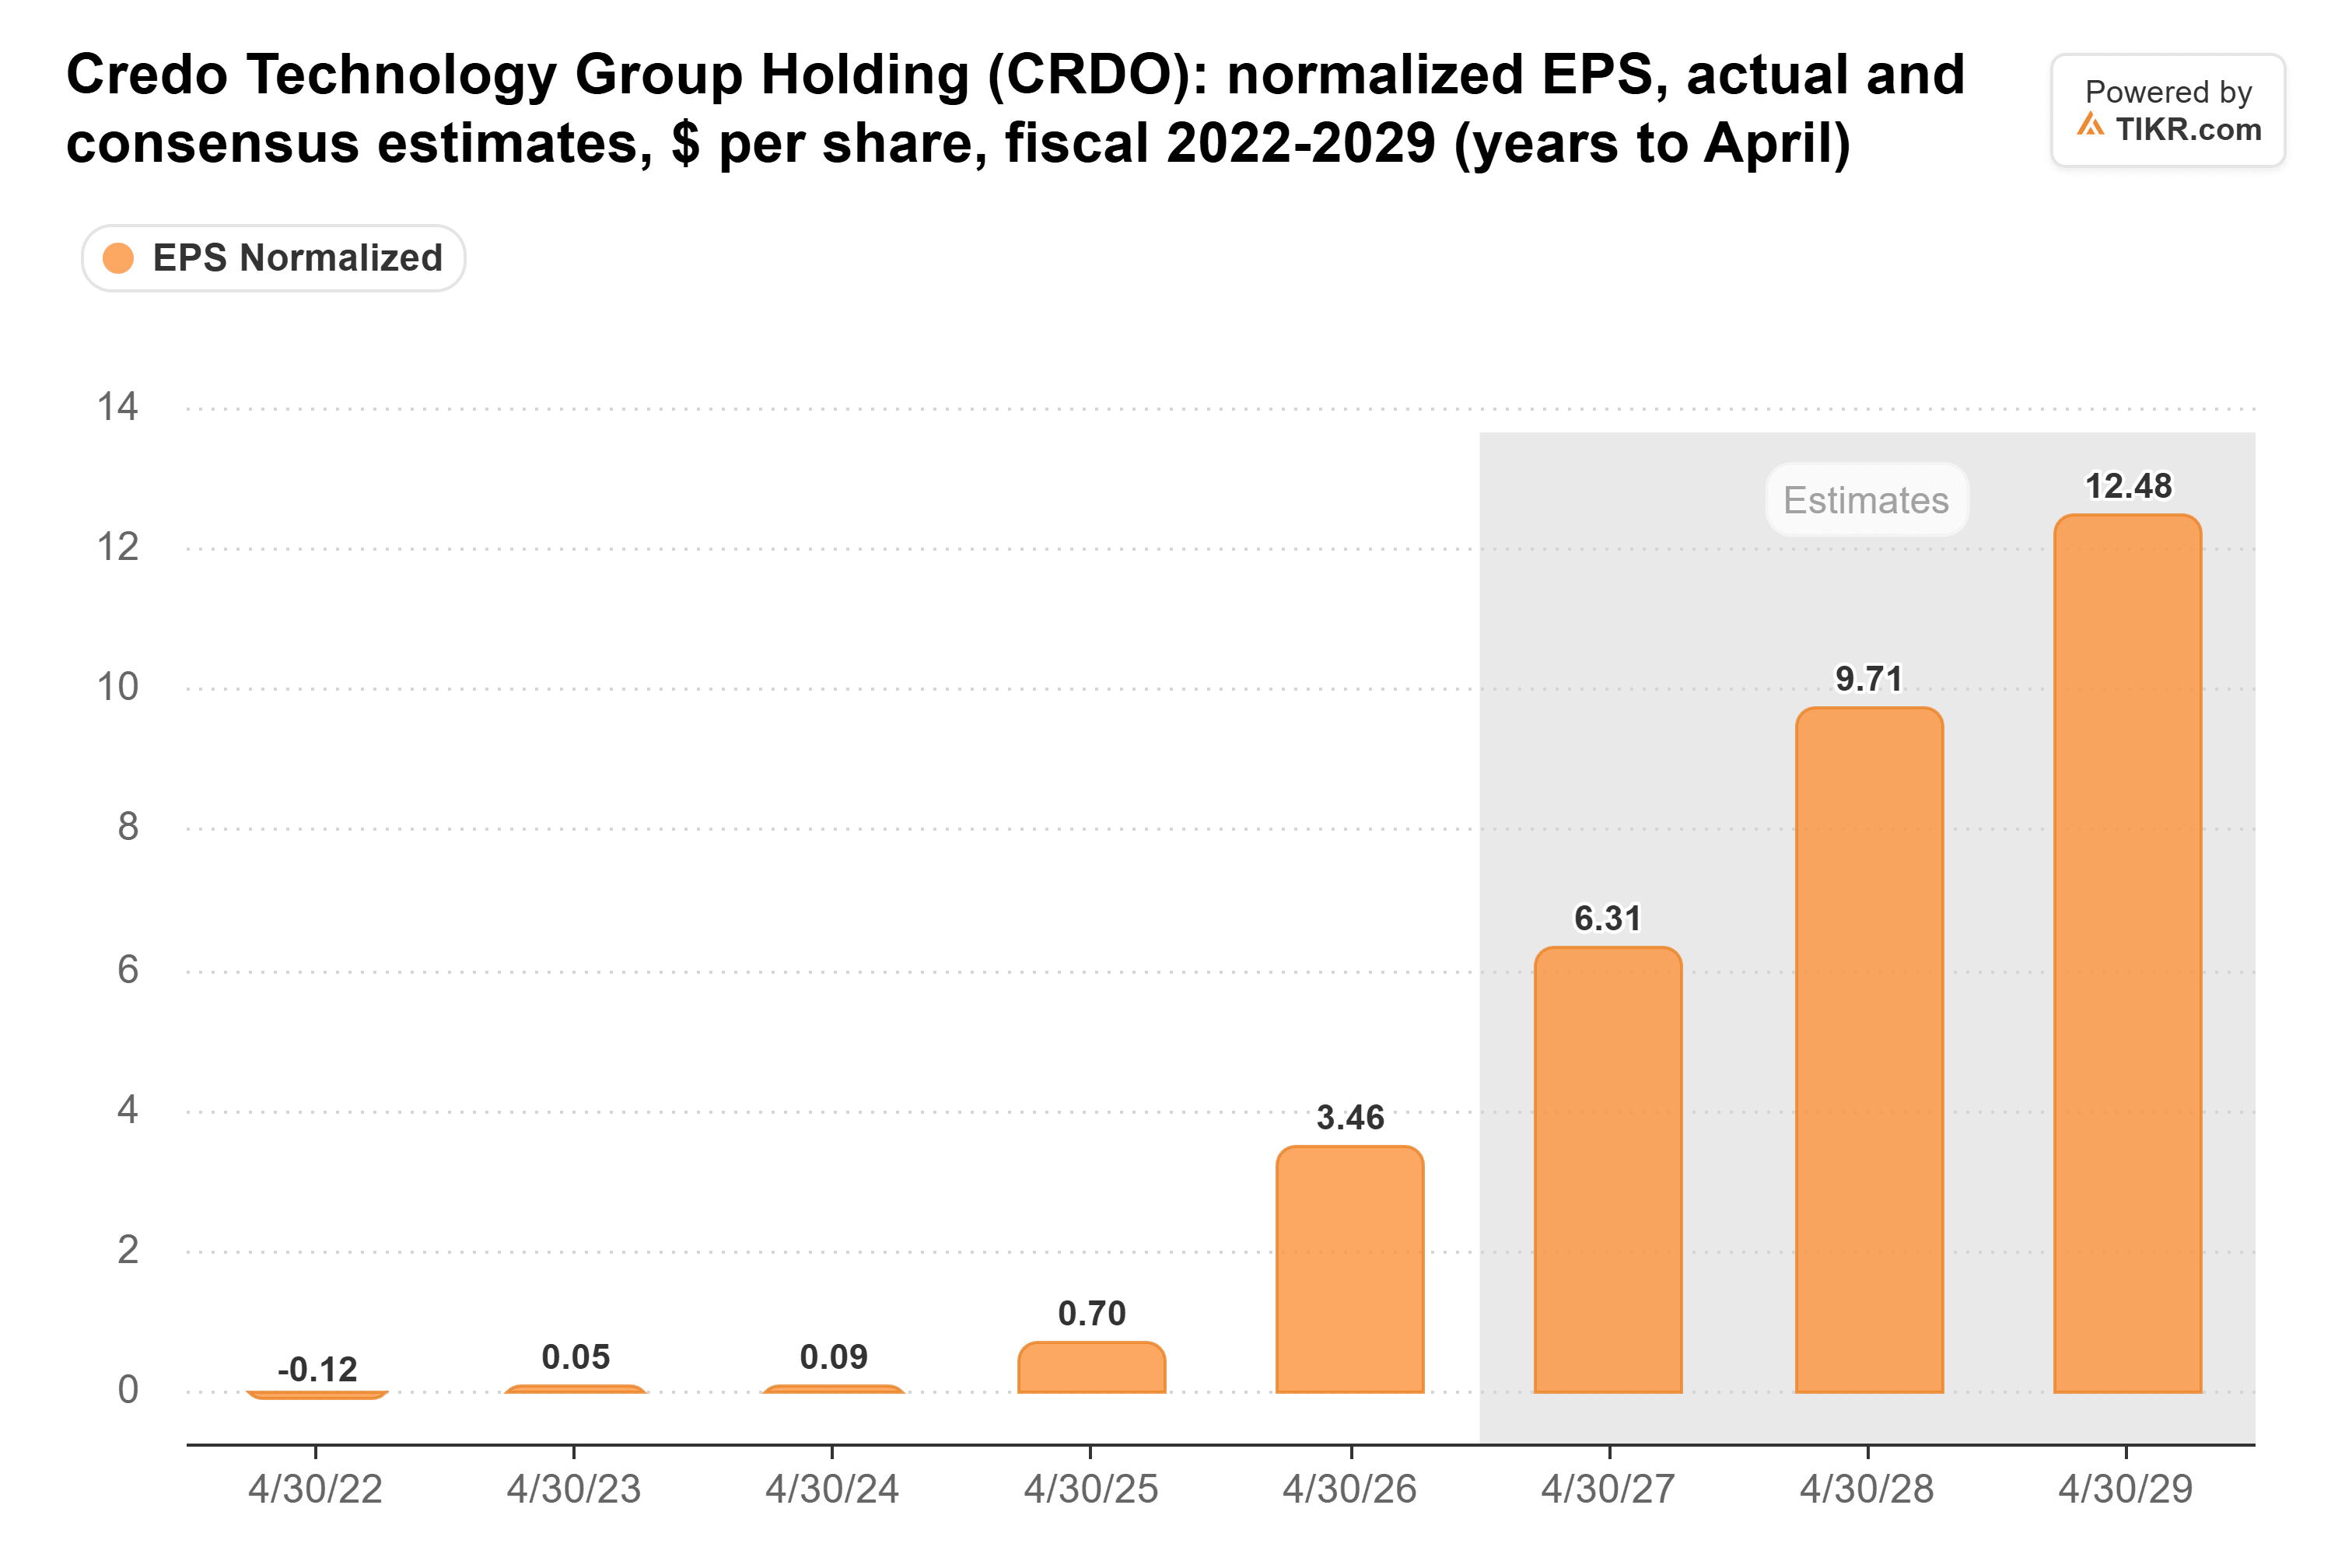
Those estimates predate this week, and nothing Credo has said since gives a reason to cut them.
But investors are paying far less for those earnings than they used to. Credo trades at 17x forward earnings, against a three-year average of 61x:
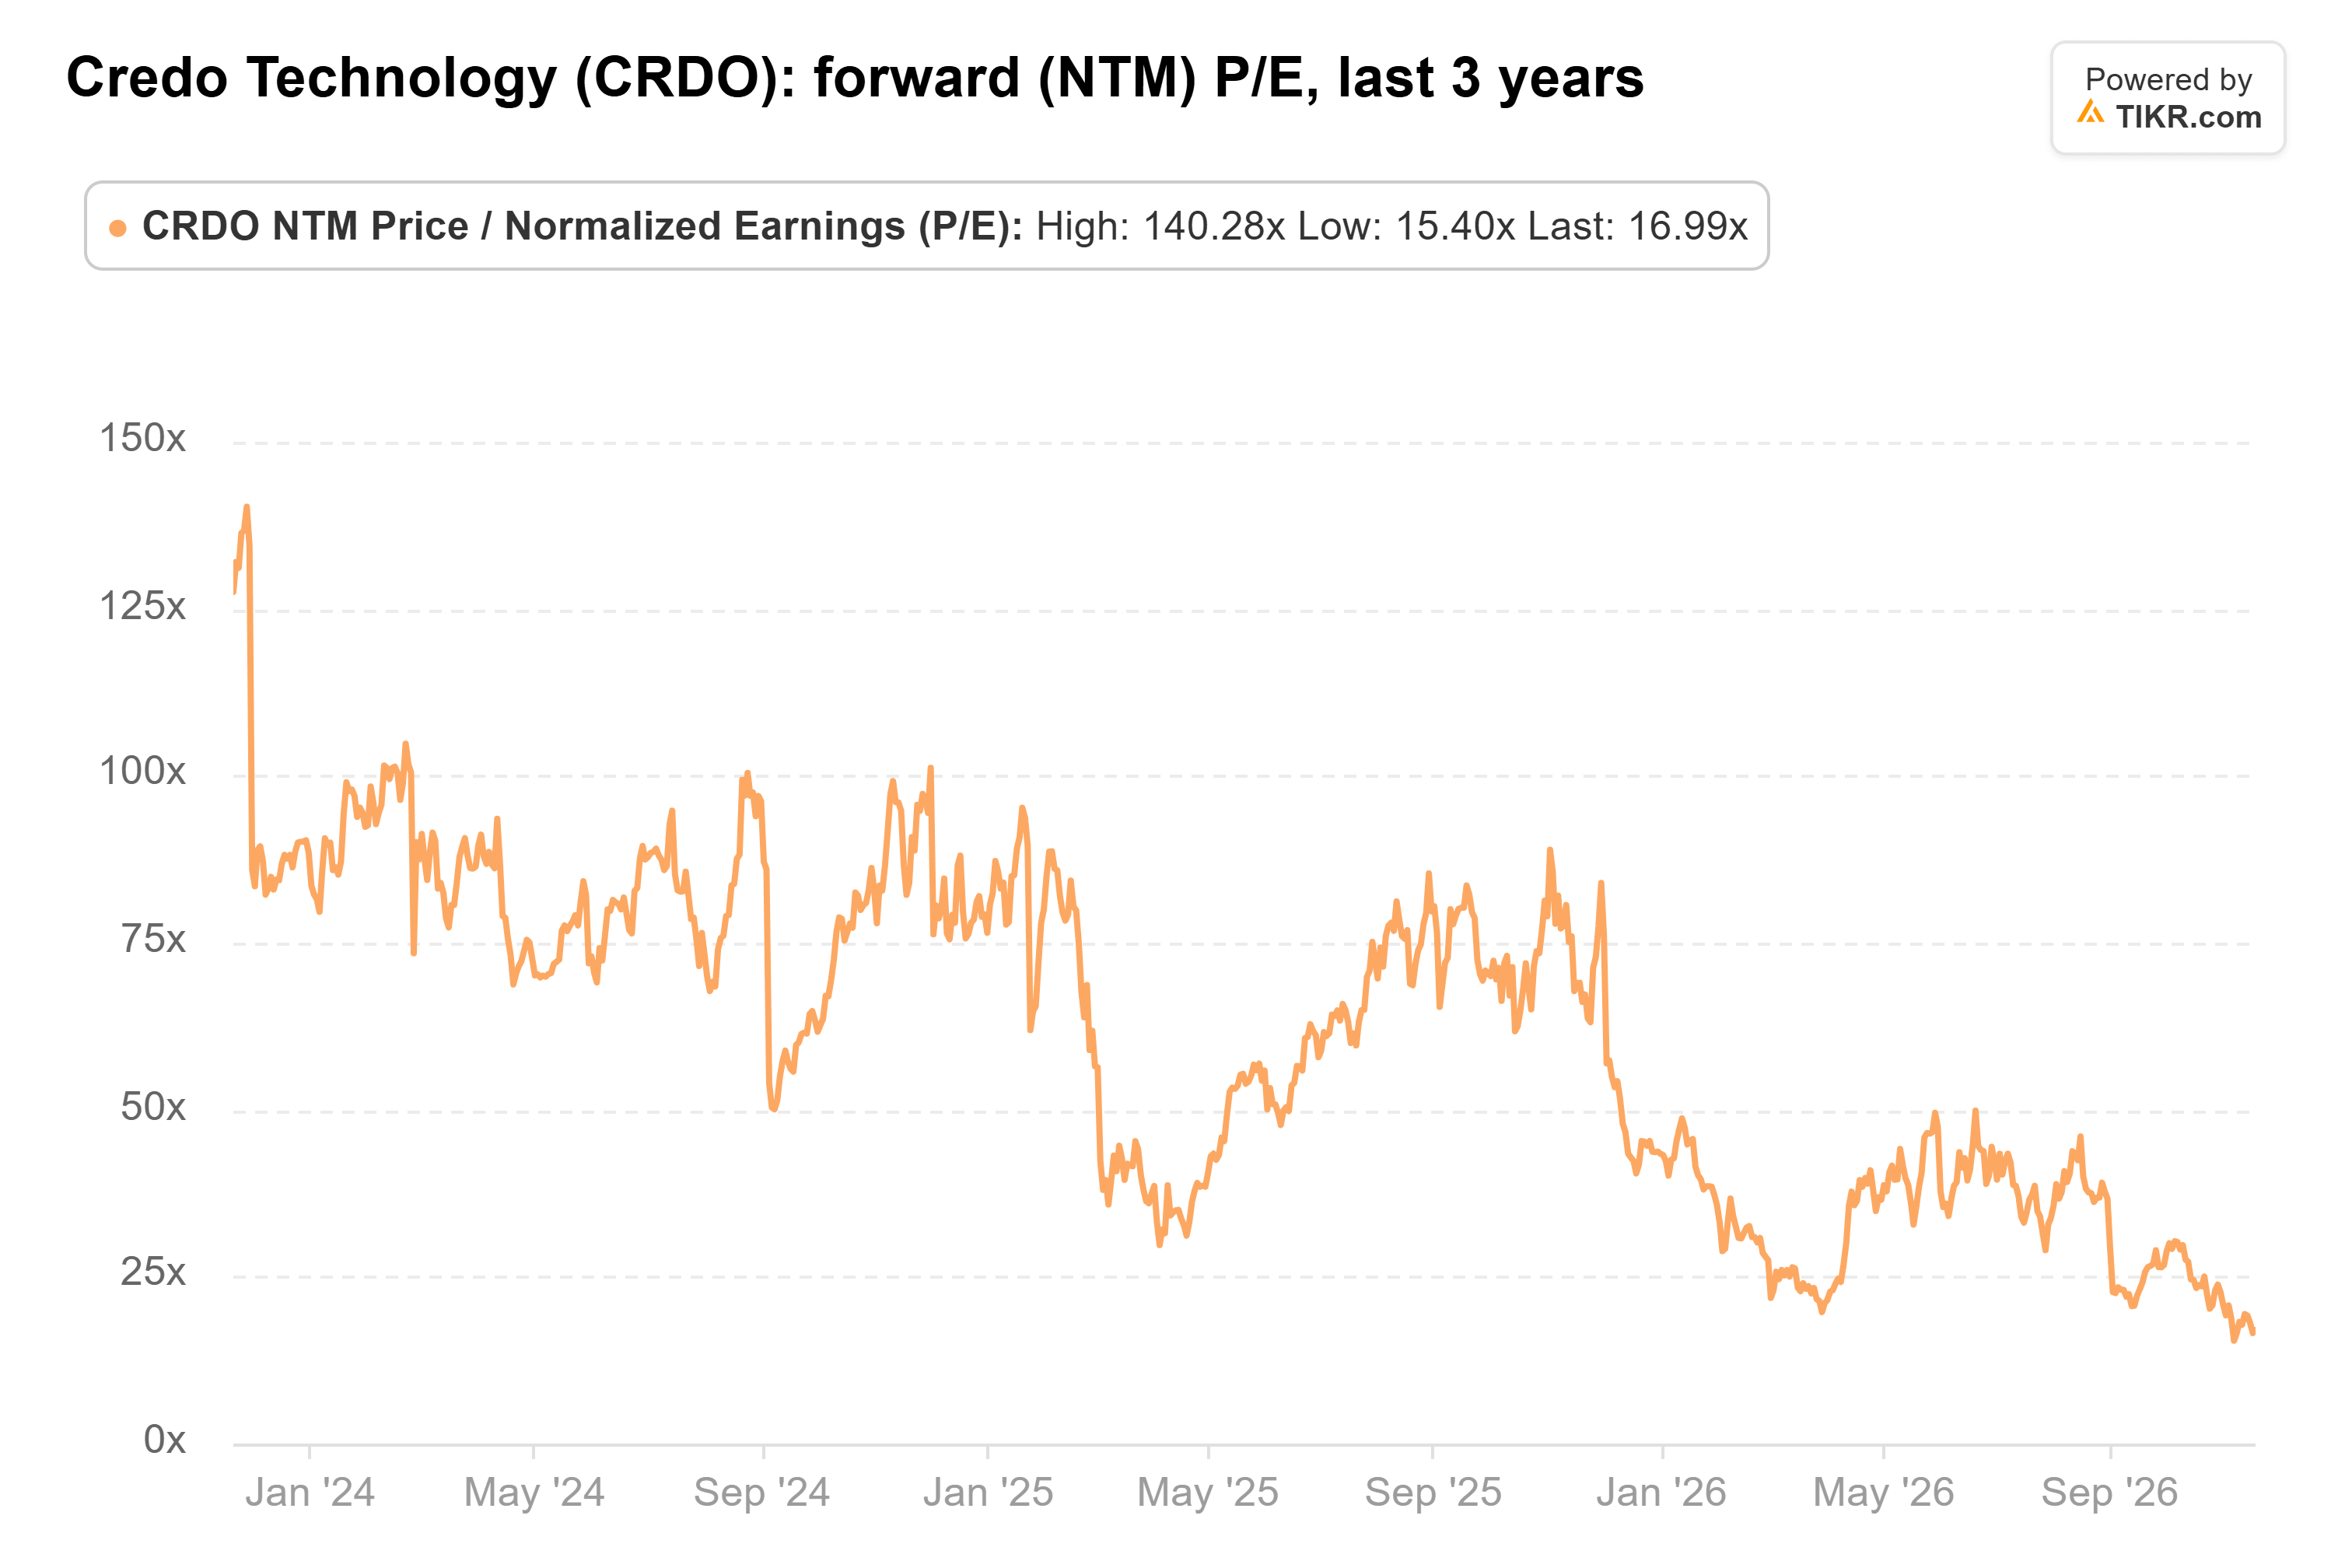
By my math, TD Cowen’s $175 is 18x fiscal 2028 EPS, close to today’s multiple. So the target only needs the estimates to hold.
Credo reports after the close on Dec. 1. Its target of more than 85% revenue growth this fiscal year needs at least $1.46 billion in the second half. That’s about $730 million a quarter, against a Q2 guide of $525 million to $535 million. Four customers bought 84% of Q1 revenue, so a pause at any one of them would show up fast.
Frankly, at 17x, Credo is priced like it’s about to lose its cable business, and this week it ended a patent fight over that very business.
I’d buy ahead of Dec. 1, though a modest Q3 guide could keep the stock stuck for months.
So what is Credo Technology stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Credo Technology could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Credo Technology for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!