Key Takeaways
- Bernstein kept its Outperform rating and $376 price target on Vertiv on Nov. 17. That’s 99% above the last close, with the stock 50% below its May high.
- Vertiv’s third-quarter sales grew 61% and analysts have raised their earnings estimates, so the stock’s whole drop has come from a lower valuation.
- Bernstein’s target works out to about 41x forward earnings, well above Vertiv’s five-year average of 27x.
- A rebound looks reasonable, but $376 within a year looks too optimistic. The Feb. 10 report, with Vertiv’s first 2027 guidance, is the next test.
Vertiv Holdings (VRT) just grew its sales 61%, and its stock is still 50% below its May high. On Nov. 17, Bernstein kept its Outperform rating and $376 price target, 99% above Vertiv’s $188.67 close on Nov. 16.
A strong quarter, then the midterms
On July 29, second-quarter sales of $3.27 billion missed the $3.35 billion midpoint of guidance, and the stock fell 17% that day. On Oct. 28, Vertiv reported 61% sales growth and organic orders up more than 100%, and raised its full-year sales guidance by $650 million. Then Democrats won Congress on Nov. 3, which brought back fears that Washington could slow data-center construction. Vertiv fell 14% on Nov. 5.
Bernstein sees a small dent
Bernstein raised its target to $376 from $368 the day after the report. It noted that investors were raising their 2027 EPS estimates to around $11 or more. After the midterms, it sized the hit to US data-center capacity at just 2% to 4%.
TIKR tracks 31 analysts on Vertiv. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Vertiv, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Vertiv’s Analyst Ratings
Does $376 add up?
The consensus target from the 31 analysts covering Vertiv has risen from $197 a year ago to $334. That’s still below its July peak of $381:
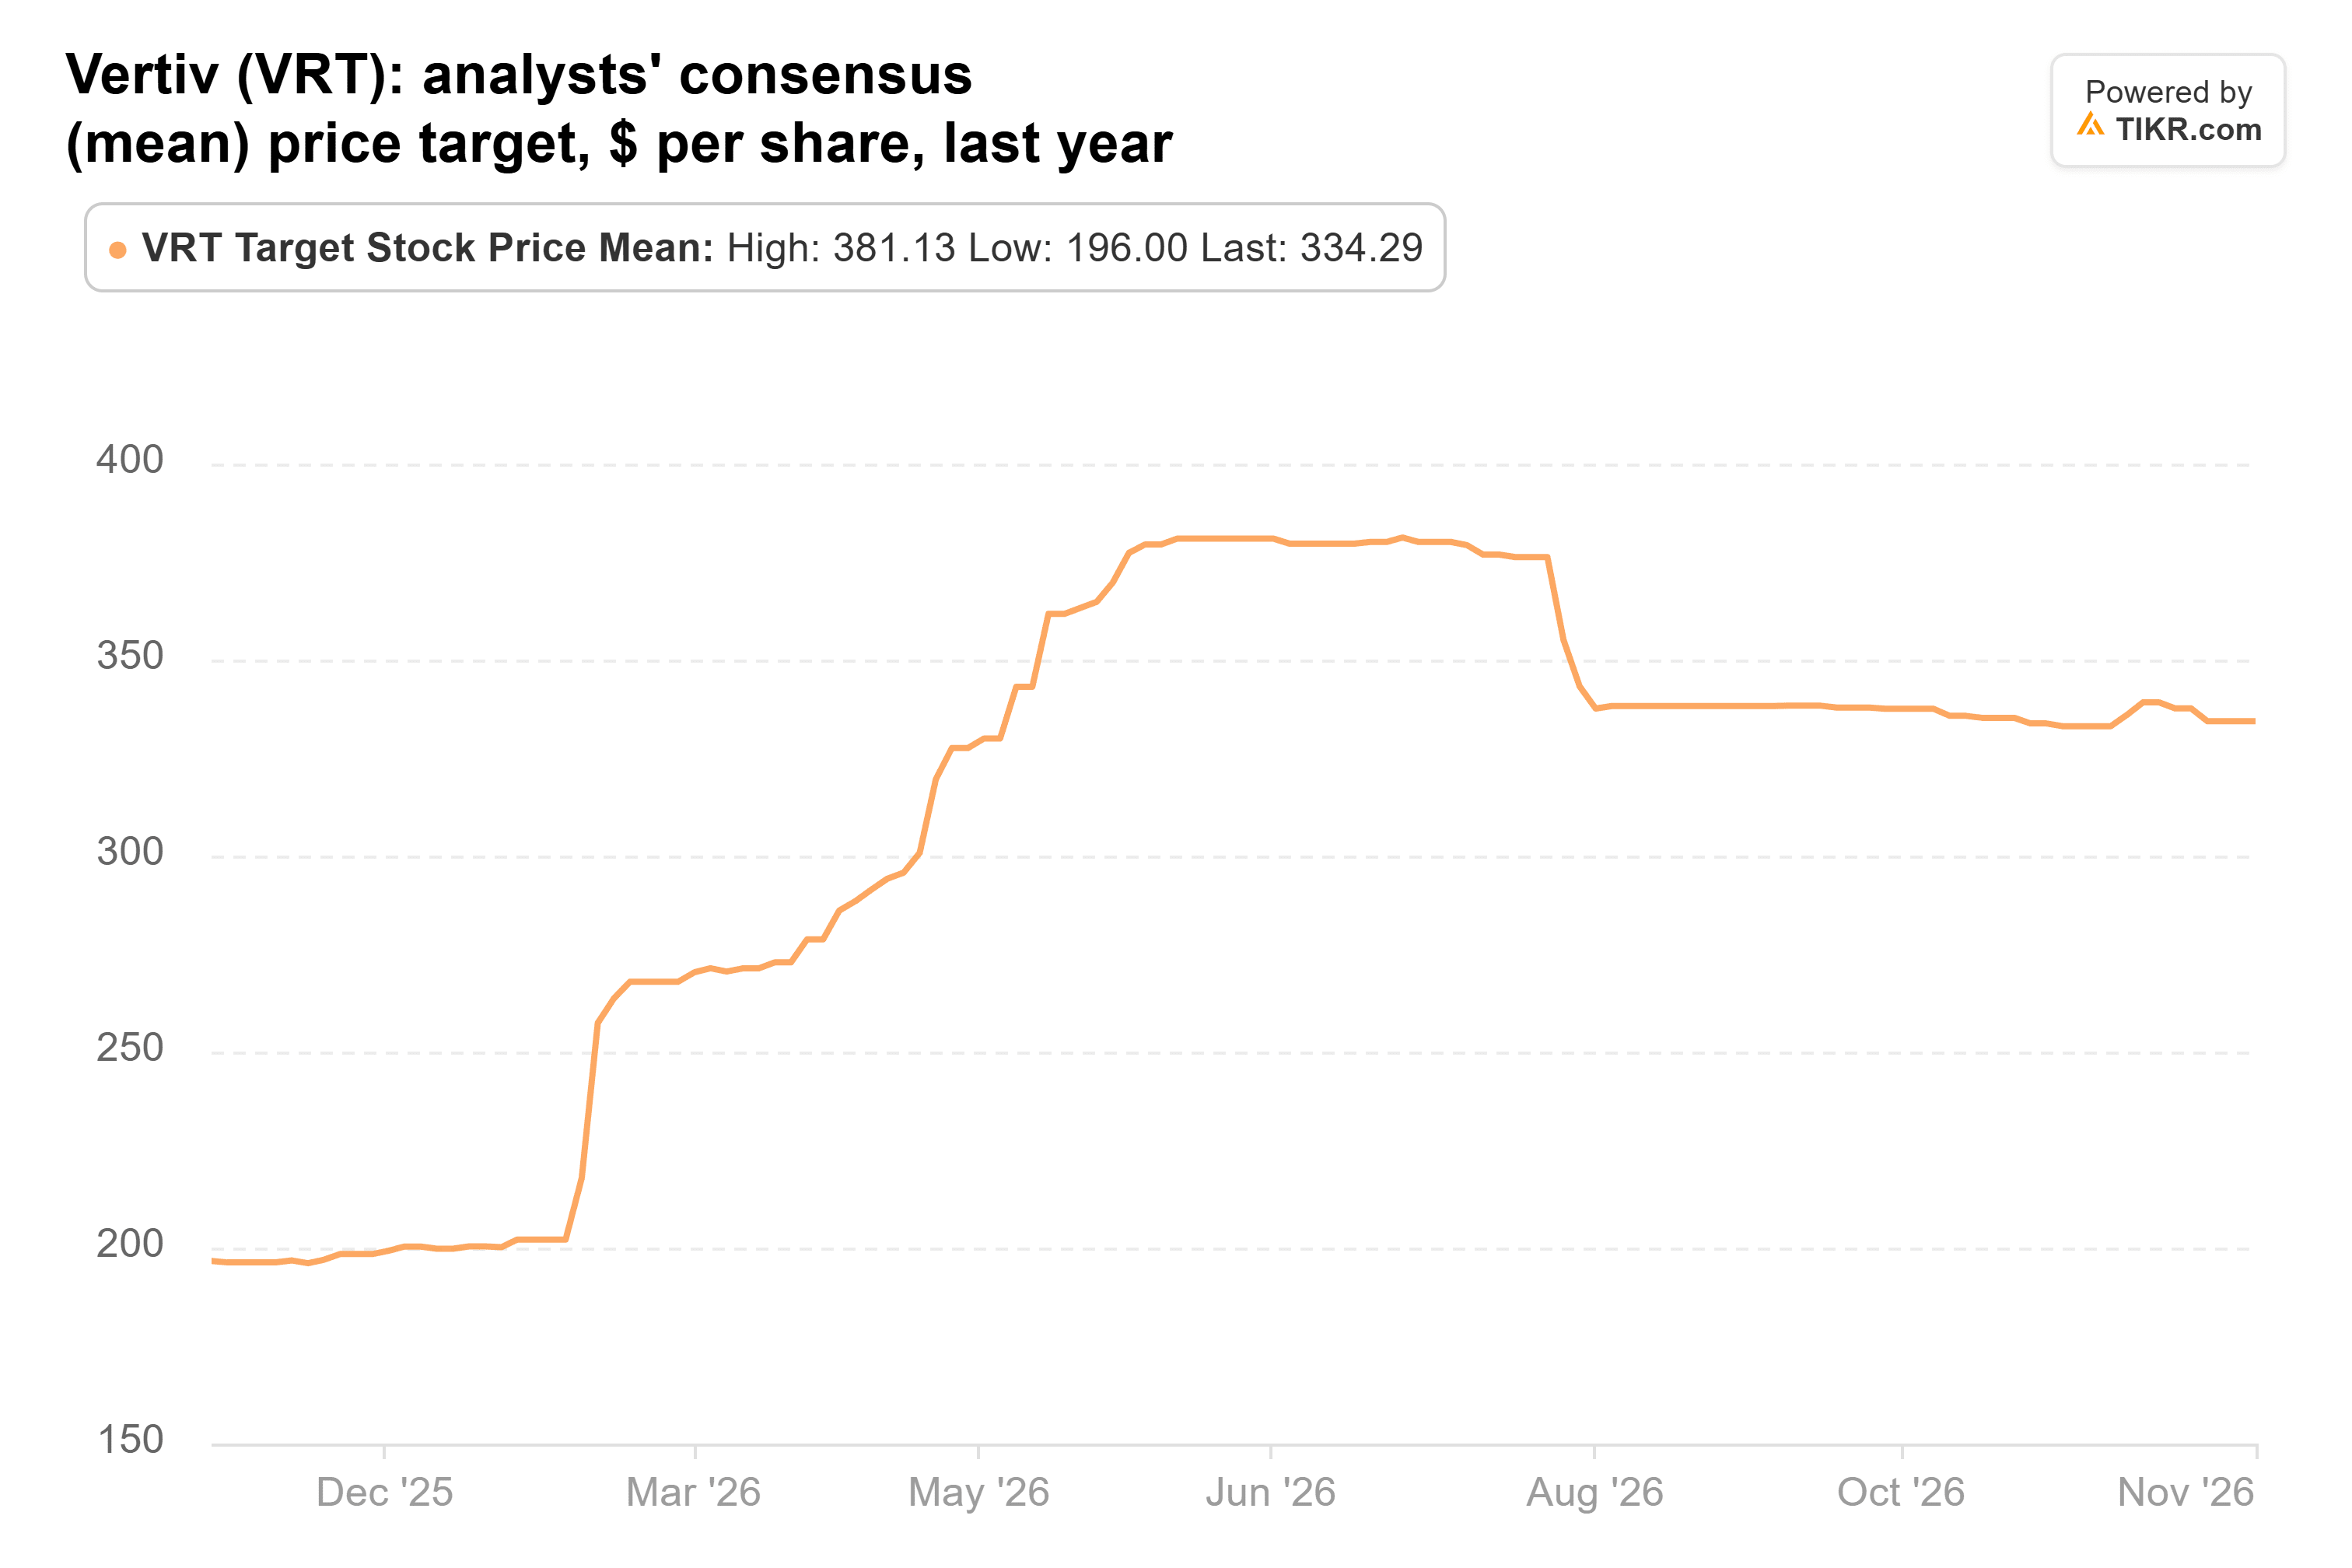
That’s 77% above the price. Bernstein’s $376 is 13% higher still.
Analysts expect normalized EPS to grow from $4.20 in 2025 to $7.19 this year and $9.87 in 2027:
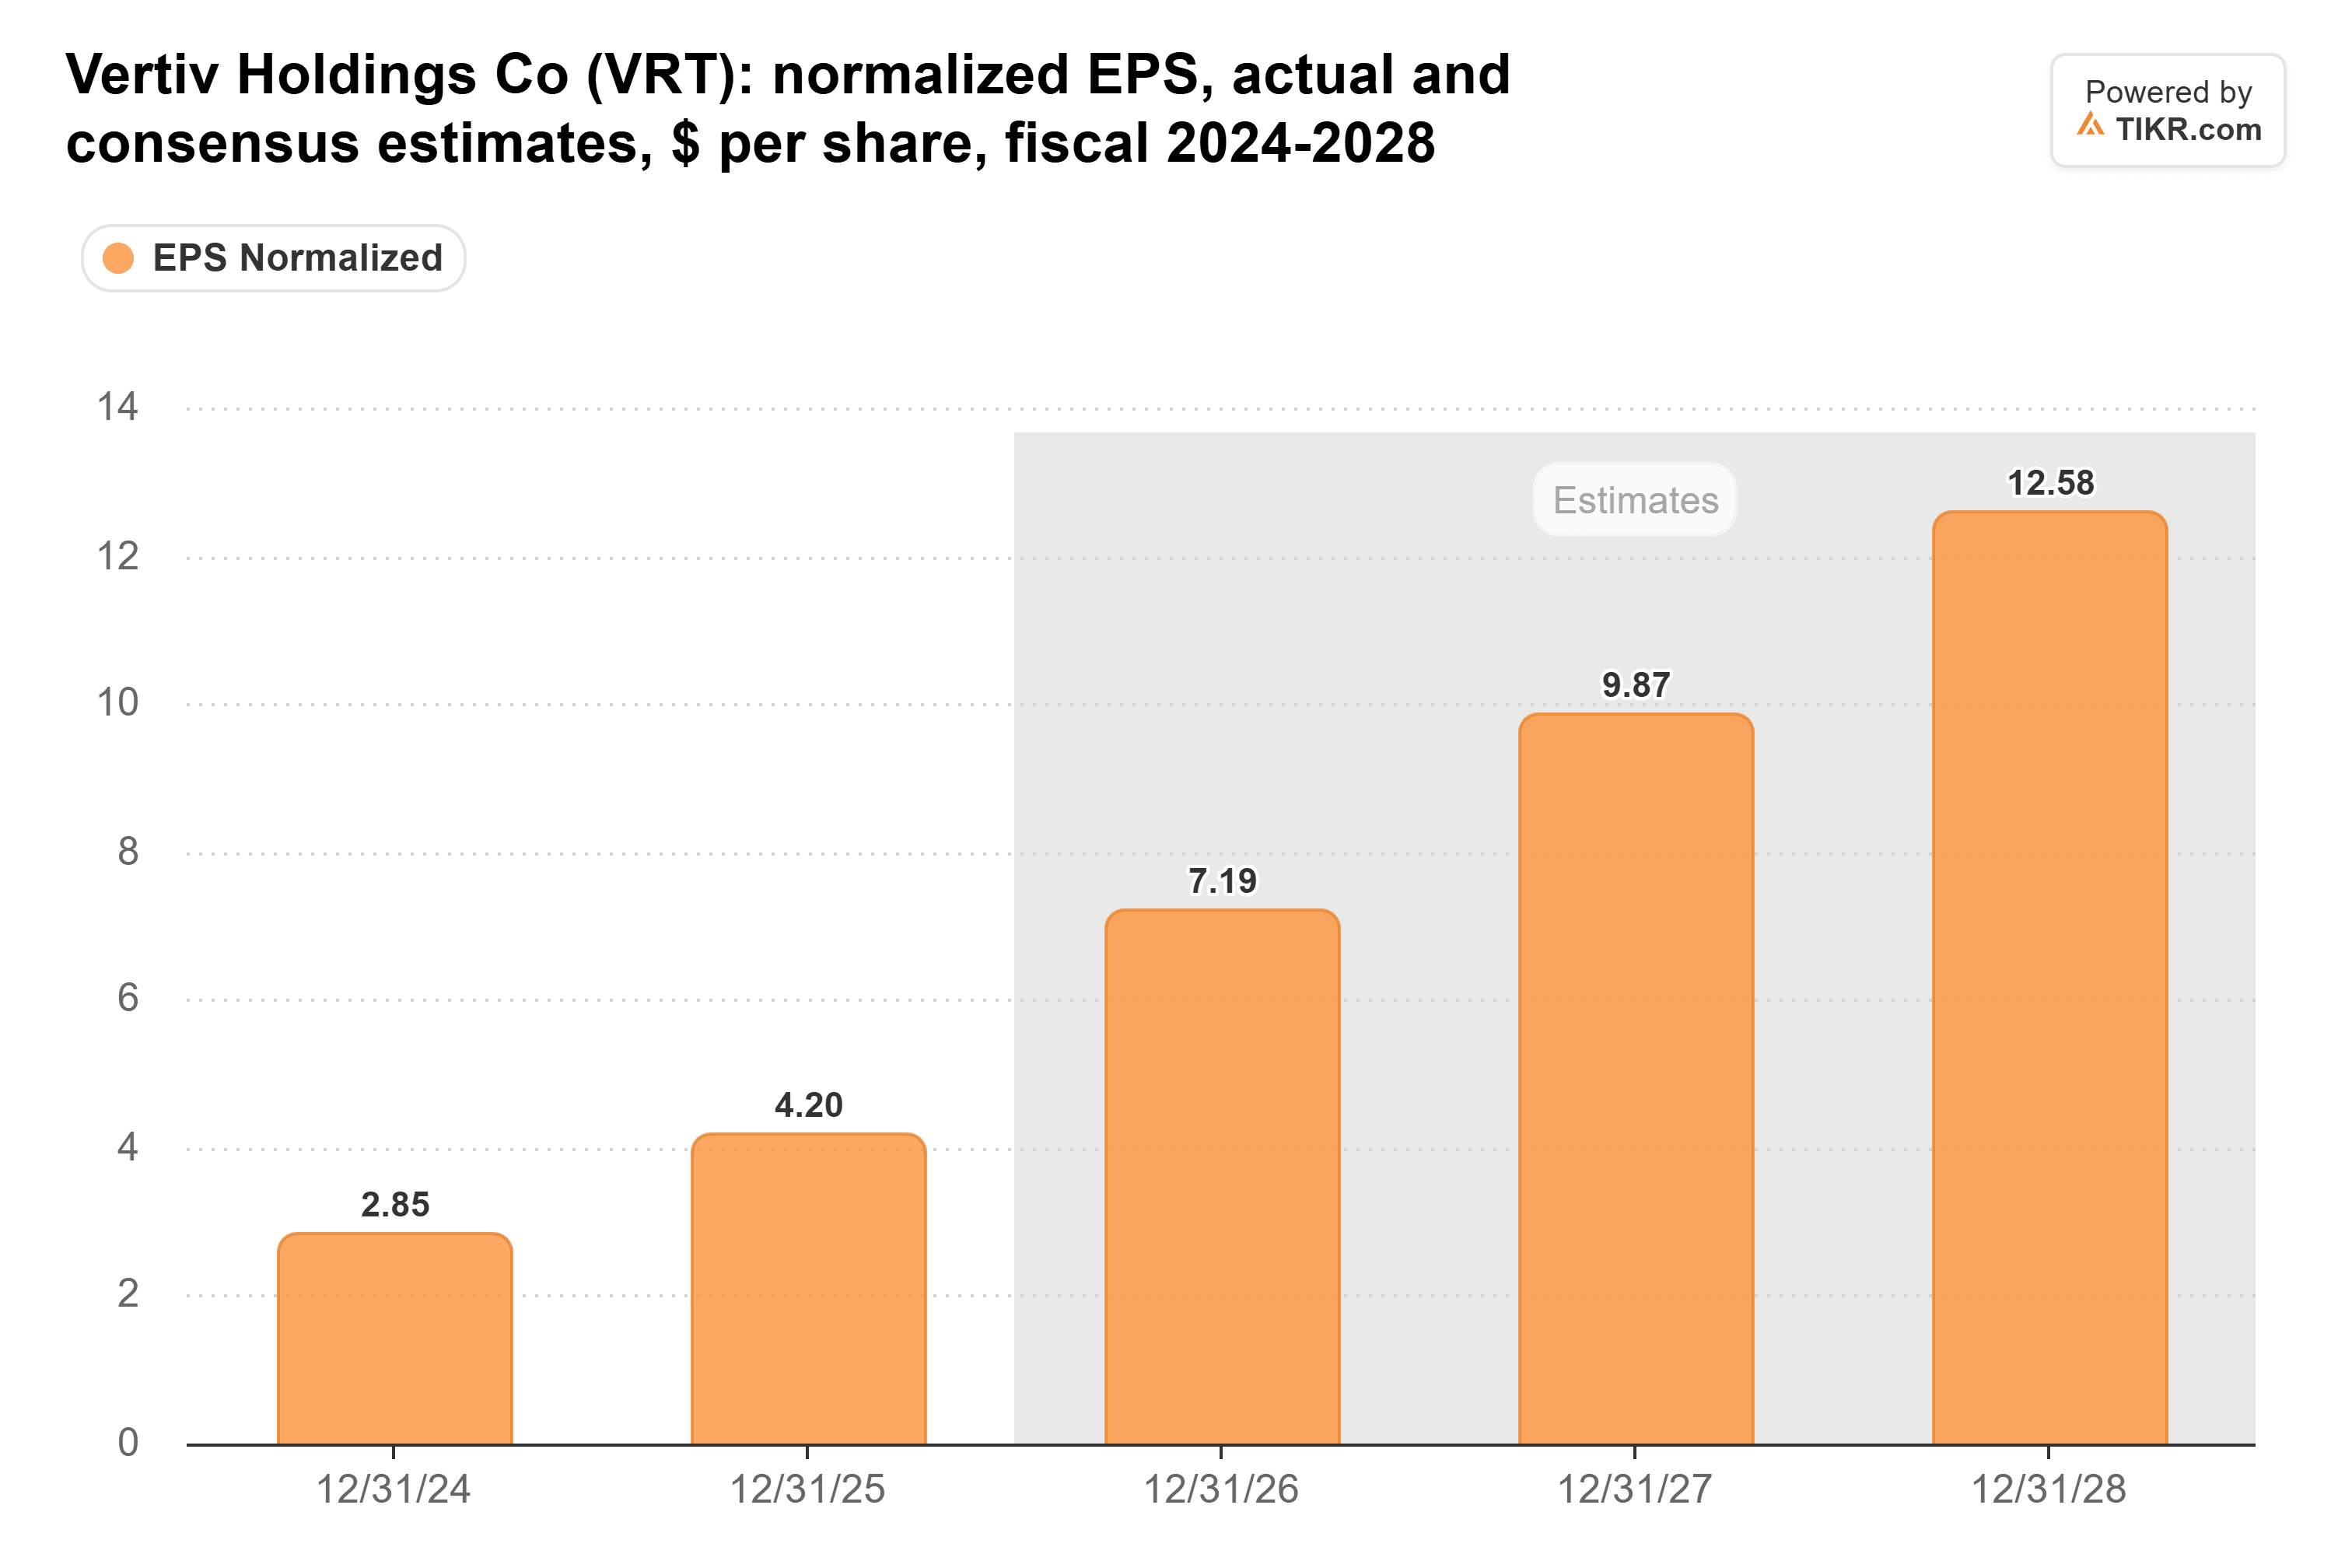
That 2027 figure is up from $9.19 a month ago, though it’s still short of the $11 Bernstein mentioned. Since estimates have risen, the whole drop since May has come from the multiple. Vertiv now trades at [20x] forward earnings, below its five-year average of 27x and far from the 55x it hit on May 14:
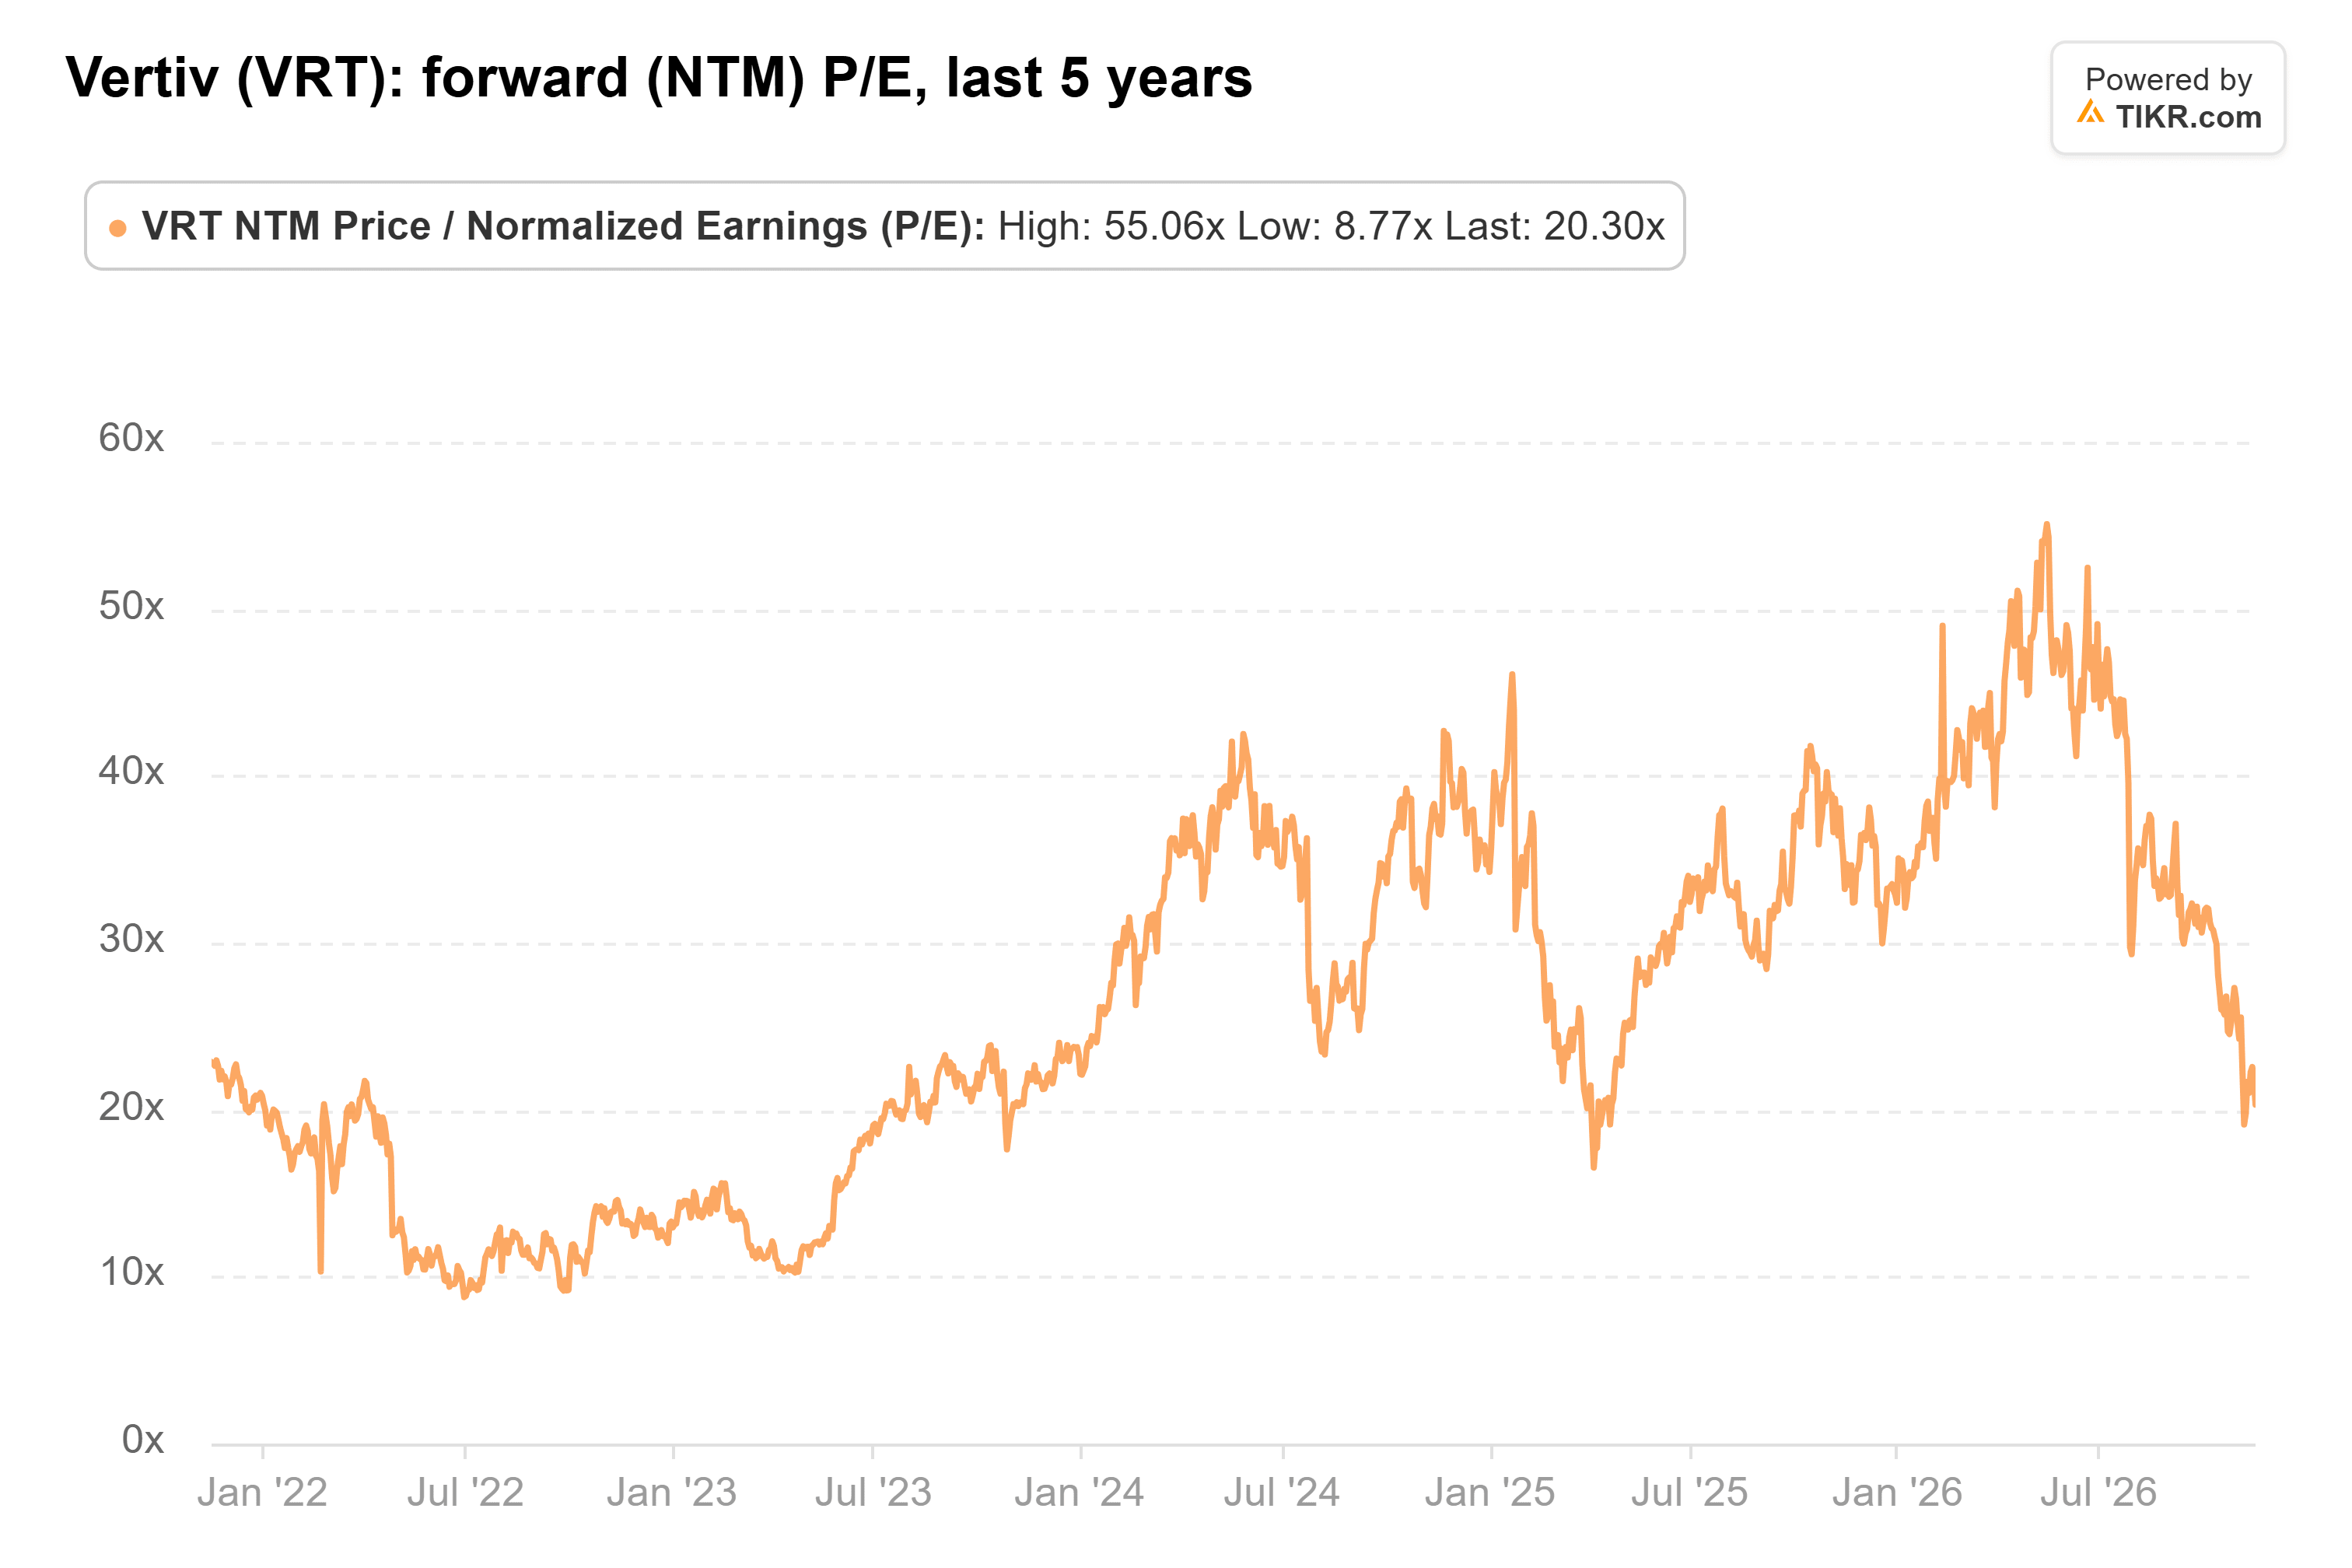
Bernstein’s target works out to about 41x the $9.29 a share analysts expect over the next twelve months.
Cheap, but $376 is a big ask
The main risk: Executive Chairman Dave Cote said on the call that Vertiv is “not planning to share orders data going forward,” so investors will have less to go on if Washington or tighter AI financing slows orders.
Bernstein isn’t totally wrong. Estimates are rising and the stock trades below its usual multiple, so a rebound makes sense to me. But to hit $376 within a year, investors would have to pay about 41x again while the politics are unsettled.
The next test is the fourth-quarter report on Feb. 10, which should bring Vertiv’s first 2027 guidance. If management guides near or above the $9.87 consensus and Washington stays quiet, I’d find Bernstein’s $376 a lot easier to believe.
So what is Vertiv stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Vertiv could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!