Key Takeaways
- Goldman Sachs kept its Buy rating and $177 target on Alibaba after the Nov. 19 report, 112% above that day’s close and after a 53% fall from January’s high.
- Cloud revenue grew 53% with a 14.5% margin, but adjusted earnings missed estimates. The same day, PDD Holdings’ merchant ad revenue grew 12%, three days after Baidu’s AI cloud infrastructure revenue grew 94%.
- On analysts’ estimates, $177 works out to about 19x fiscal 2028 earnings, against a five-year average of about 13x, so most of the upside depends on investors paying a higher multiple.
- Roughly $120 looks like a fairer goal for now, and the U.S. chip rule that took effect on report day is the risk that could cap the cloud.
Alibaba (BABA) stock closed at $83.31 on Nov. 19, 53% below its January closing high. Goldman Sachs analyst Ronald Keung kept his Buy rating and $177 target on Nov. 18, and again after the company’s September-quarter report on Nov. 19. That’s 112% above the close.
The report landed the same day PDD Holdings (PDD) said its online marketing revenue grew 12%. It also came three days after Baidu (BIDU) said its AI cloud infrastructure revenue grew 94%.
A big bill, then a chip rule
The latest leg down started with the June-quarter report on Aug. 20. Capital spending jumped 75% to RMB 67.7 billion, and adjusted EBITA fell 30%. The fees Taobao and Tmall collect from merchants grew just 1% like-for-like.
On Nov. 16, the Commerce Department issued a rule requiring a license to ship advanced chips to data centers abroad that sell large amounts of computing to Chinese companies. The rule targets the rented offshore computing Alibaba’s cloud reportedly uses, and it took effect Nov. 19, the day Alibaba reported.
Goldman’s bet is on the cloud
Before the report, Keung’s note cited “the potential for beats-and-raises over the next few quarters for Cloud & Compute Services.” The firm expects EPS to rise 59% in fiscal 2027 and 28% in fiscal 2028.
The cloud delivered. AI Cloud and Compute Services revenue grew 53% in the September quarter, up from 45% in June, and its adjusted EBITA margin rose to 14.5% from 11.6%. CFO Toby Xu credited “quality earnings” for the margin. Group adjusted earnings of $1.21 per ADS still fell short of the roughly $1.65 analysts expected, and the stock gave up early gains to close down 1.26%.
Analysts expect normalized EPS to get back to about fiscal 2024’s level by fiscal 2028, after it fell by more than half last fiscal year:
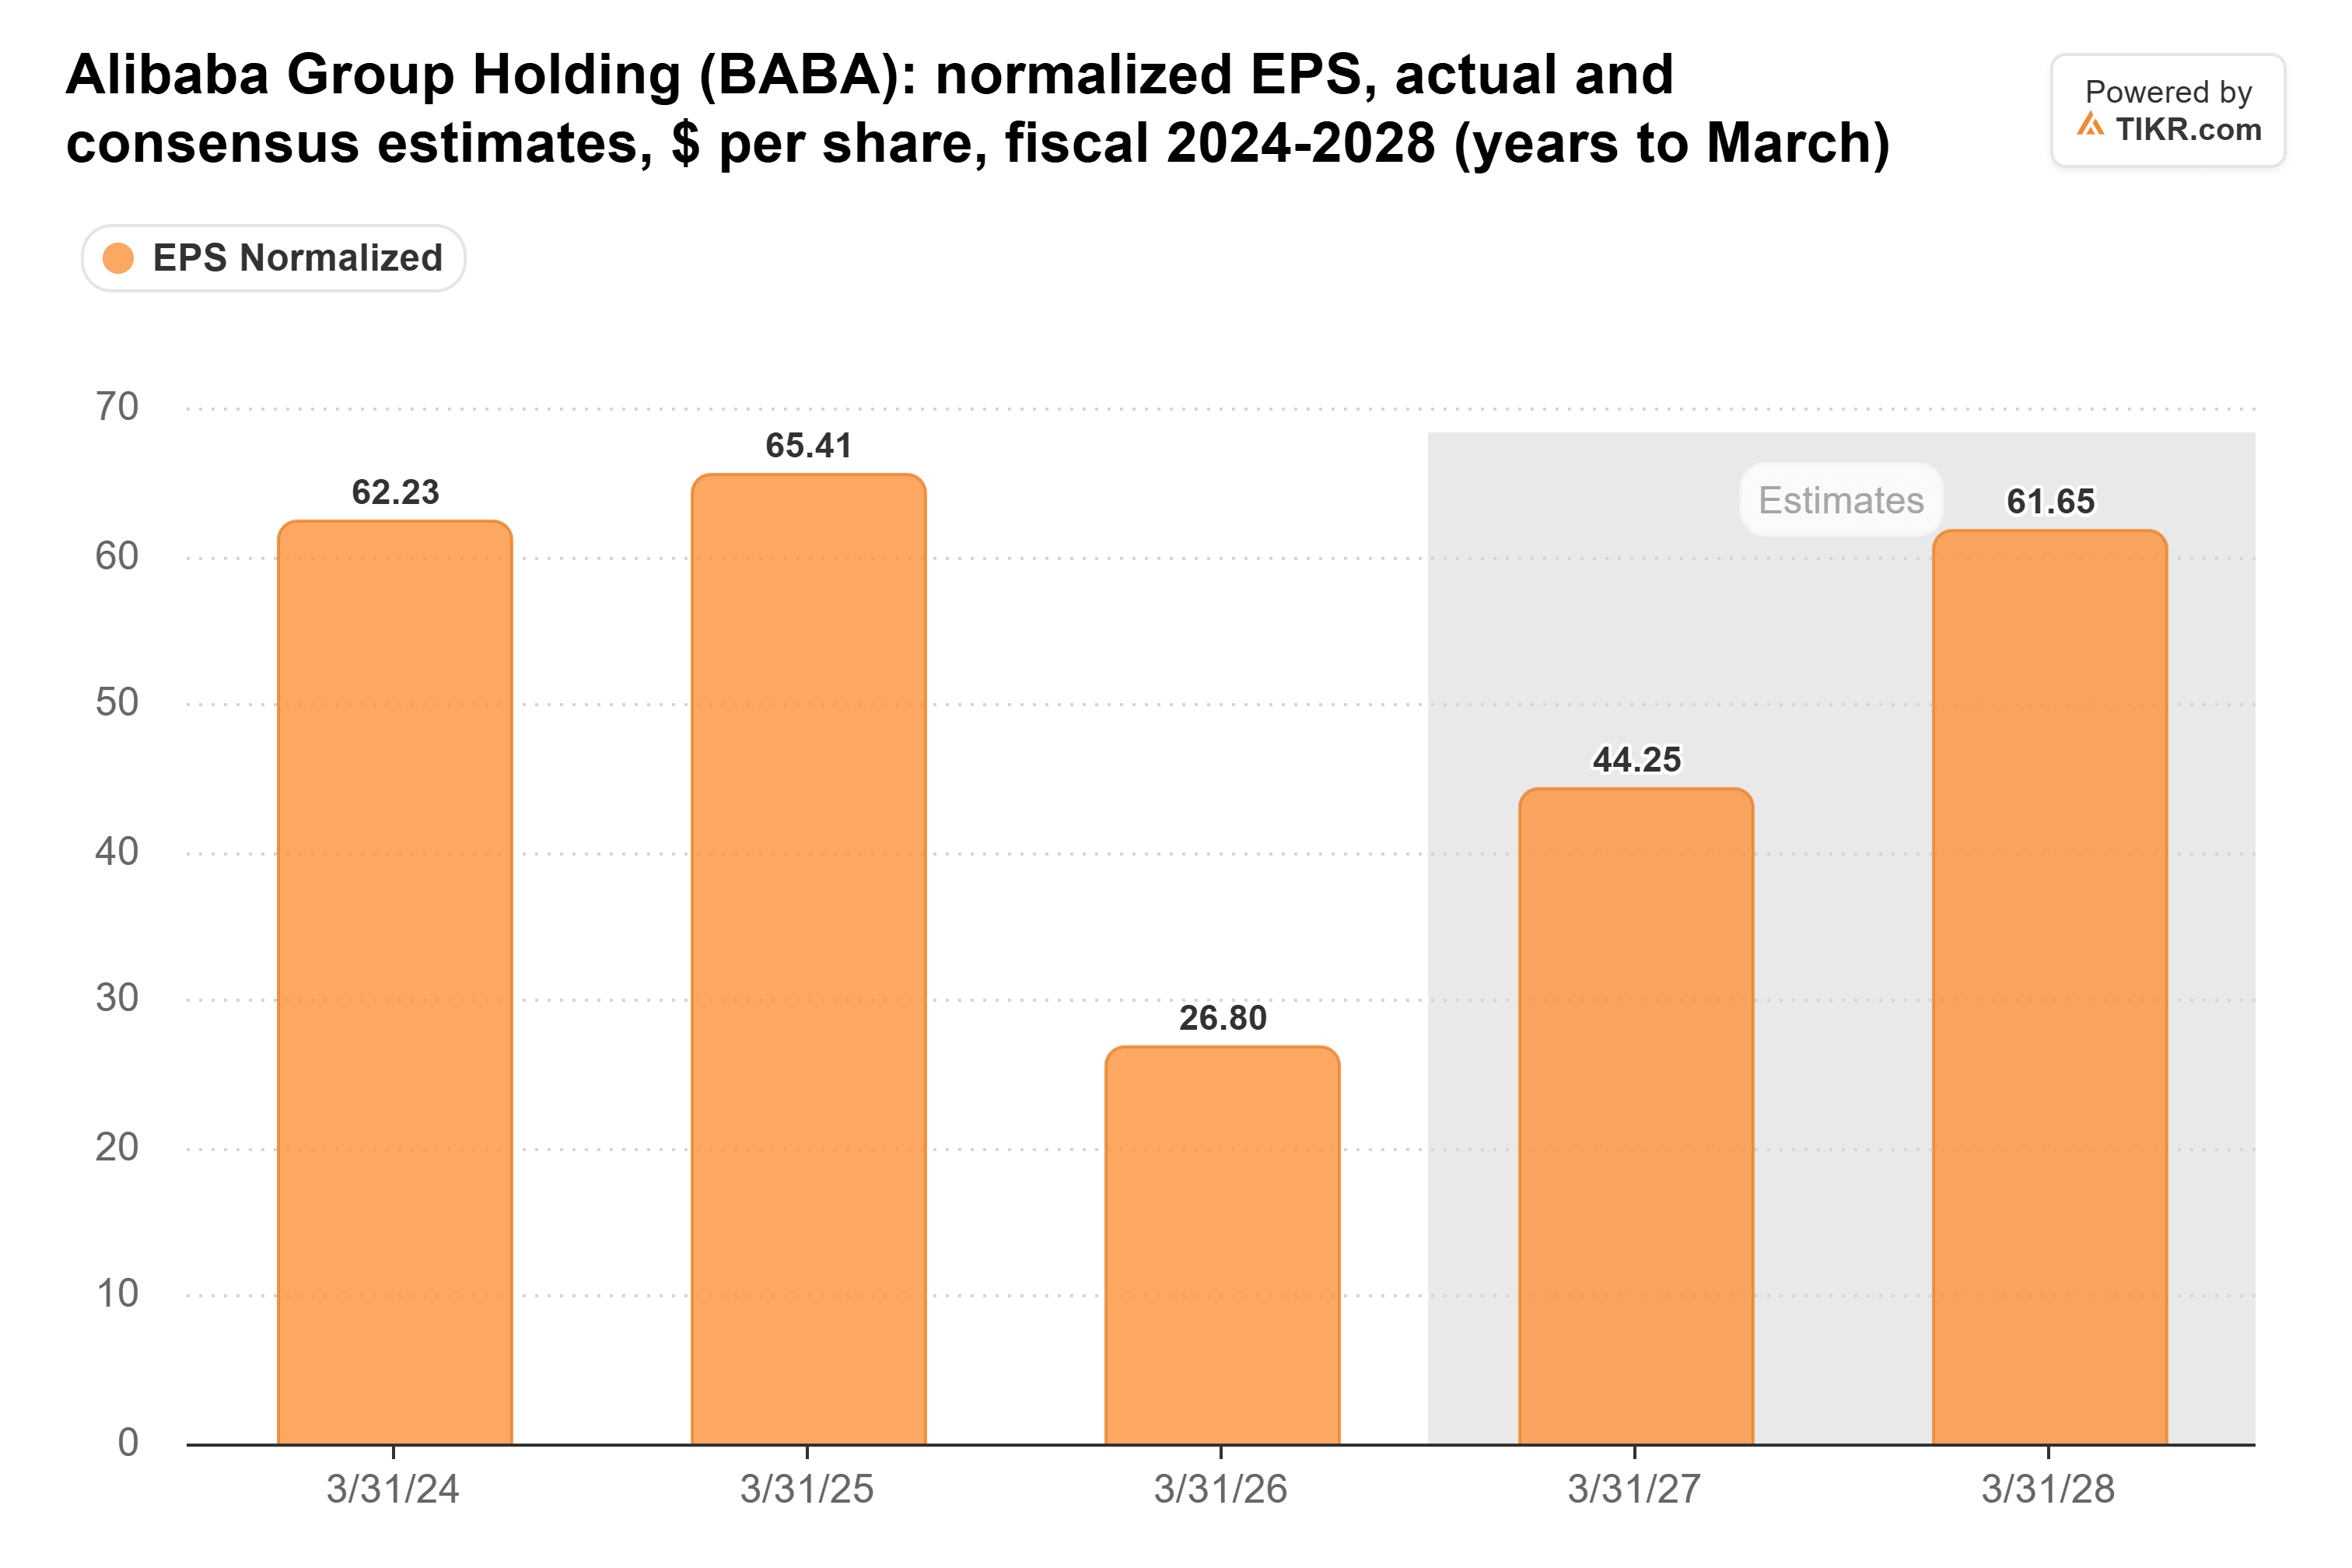
Those estimates barely moved in the three months before the report.
TIKR tracks 41 analysts on Alibaba. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alibaba, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alibaba’s Analyst Ratings
Does $177 add up?
The 40 analyst targets on Alibaba averaged $185 heading into the report, down from $198 at the end of 2025. TIKR’s chart tracks the same mean in RMB:
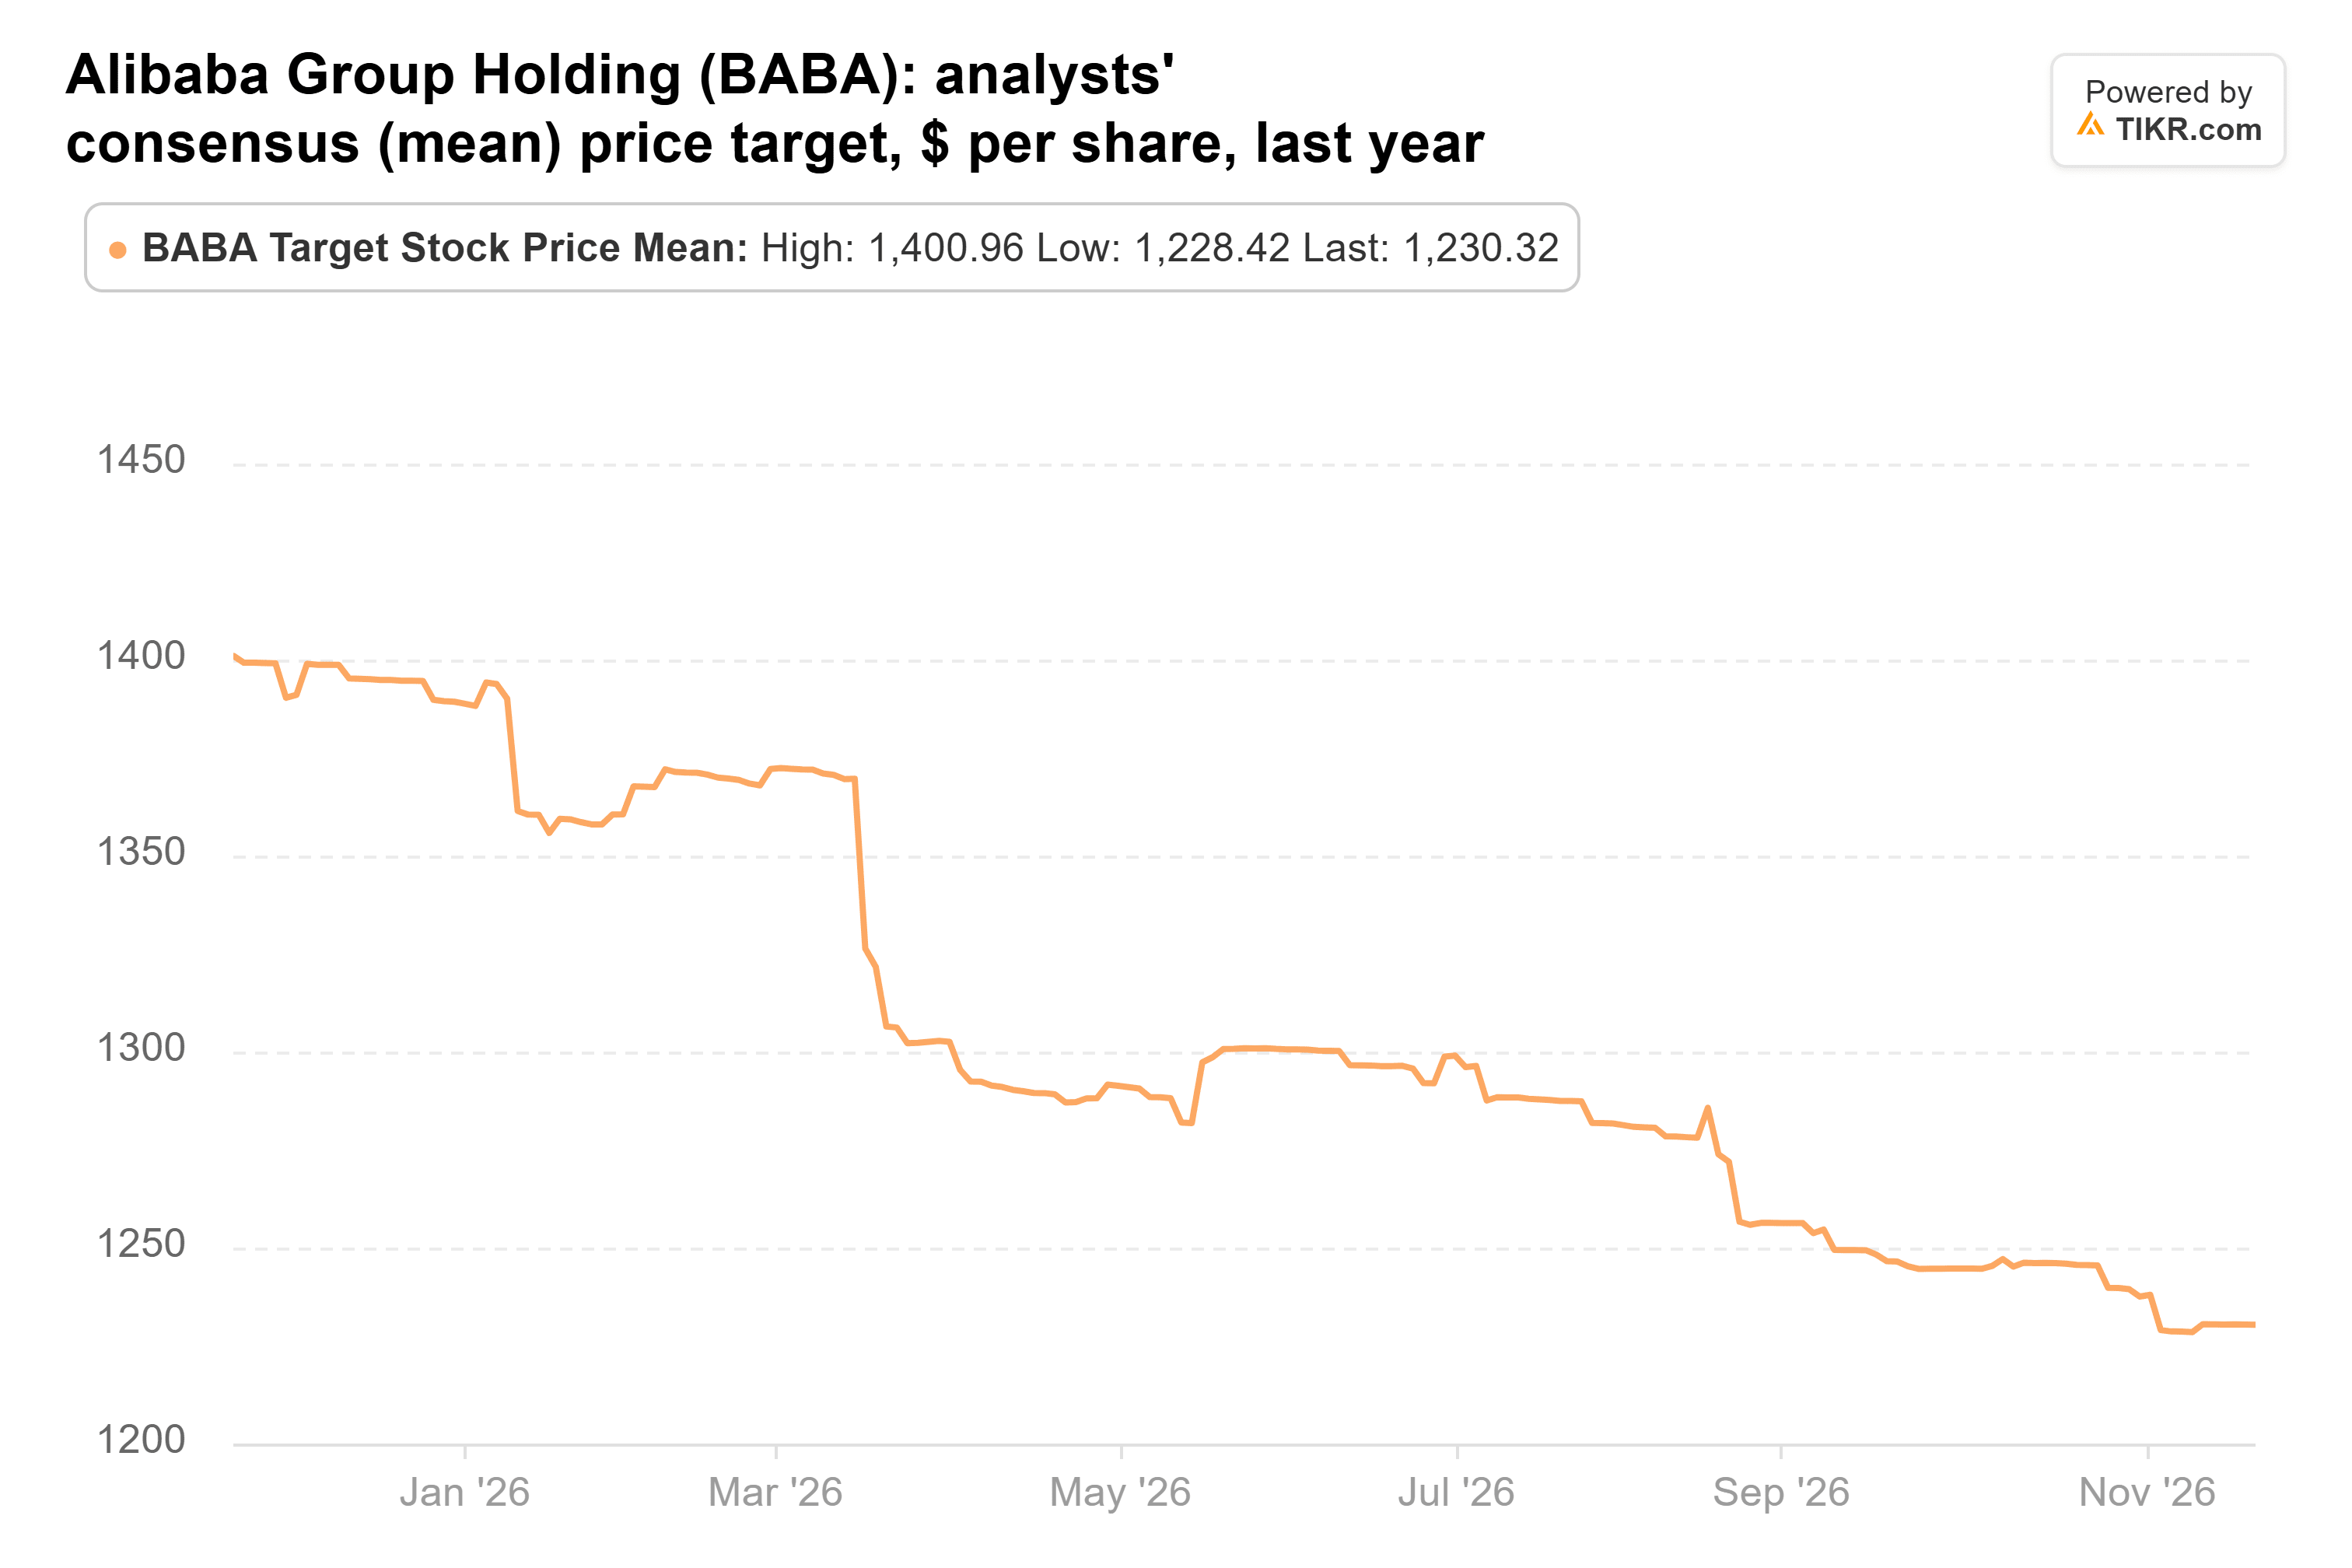
Goldman’s target is below that average. Converted to dollars, analysts’ fiscal 2028 estimate puts $177 at about 19x earnings. Alibaba traded at about 11x forward earnings before the report, against a five-year average of about 13x:
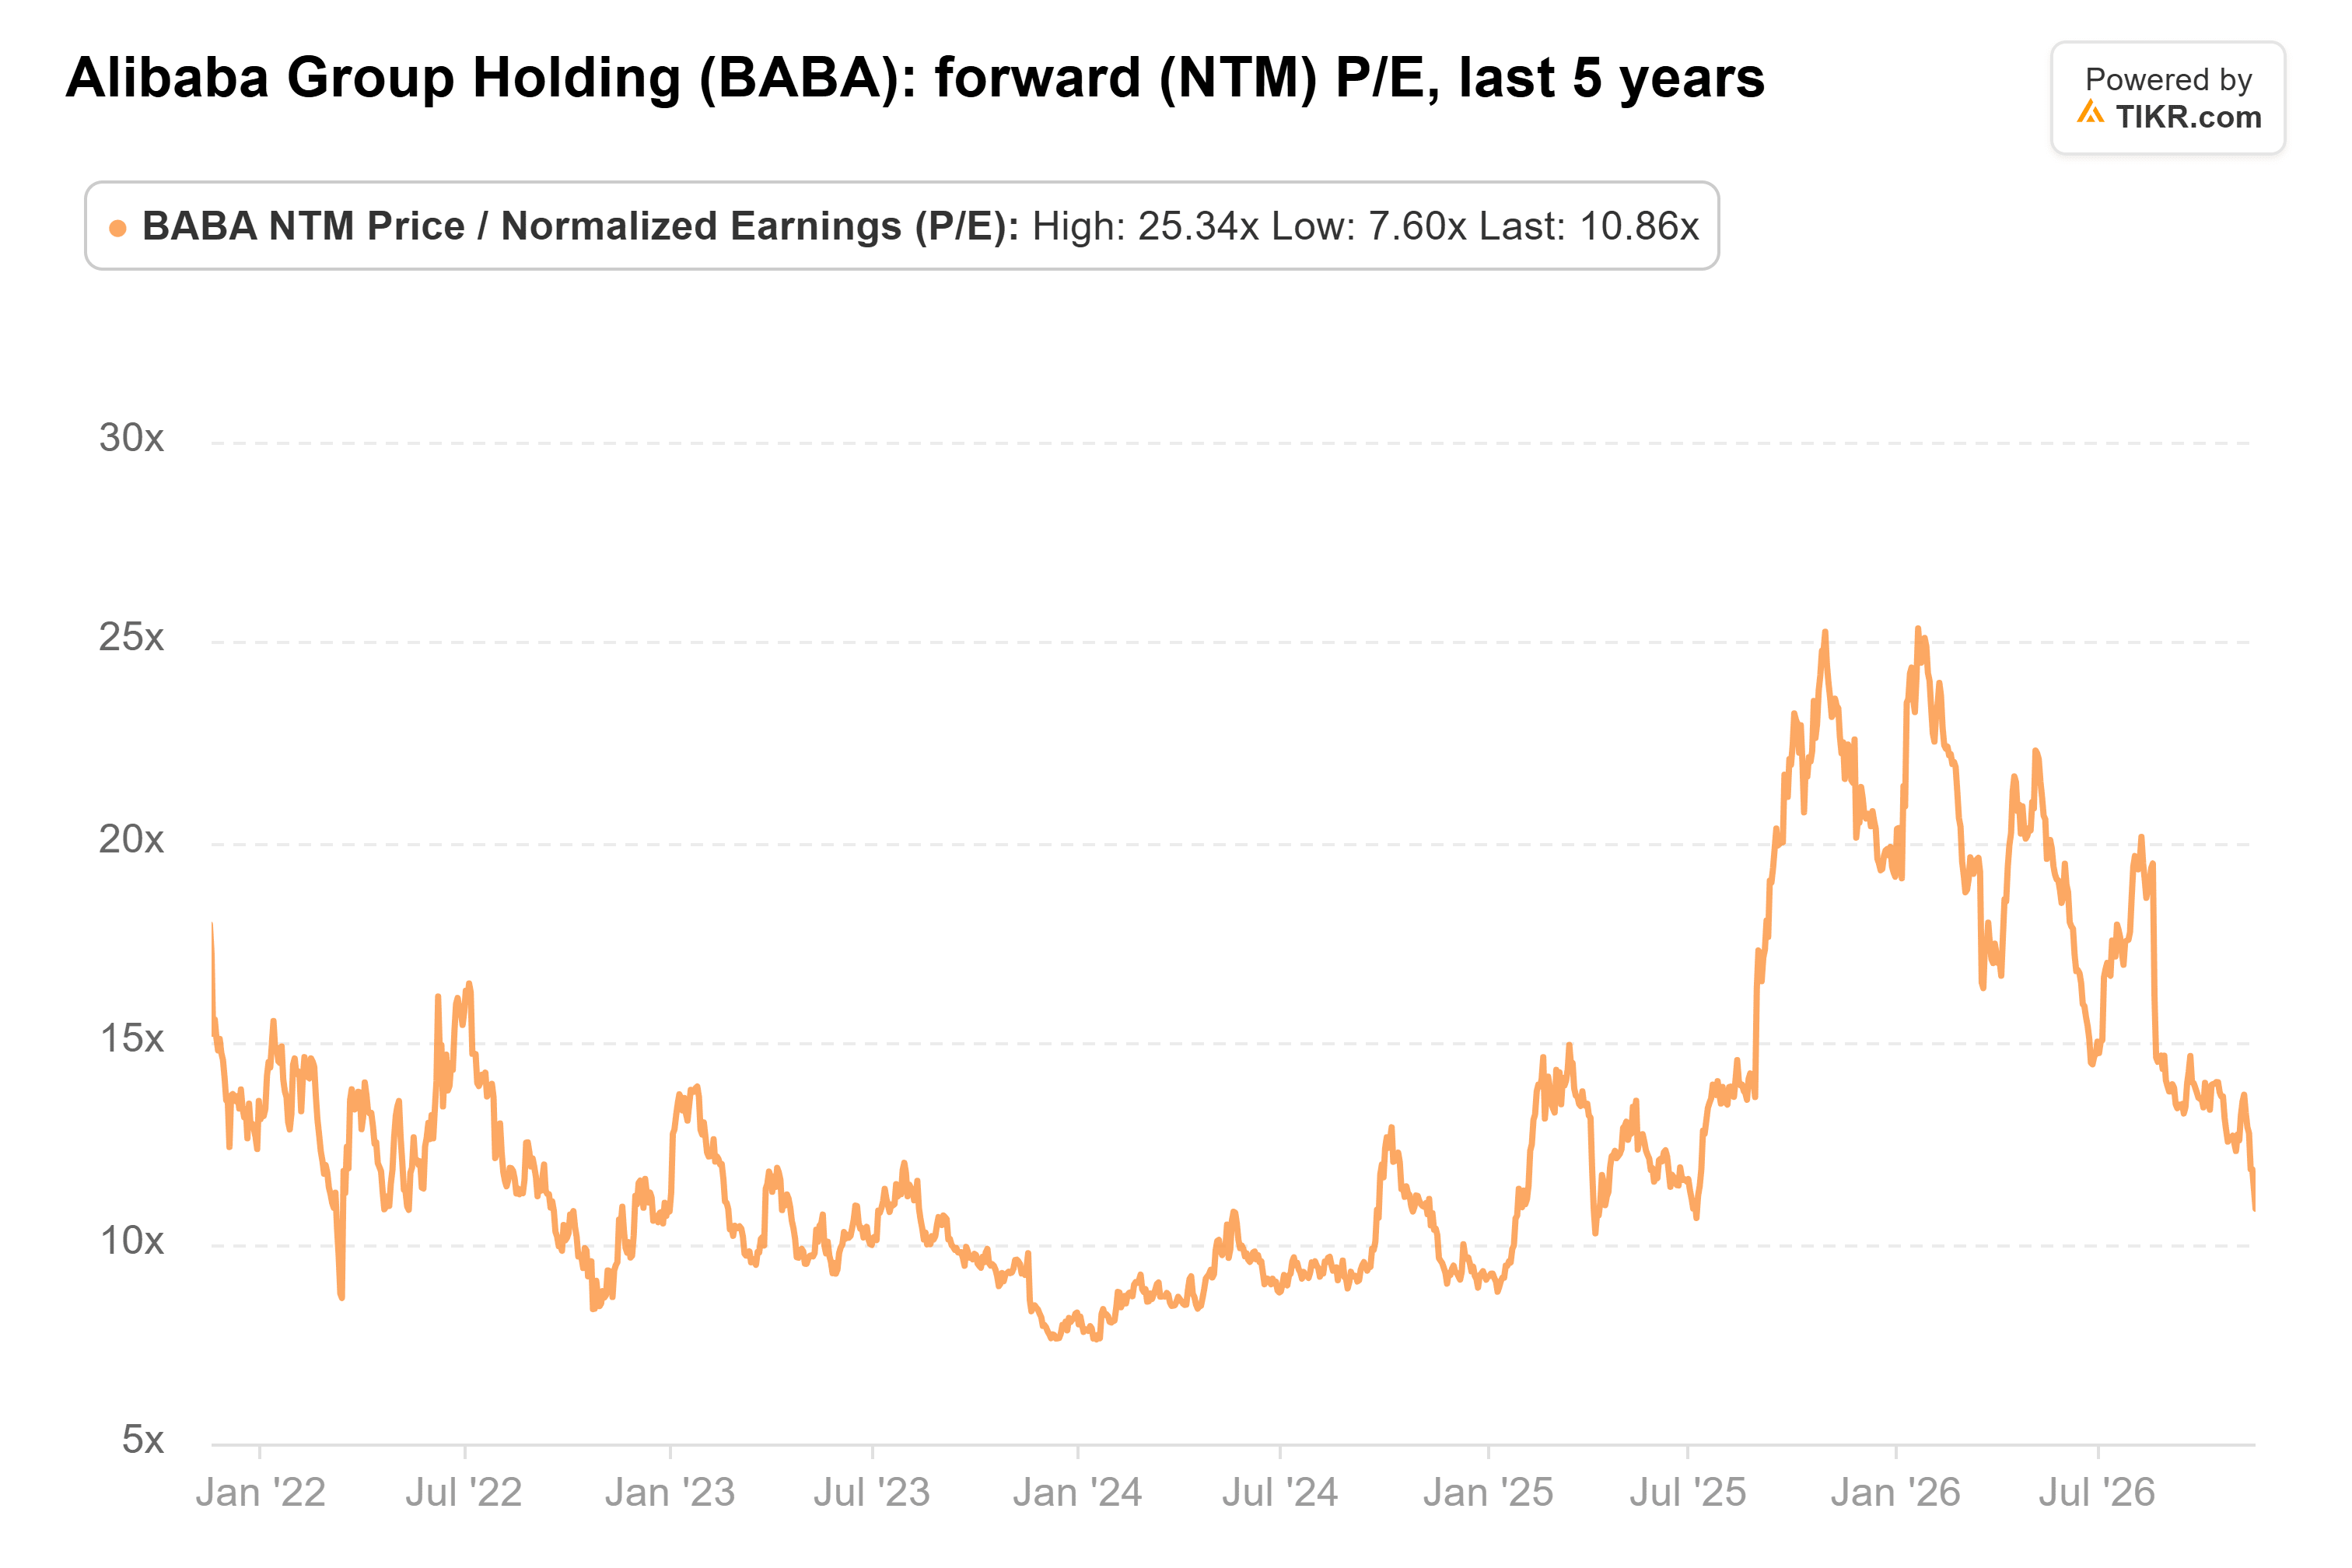
The stock averaged about 19x over the past year and hit 25x in January, so Goldman is asking for the rally’s multiple back. If earnings reach the fiscal 2028 estimate, that alone lifts the stock about 15% at the pre-report multiple. The rest needs the multiple to rise by about three-quarters. At its five-year average multiple on those estimates, the stock would be worth roughly $120.
Cloud cleared its bar, but $177 needs more
The chip rule is the big risk. Data centers already serving Chinese companies have 90 days from Nov. 19 to get a license, which makes mid-February the first real test of Alibaba’s rented capacity. Merchant fees still trail, too: Alibaba’s like-for-like customer management revenue grew 1% again, while PDD’s marketing revenue grew 12%.
Goldman needs both an earnings rebound and the rally’s multiple. The September quarter made the rebound more believable. Paying for the multiple as well looks early while free cash flow stays negative, at an outflow of RMB 34.5 billion last quarter. A second straight quarter of cloud growth above 50% with margins near 14.5% would make “beats-and-raises” much harder to doubt.
So what is Alibaba stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alibaba could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!