Key Takeaways
- CoreWeave fell 9% today after a report that Microsoft passed on an option to more than double its Texas lease with Nscale.
- Neoclouds borrow against new contracts, so a hyperscaler walking away hurts CoreWeave even with its own deals untouched.
- A neocloud that delivers GPU capacity to Microsoft reports tonight.
- CoreWeave’s Nov. 10 report is the next test of whether it can carry its interest bill.
CoreWeave (CRWV) is down 9% today after the Financial Times reported that Microsoft (MSFT) declined an option to more than double its lease at Nscale’s Texas site, a deal potentially worth tens of billions of dollars.
Microsoft can say no
On Wednesday’s 20VC podcast, venture investor Rory O’Driscoll said who gets hurt first: “the first person who’s going to suffer when the demand is not there is not going to be Google or Amazon … It’s going to be the guys like CoreWeave.”
New contracts are what let neoclouds keep borrowing, and Microsoft has now walked away from Nscale twice this year. Analysts still expect CoreWeave’s revenue to climb from $5.13 billion in 2025 to $43.6 billion in 2028:

Today’s news doesn’t touch CoreWeave’s $104.2 billion backlog, so I don’t expect these estimates to move. But the later years need capacity it hasn’t built yet.
TIKR tracks 42 analysts on CoreWeave. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CoreWeave, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CoreWeave’s Analyst Ratings
Borrowing is the pressure point
That build runs on debt. Total debt, leases included, went from $2 billion at the end of 2023 to $29.8 billion at the end of 2025:

It reached $51.6 billion by June 30, 2026. And it’s getting pricier: CoreWeave’s 9.625% notes due 2032 fell below 80 cents on the dollar in mid-October, a yield near 15%.
IREN (IREN), down 14% and delivering four GPU deployments to Microsoft, financed the GPUs for its Microsoft contract at 6.0%, and tonight’s report should show whether the three deployments it hasn’t delivered yet are still due this quarter.
Priced for trouble
At Monday’s close, CoreWeave traded at 1.4x forward sales, its low of the past year, against a 3.6x average:
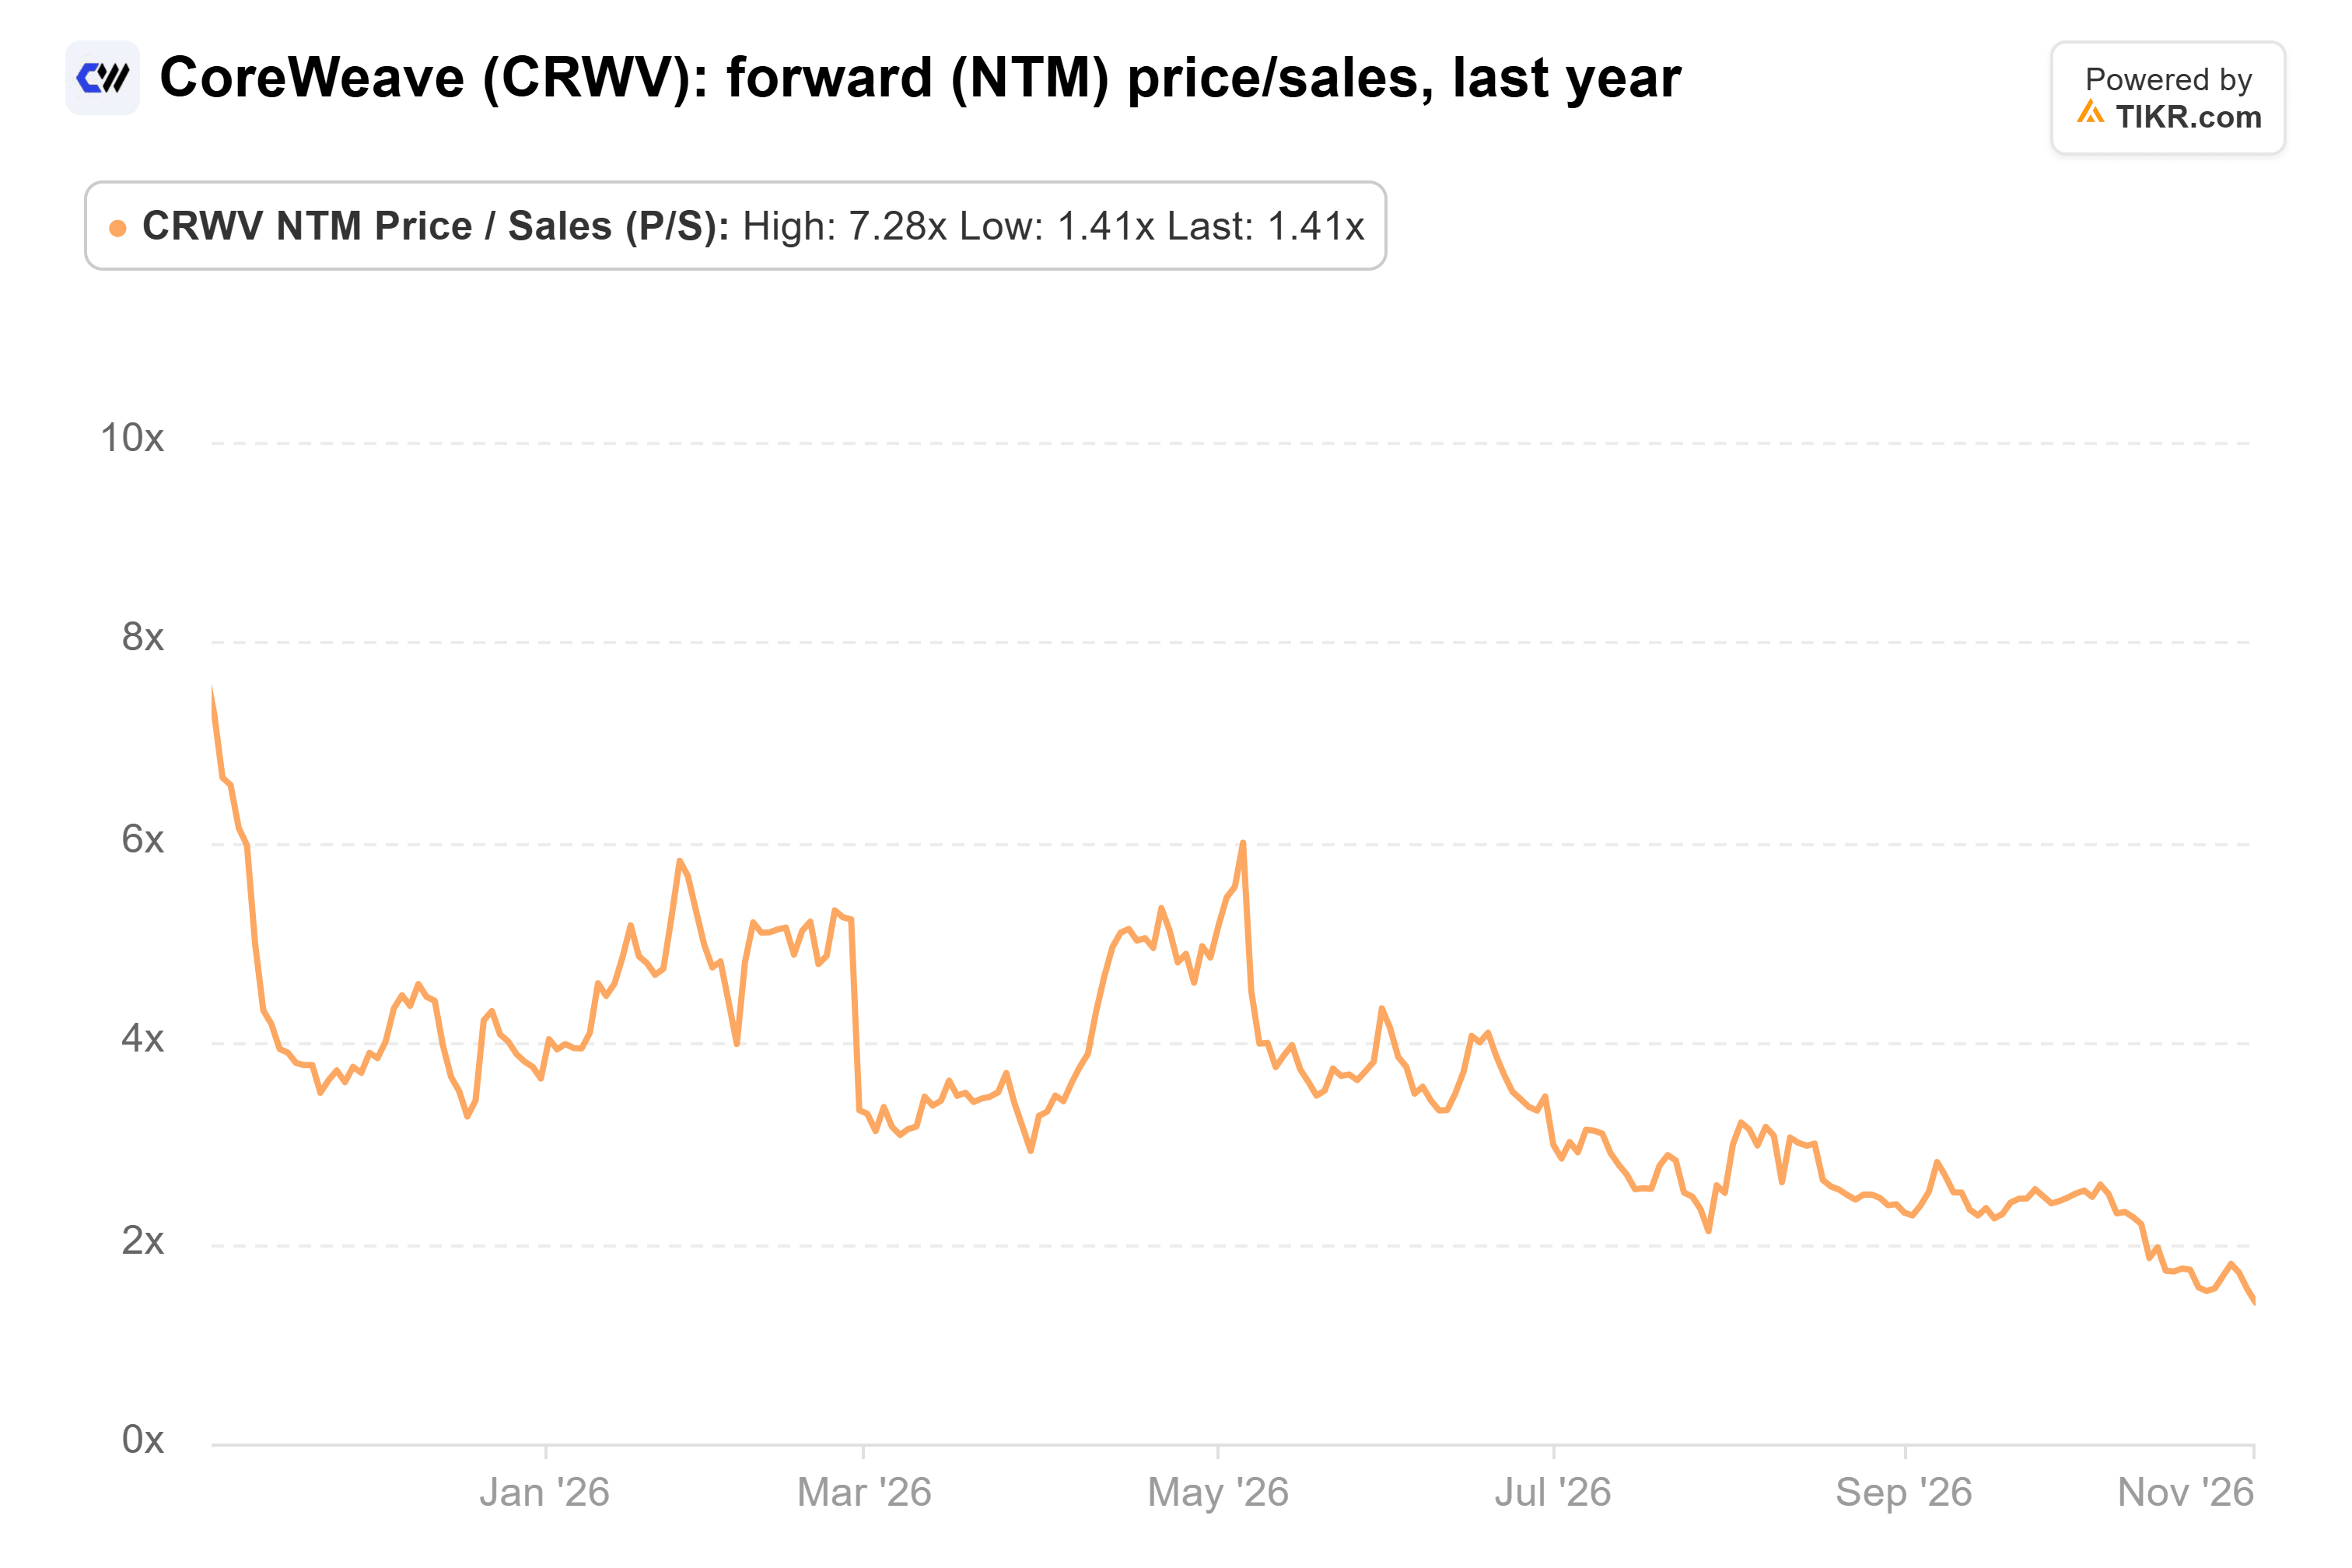
It’s lower still today.
The proof comes Nov. 10
The way I see it, today’s drop is fair. Every dollar CoreWeave borrows gets priced on whether hyperscalers keep signing, and Microsoft just showed it will say no. The stock is cheap, but I’d wait to see it cover its interest first.
CoreWeave reports Nov. 10. It guided third-quarter interest expense of $860 million to $940 million, against adjusted operating income of $200 million to $260 million. Operating income at the top of that range would make me far more comfortable buying the dip.
So what is CoreWeave stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CoreWeave could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!