Key Takeaways
- Coherent jumped 6% today on a new $2 billion buyback, as Anthropic’s IPO lifted AI hardware stocks.
- Management sees the stock as cheap, and Fabrinet’s record quarter shows optics demand still growing.
- The catch is cash: Coherent’s free cash flow was negative $1.02 billion last fiscal year, and Applied Optoelectronics is selling up to $550 million of stock.
- With EPS expected to rise about 86% this fiscal year, a forward P/E below its five-year average looks cheap.
Coherent (COHR) jumped 6% today after its board authorized a $2 billion share buyback. Anthropic’s IPO lifted AI hardware stocks the same morning.
Not every optics company can afford that. Applied Optoelectronics (AAOI) disclosed on Nov. 17 a program to sell up to $550 million of new stock, its fourth this year. Fabrinet (FN) expanded its buyback after a record quarter.
A $2 billion vote of confidence
The program has no expiration date. At yesterday’s close, $2 billion was nearly 5% of Coherent’s market value.
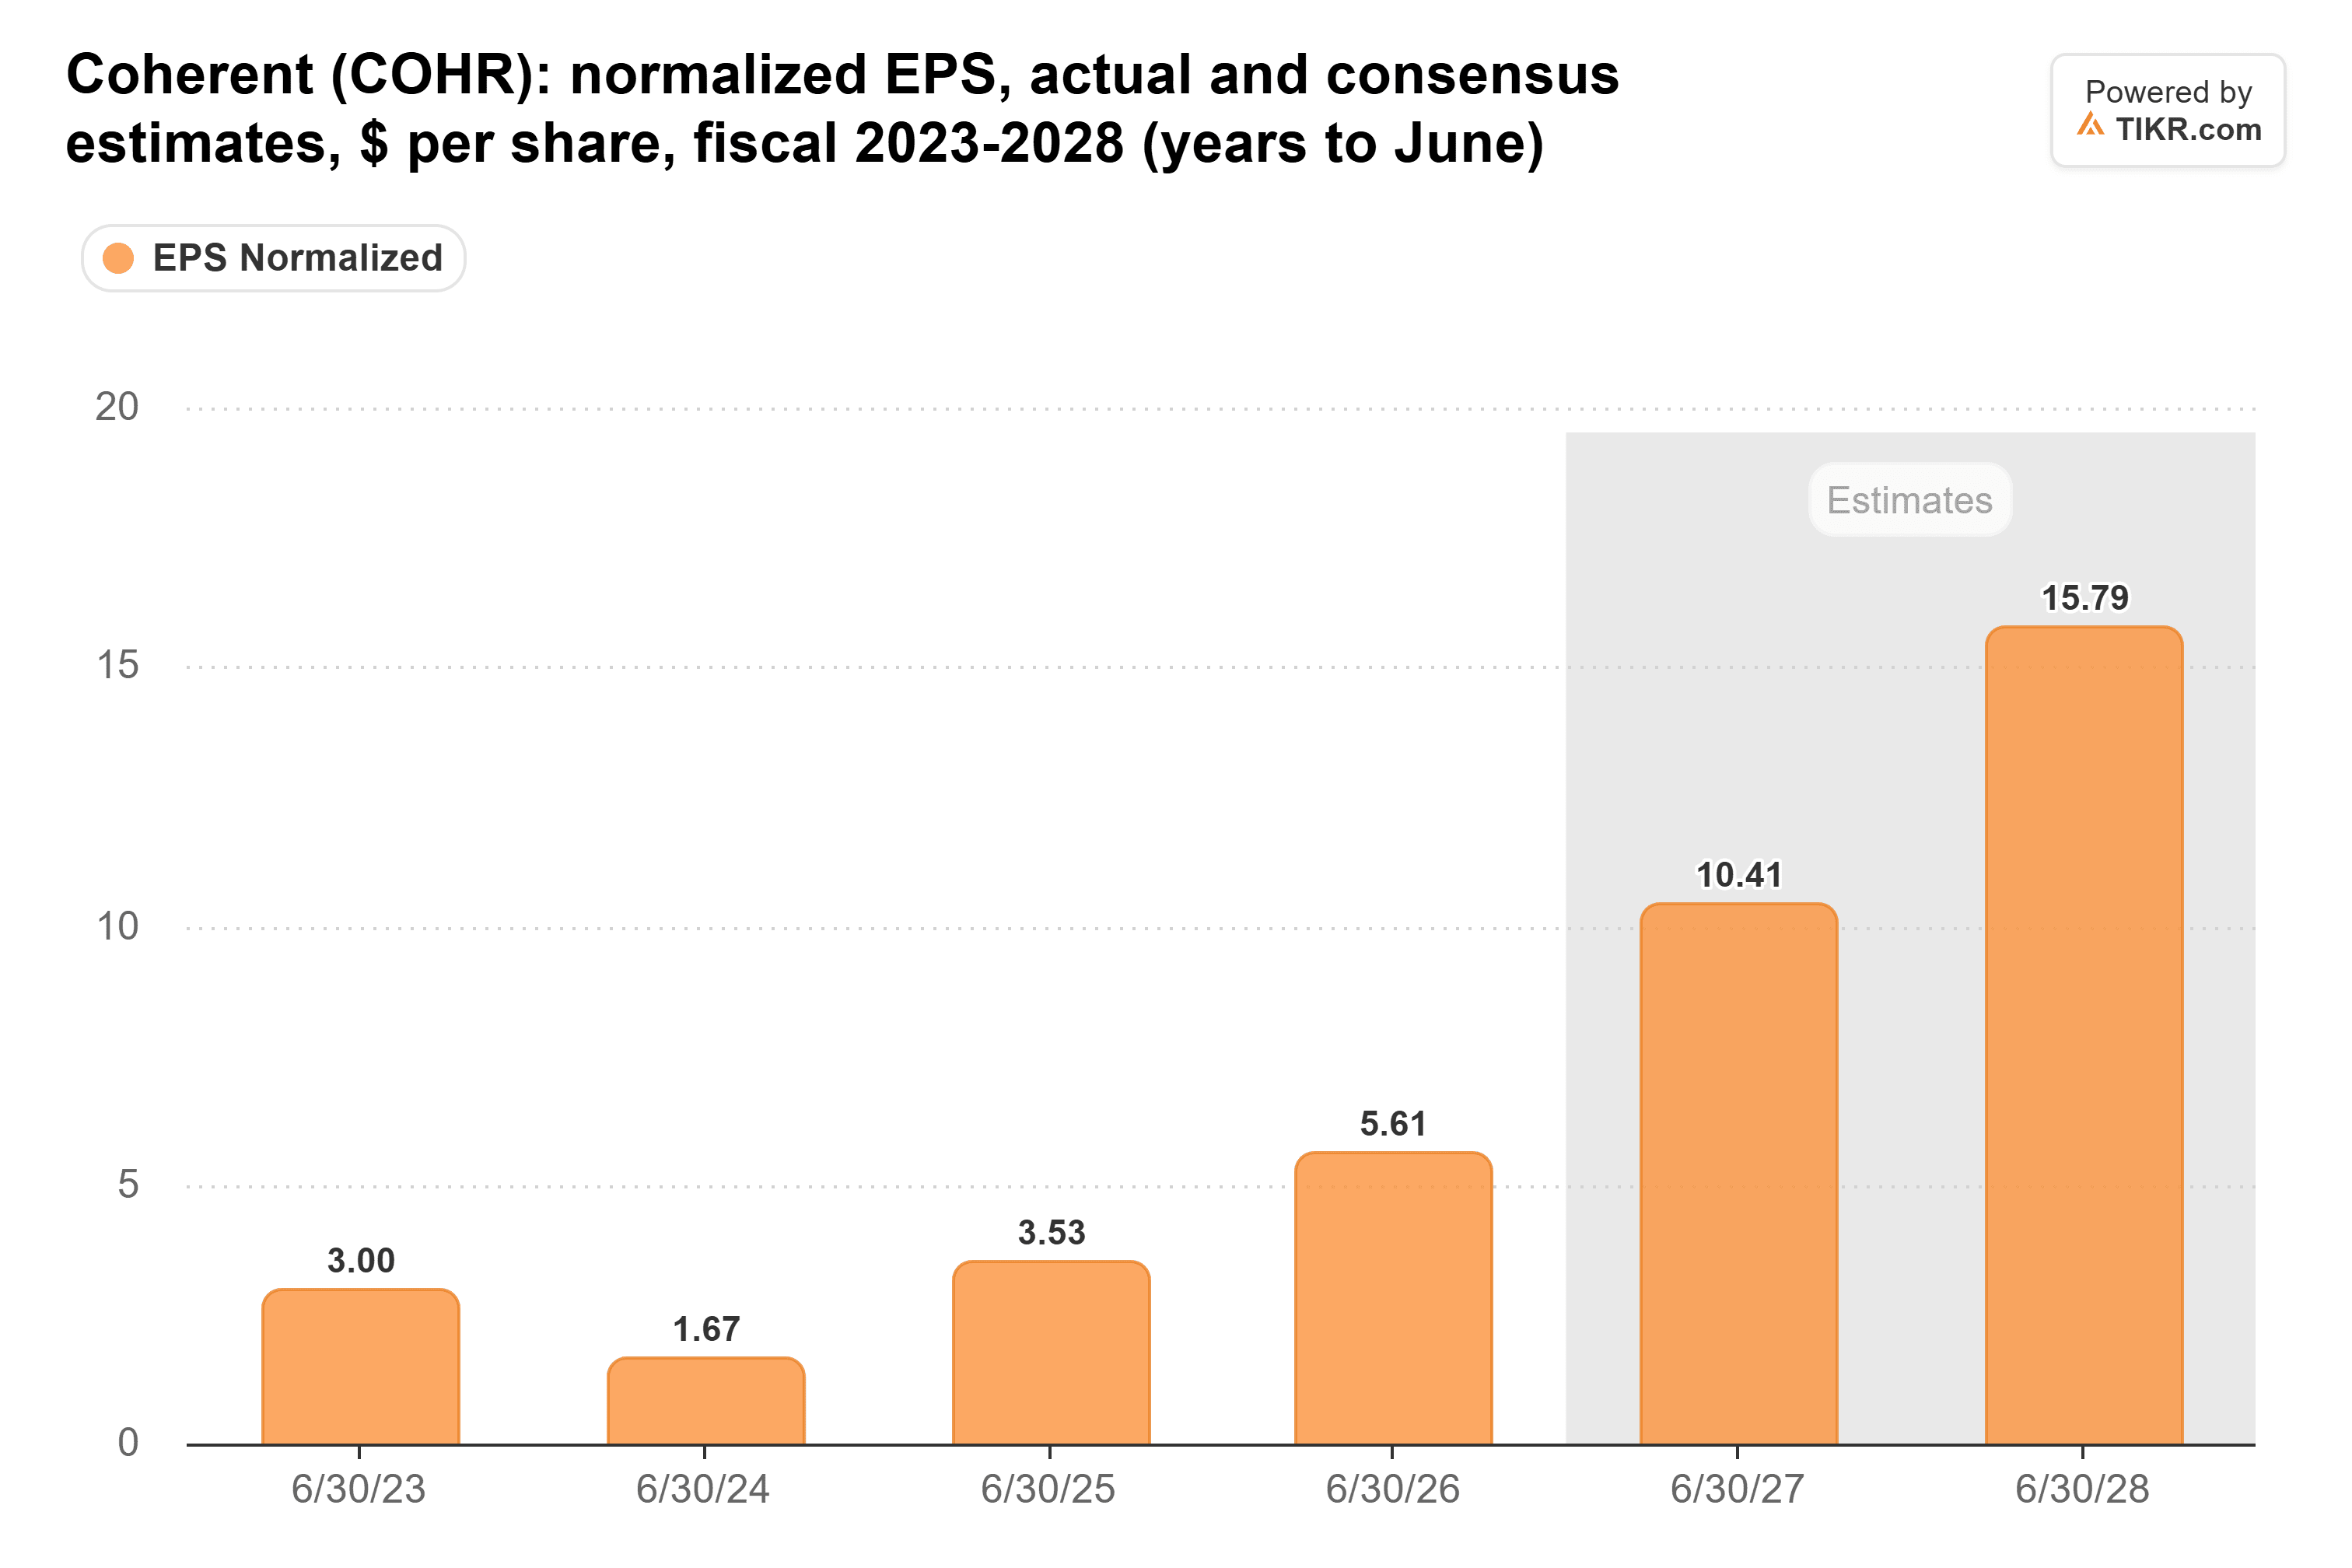
September-quarter revenue rose 50% to $2.37 billion. Analysts expect normalized EPS to climb from $5.61 in fiscal 2026 to $10.41 this fiscal year, which ends in June:
Yet the stock trades below its usual multiple:
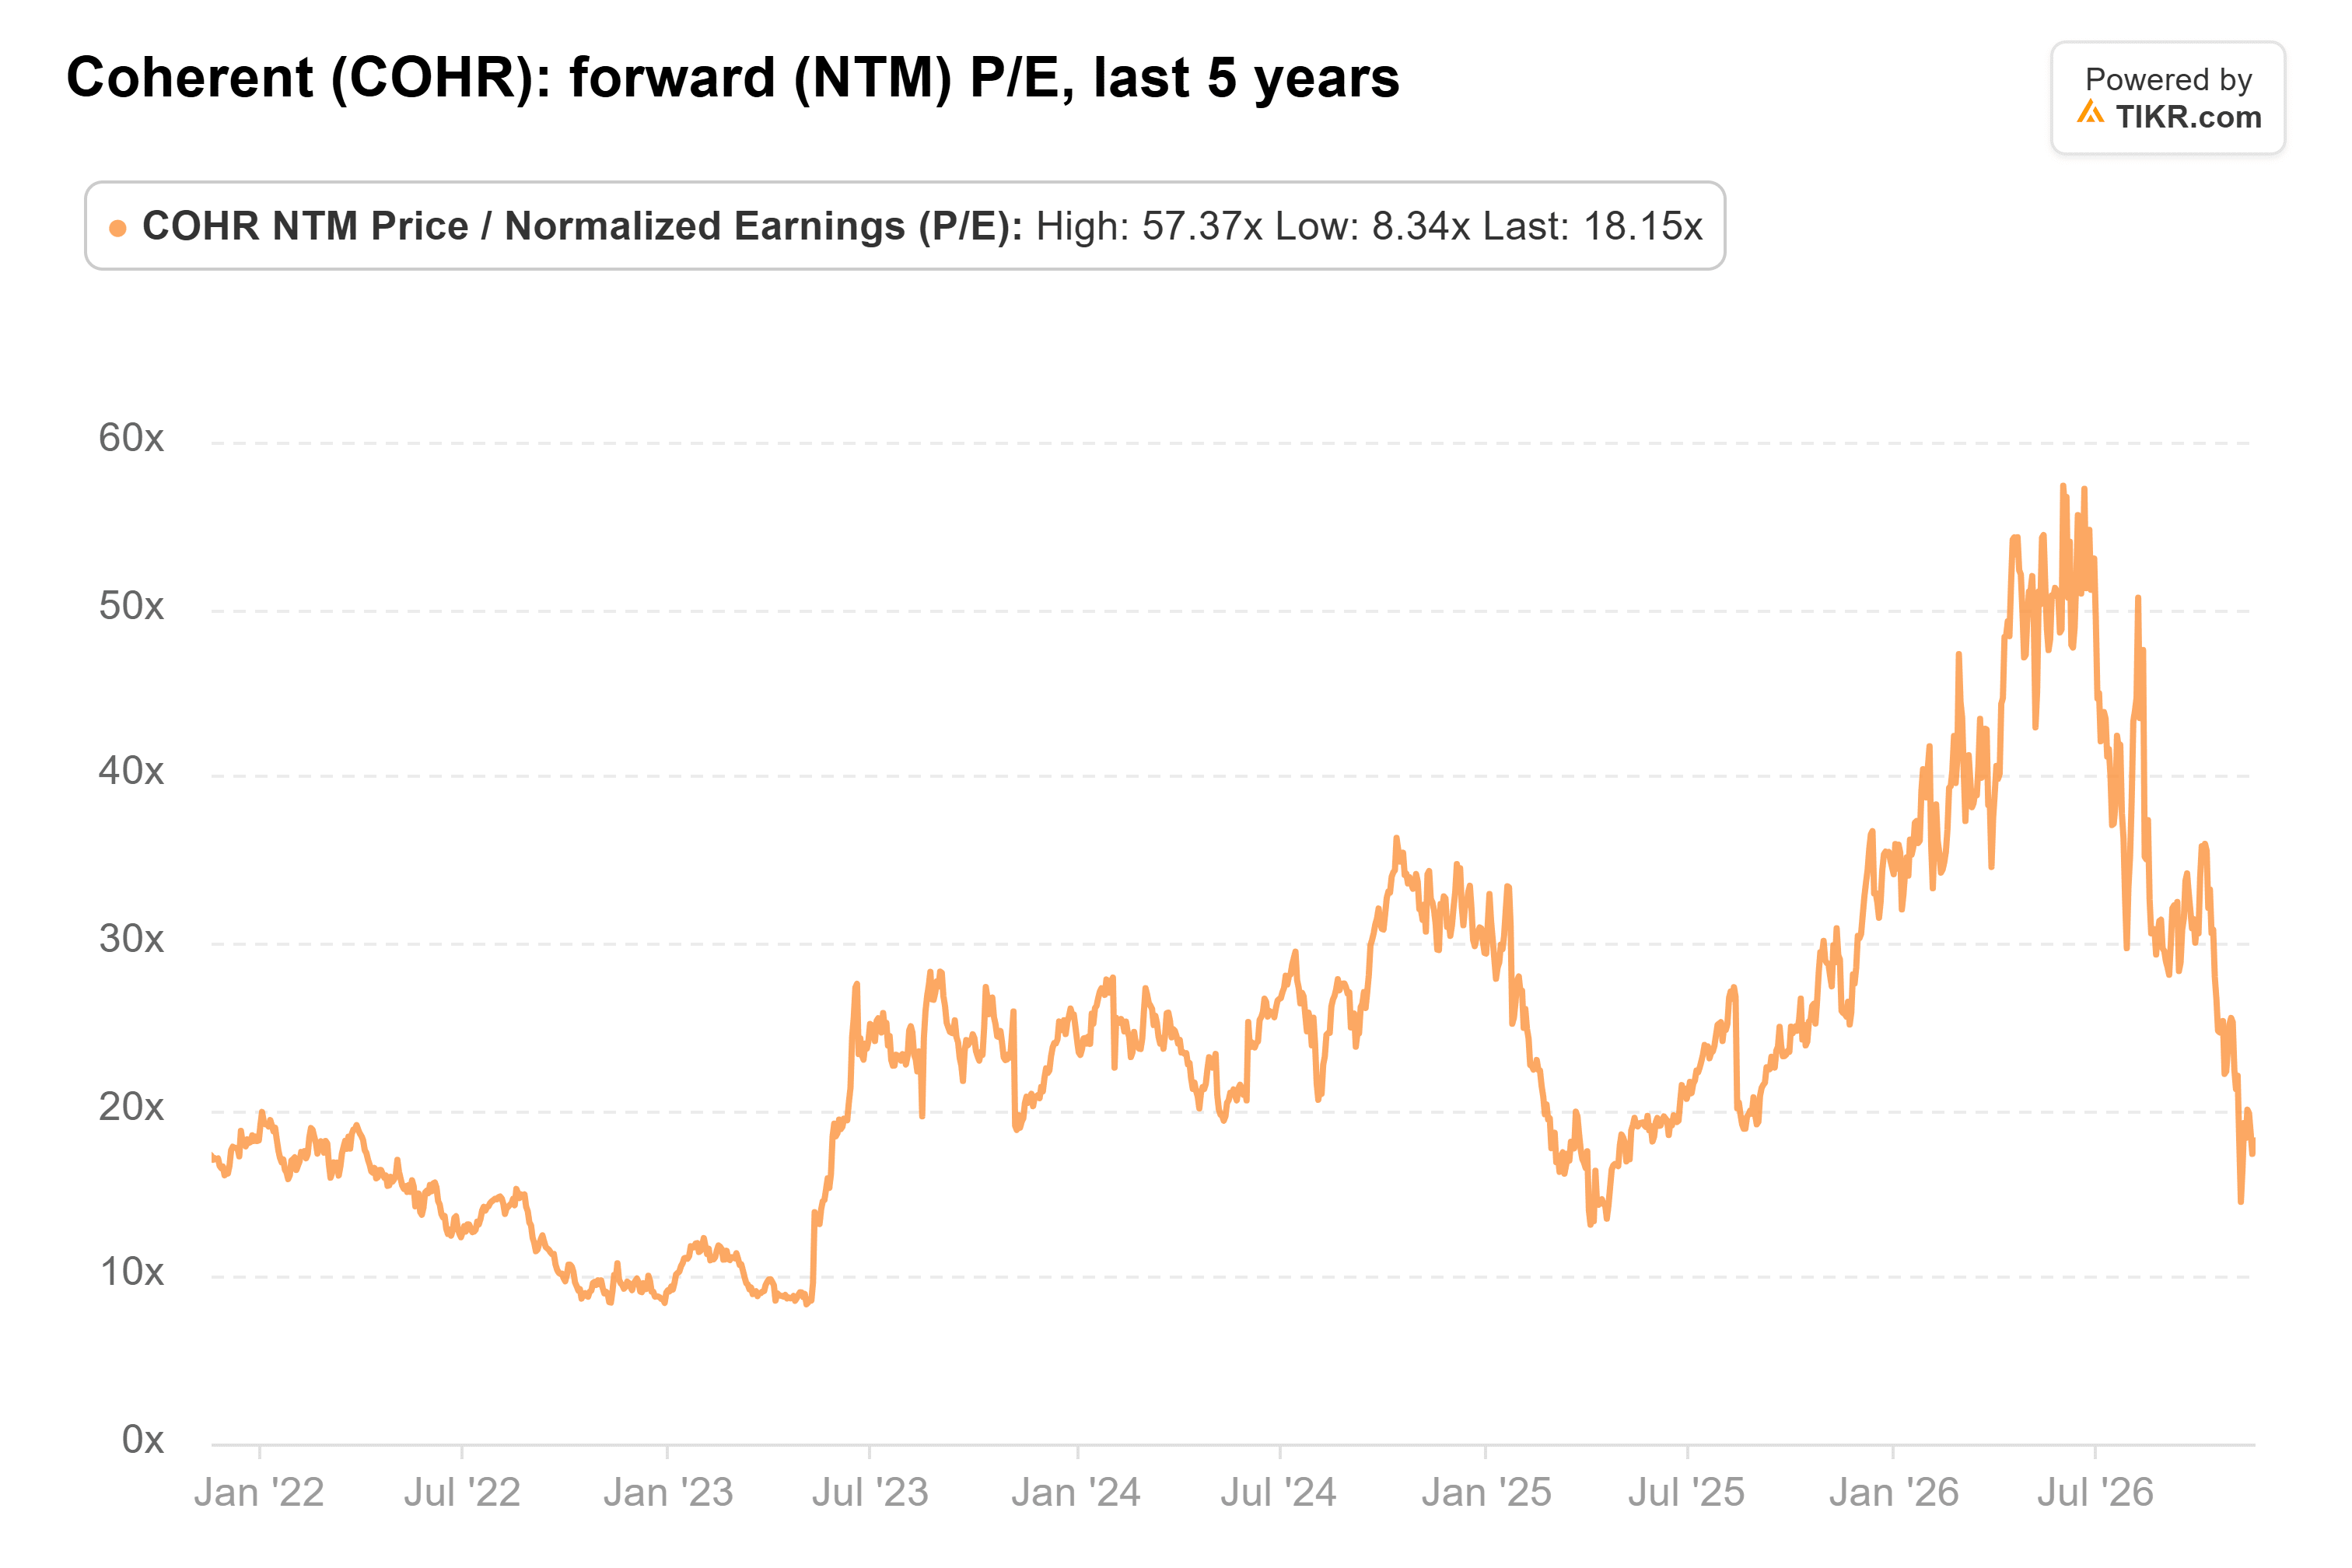
At yesterday’s close, that was 18x forward earnings, against a five-year average of 24x. Even after today’s jump, it’s about 20x.
TIKR tracks 26 analysts on Coherent. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Coherent, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Coherent’s Analyst Ratings
The catch is cash
Free cash flow was negative $1.02 billion in fiscal 2026, as Coherent built laser capacity and inventory. It ended September with $1.55 billion of cash and equivalents. I’d expect Coherent to buy back stock only as fast as its cash flow allows.
Applied Optoelectronics has less room. Its third-quarter revenue more than doubled to $269.9 million, but CFO Stefan Murry said on the Nov. 5 call that “Our revenue growth is gated by our ability to add capacity.” So it’s selling stock to build.
Fabrinet’s results point to demand holding up. Its revenue jumped 51% to $1.47 billion in the quarter ended Sept. 25, and it guides to as much as $1.65 billion this quarter. Its board also added $103.0 million to its buyback. At 15x forward earnings, Fabrinet is priced for a slowdown its guidance doesn’t show either.
Cheap, if the cash comes
For a company expected to nearly double EPS this year, 20x looks cheap, and management clearly agrees. The main risk is concentration: one customer bought 20% of fiscal 2026 revenue. The next test is the December-quarter report in early February. Operating cash flow above capex would show Coherent can pay for both the ramp and the buyback.
So what is Coherent stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Coherent could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!