Key Takeaways
- Blackstone’s new data center REIT is buying 75% of 13 Amazon Web Services buildings in a deal valued at about $5 billion, at a 7% cap rate.
- AWS is Cipher Digital’s tenant at two Texas campuses, with about $7.5 billion of rent under contract, so Blackstone’s price gives investors a yardstick.
- At a 7% yield, Cipher’s projected property income would be worth about $12.3 billion, roughly twice its debt.
- Cipher trades at 4.7x forward sales, well under its three-year average, though its debt and Texas politics are real risks.
Blackstone (BX) just put a price on rent from Amazon (AMZN) data centers, and I think it matters most for Cipher Digital (CIFR), which collects that rent in Texas.
Blackstone Digital Infrastructure Trust, Blackstone’s newly listed data center REIT, announced its first deal on Monday: a 75% stake in two joint ventures with Amazon Web Services, valued at about $5 billion. It’s also a public price on the kind of tenant Cipher already has.
What Blackstone Is Buying
- 13 newly built powered shells on two AWS campuses, two-thirds in the greater Chicago region and the rest in Mississippi.
- Amazon affiliates keep about 25%, and Amazon Data Services leases both campuses on triple-net terms averaging 12 years, or 32 fully extended, with Amazon.com guaranteeing the rent.
- A 7.0% cap rate, with the joint venture borrowing half the price. The deal is expected to close in the fourth quarter.
Short seller Jim Chanos said on X that a 7% yield would value Digital Realty and Equinix “materially lower than where they trade today.” Run the same math on Cipher, and the answer flips.
TIKR Tracks 22 Analysts on Cipher Digital. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Cipher Digital, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Cipher Digital’s Analyst Ratings
Cipher’s Rent Looks Cheap at Blackstone’s Yield
Cipher had $16.6 billion of rent under contract across 700 megawatts at Sept. 30. About $7.5 billion of it is from AWS: a 15-year, $5.5 billion lease at Black Pearl, where rent started in August, and the Stingray campus.
Cipher projects average annual net operating income of $864 million across its three campuses from August 2026 through July 2041. That income comes from turnkey halls with power and cooling, not empty shells, and it includes Barber Lake, where the tenant is Fluidstack.
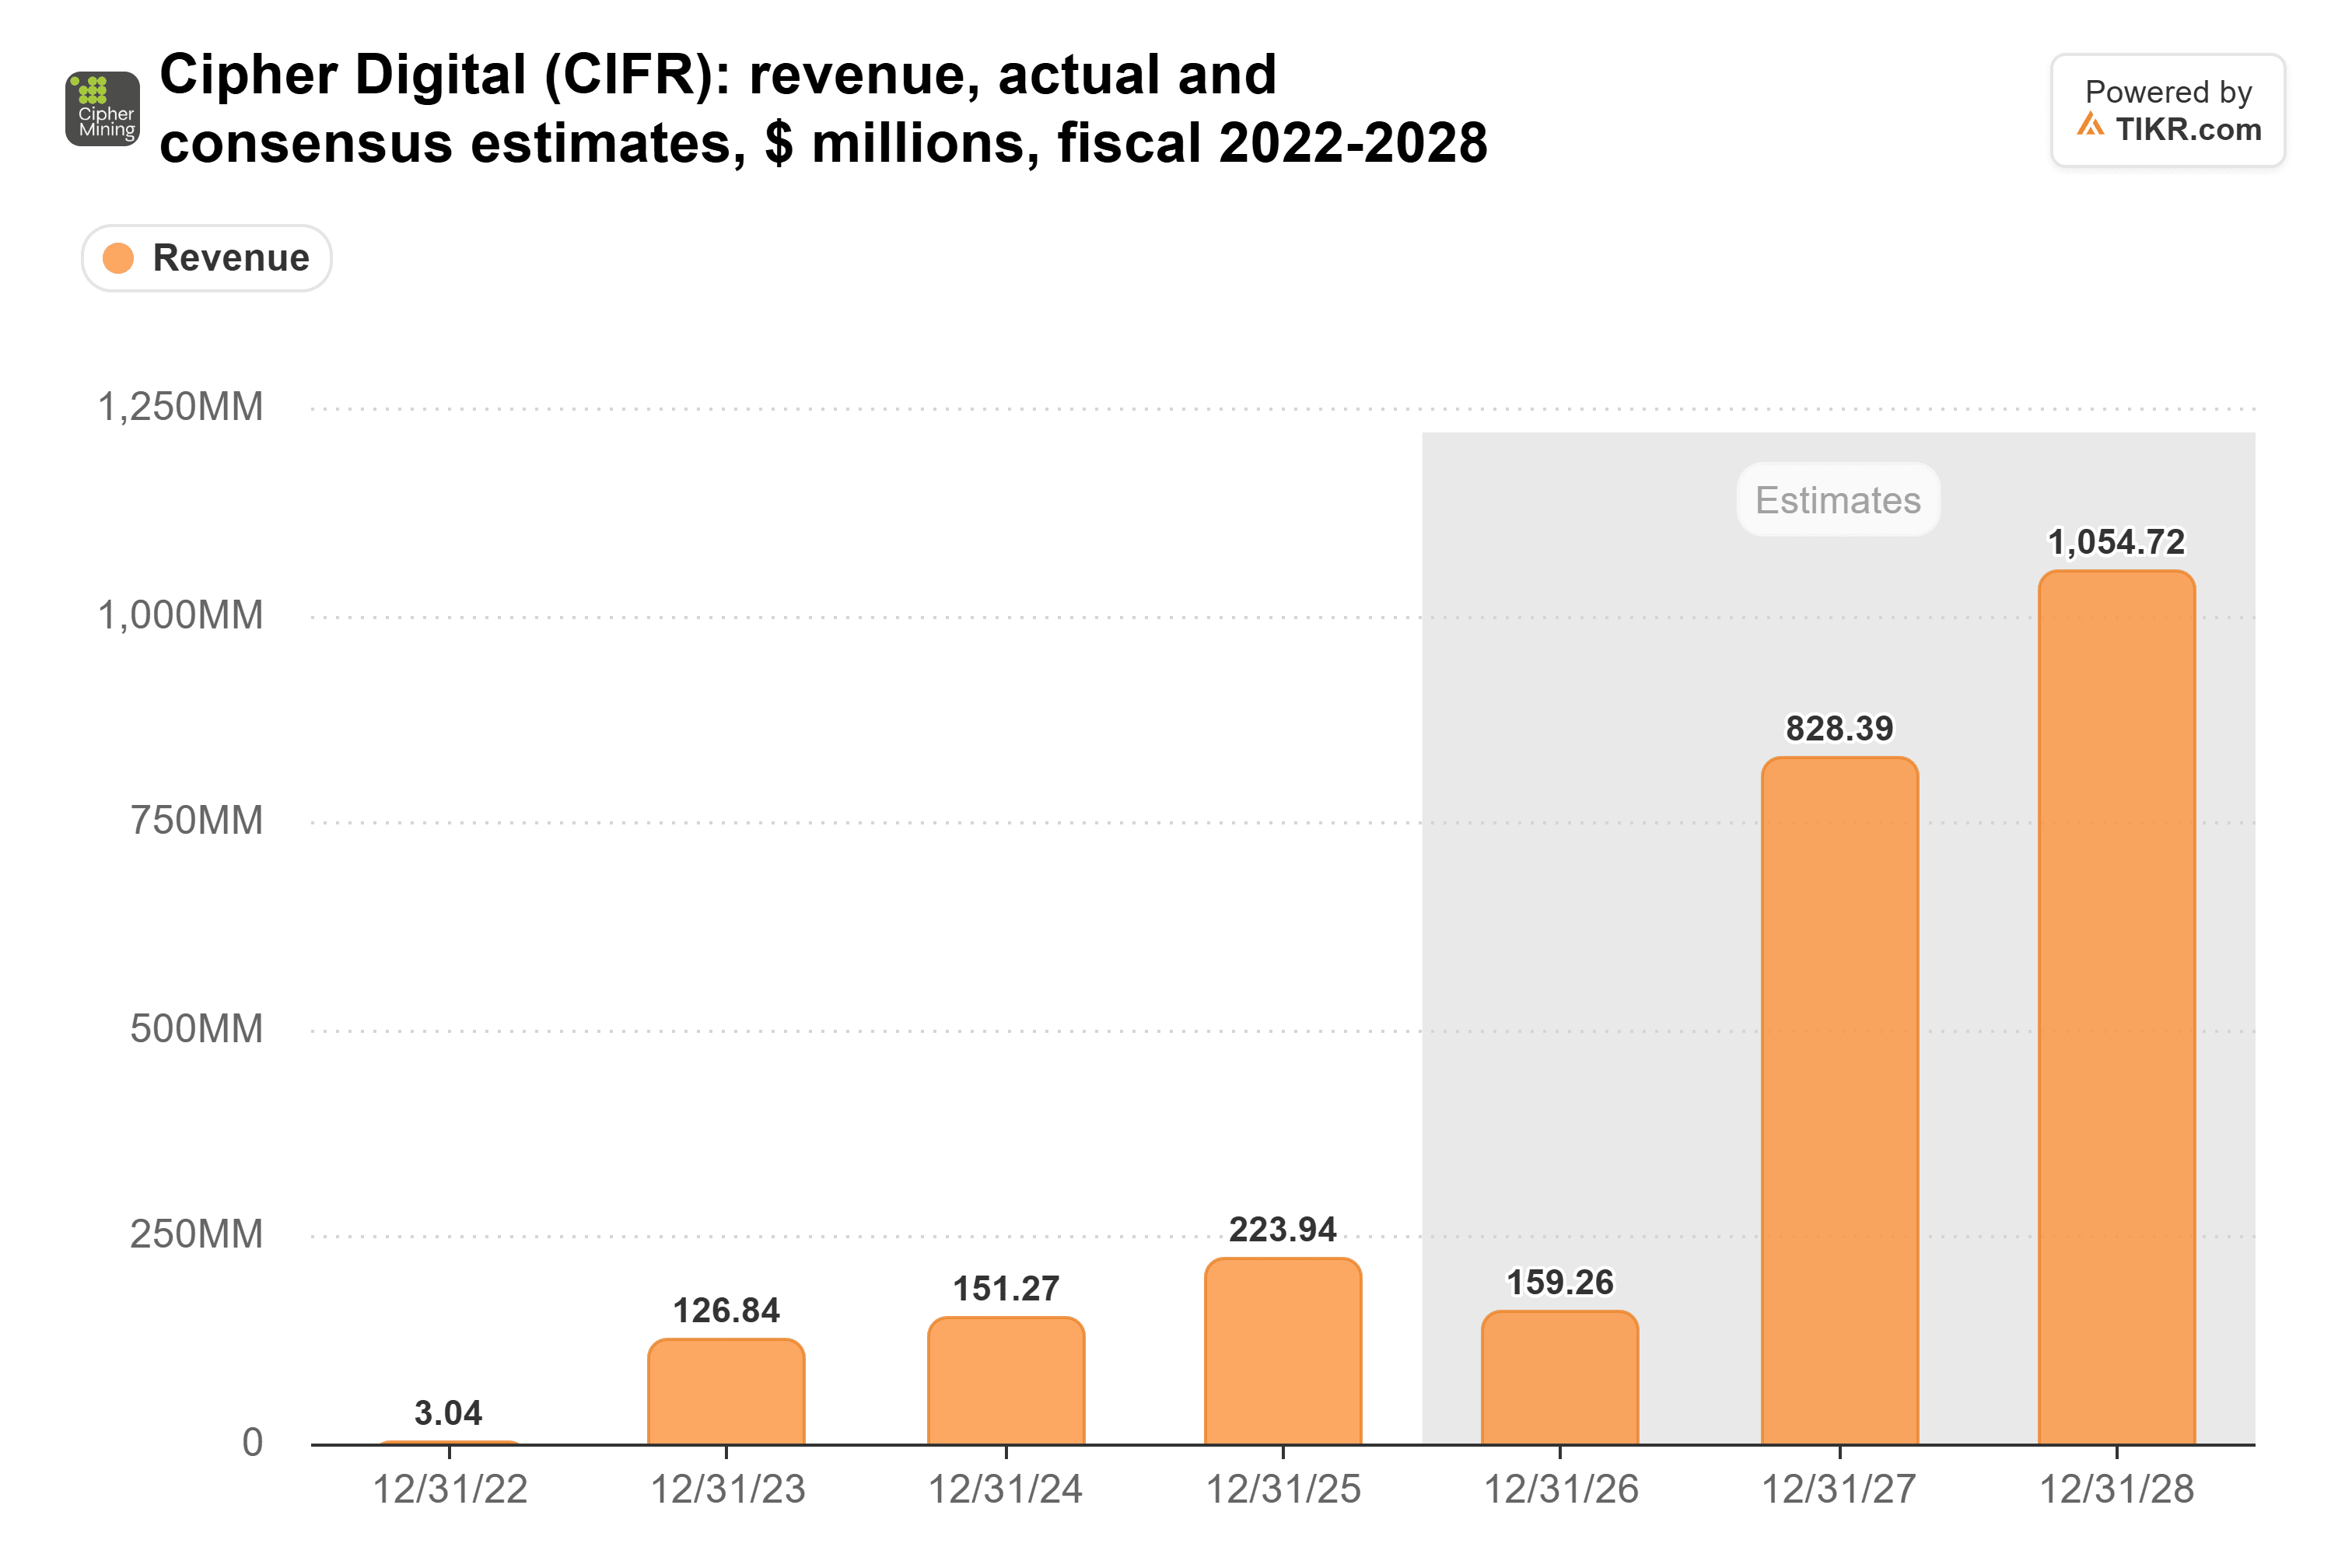
Analysts expect that rent to lift revenue from $159 million this year to $828 million in 2027 as bitcoin mining winds down:
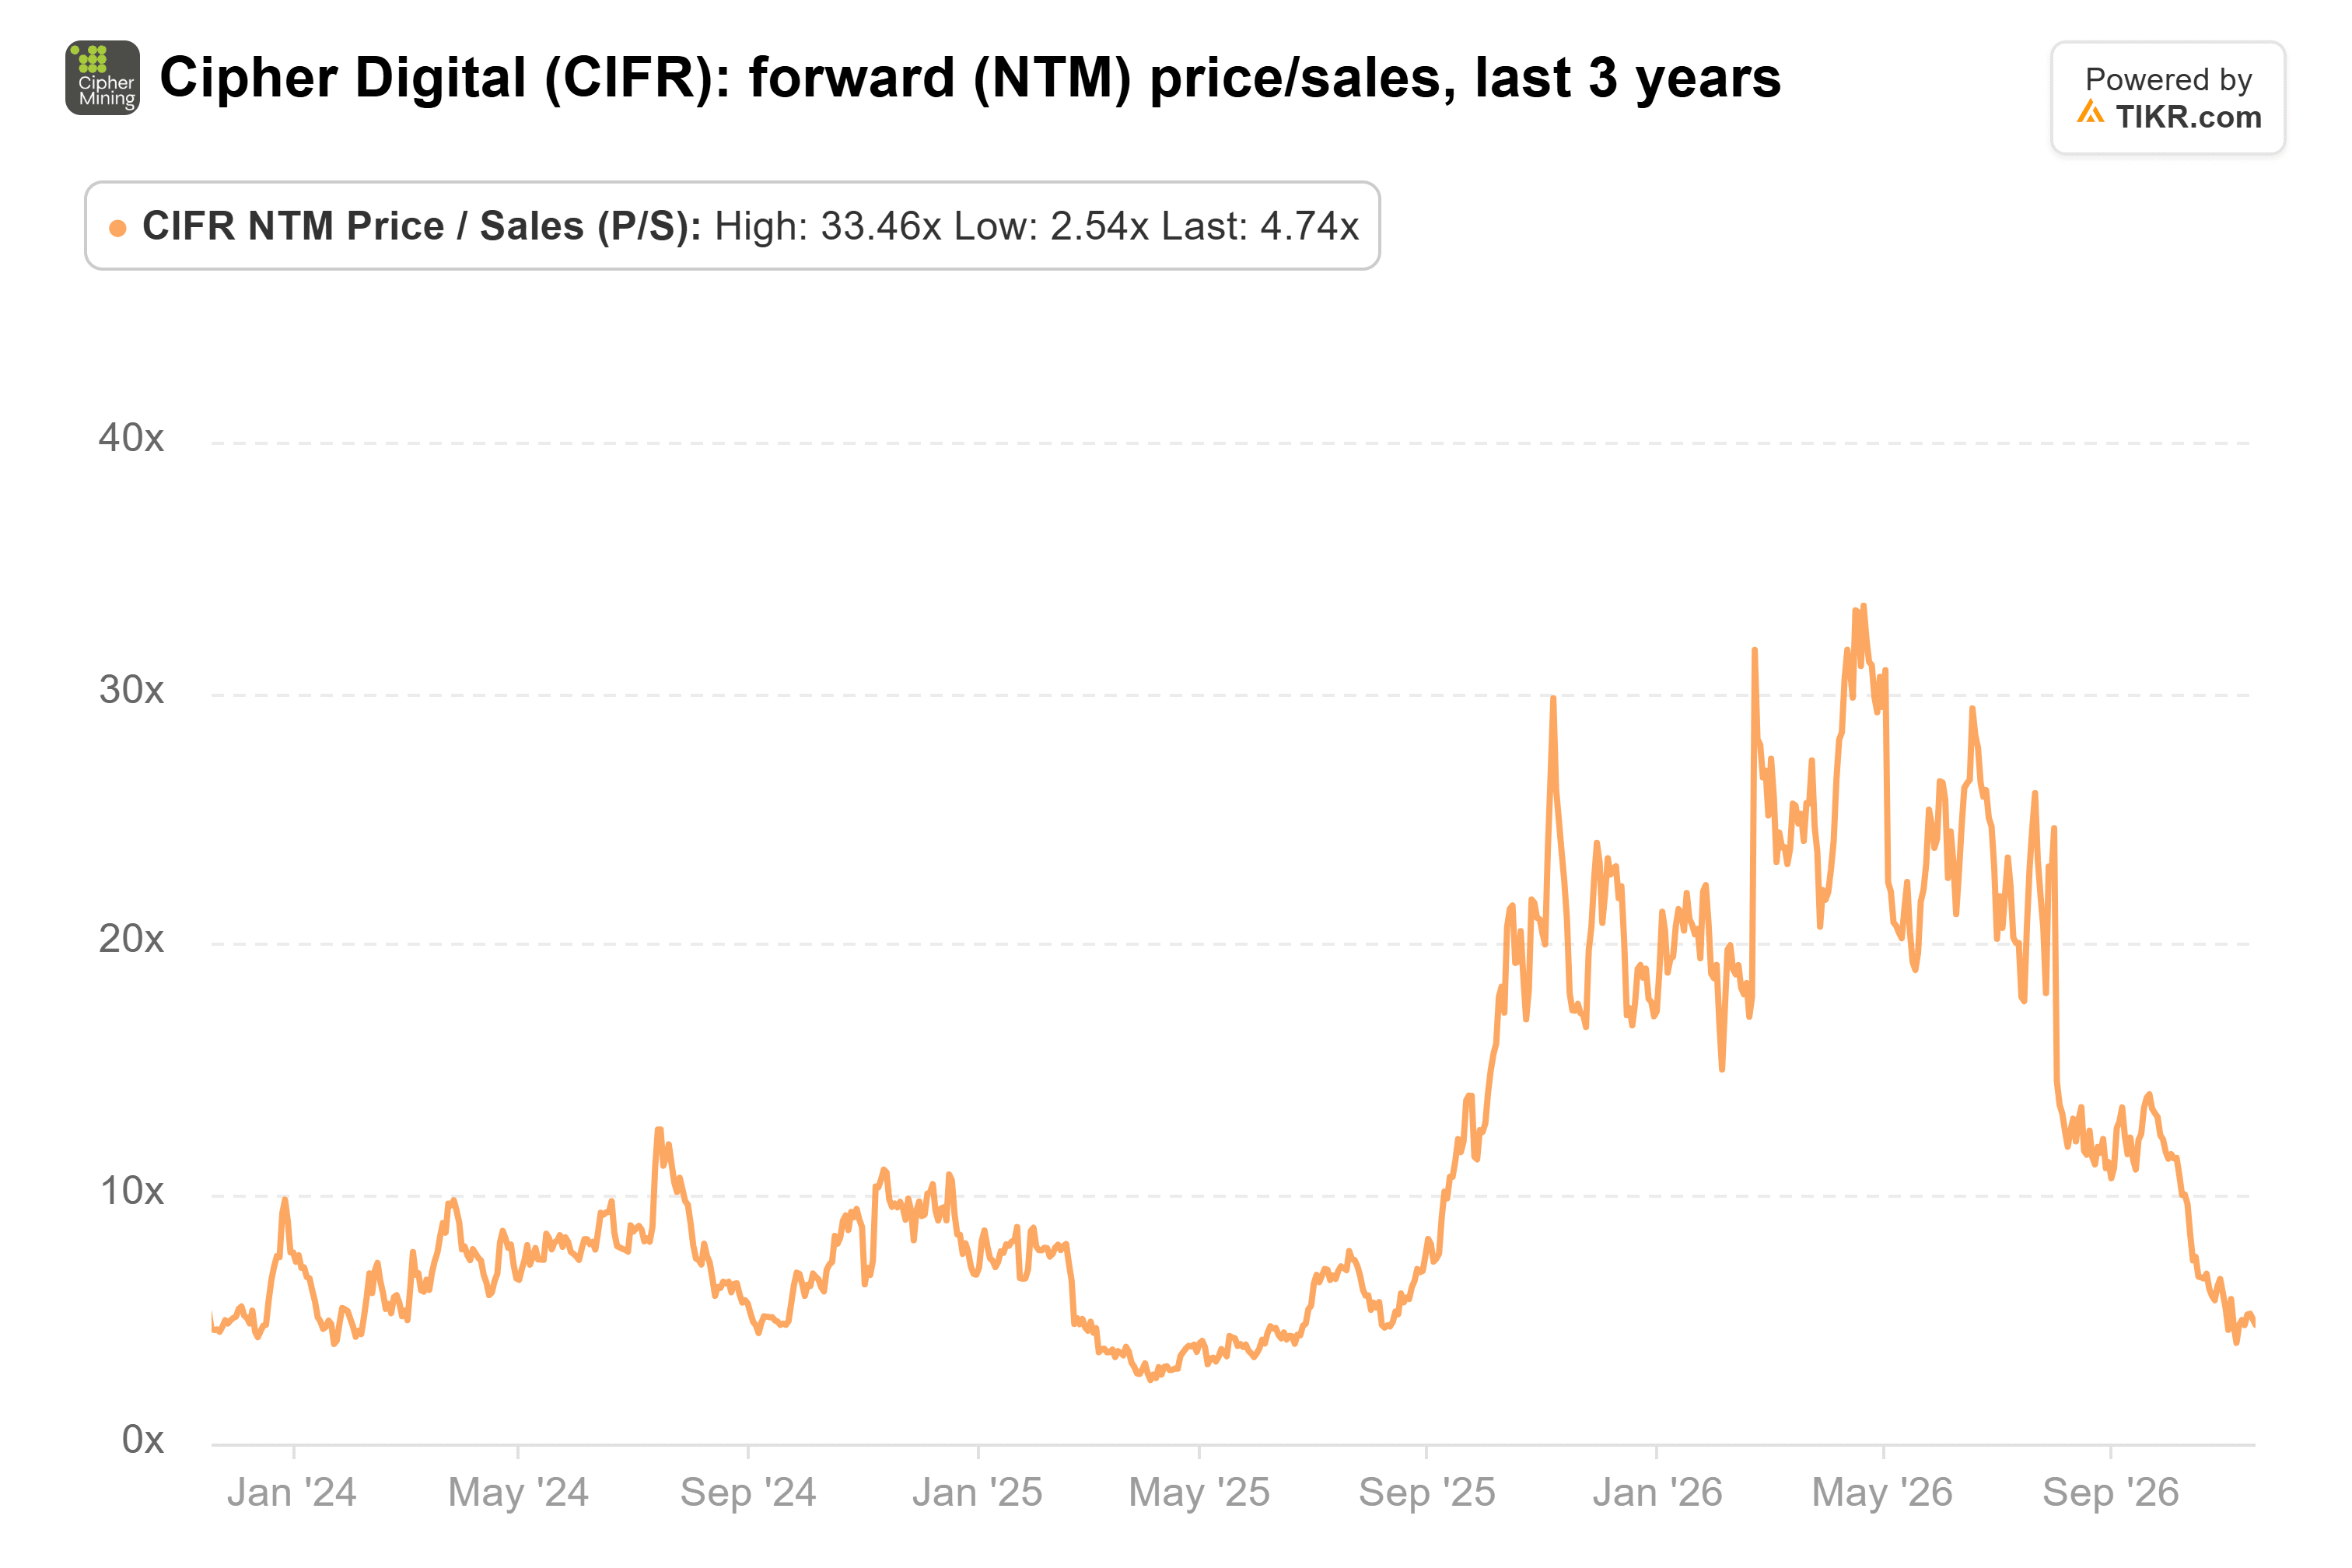
Yet the stock trades at 4.7x forward sales, well under its 11.4x three-year average and the 33.5x it hit in April:
The Debt Is the Catch
Cipher’s total debt reached $5.62 billion at Sept. 30, before the $850 million of 0% convertible notes it sold in October:
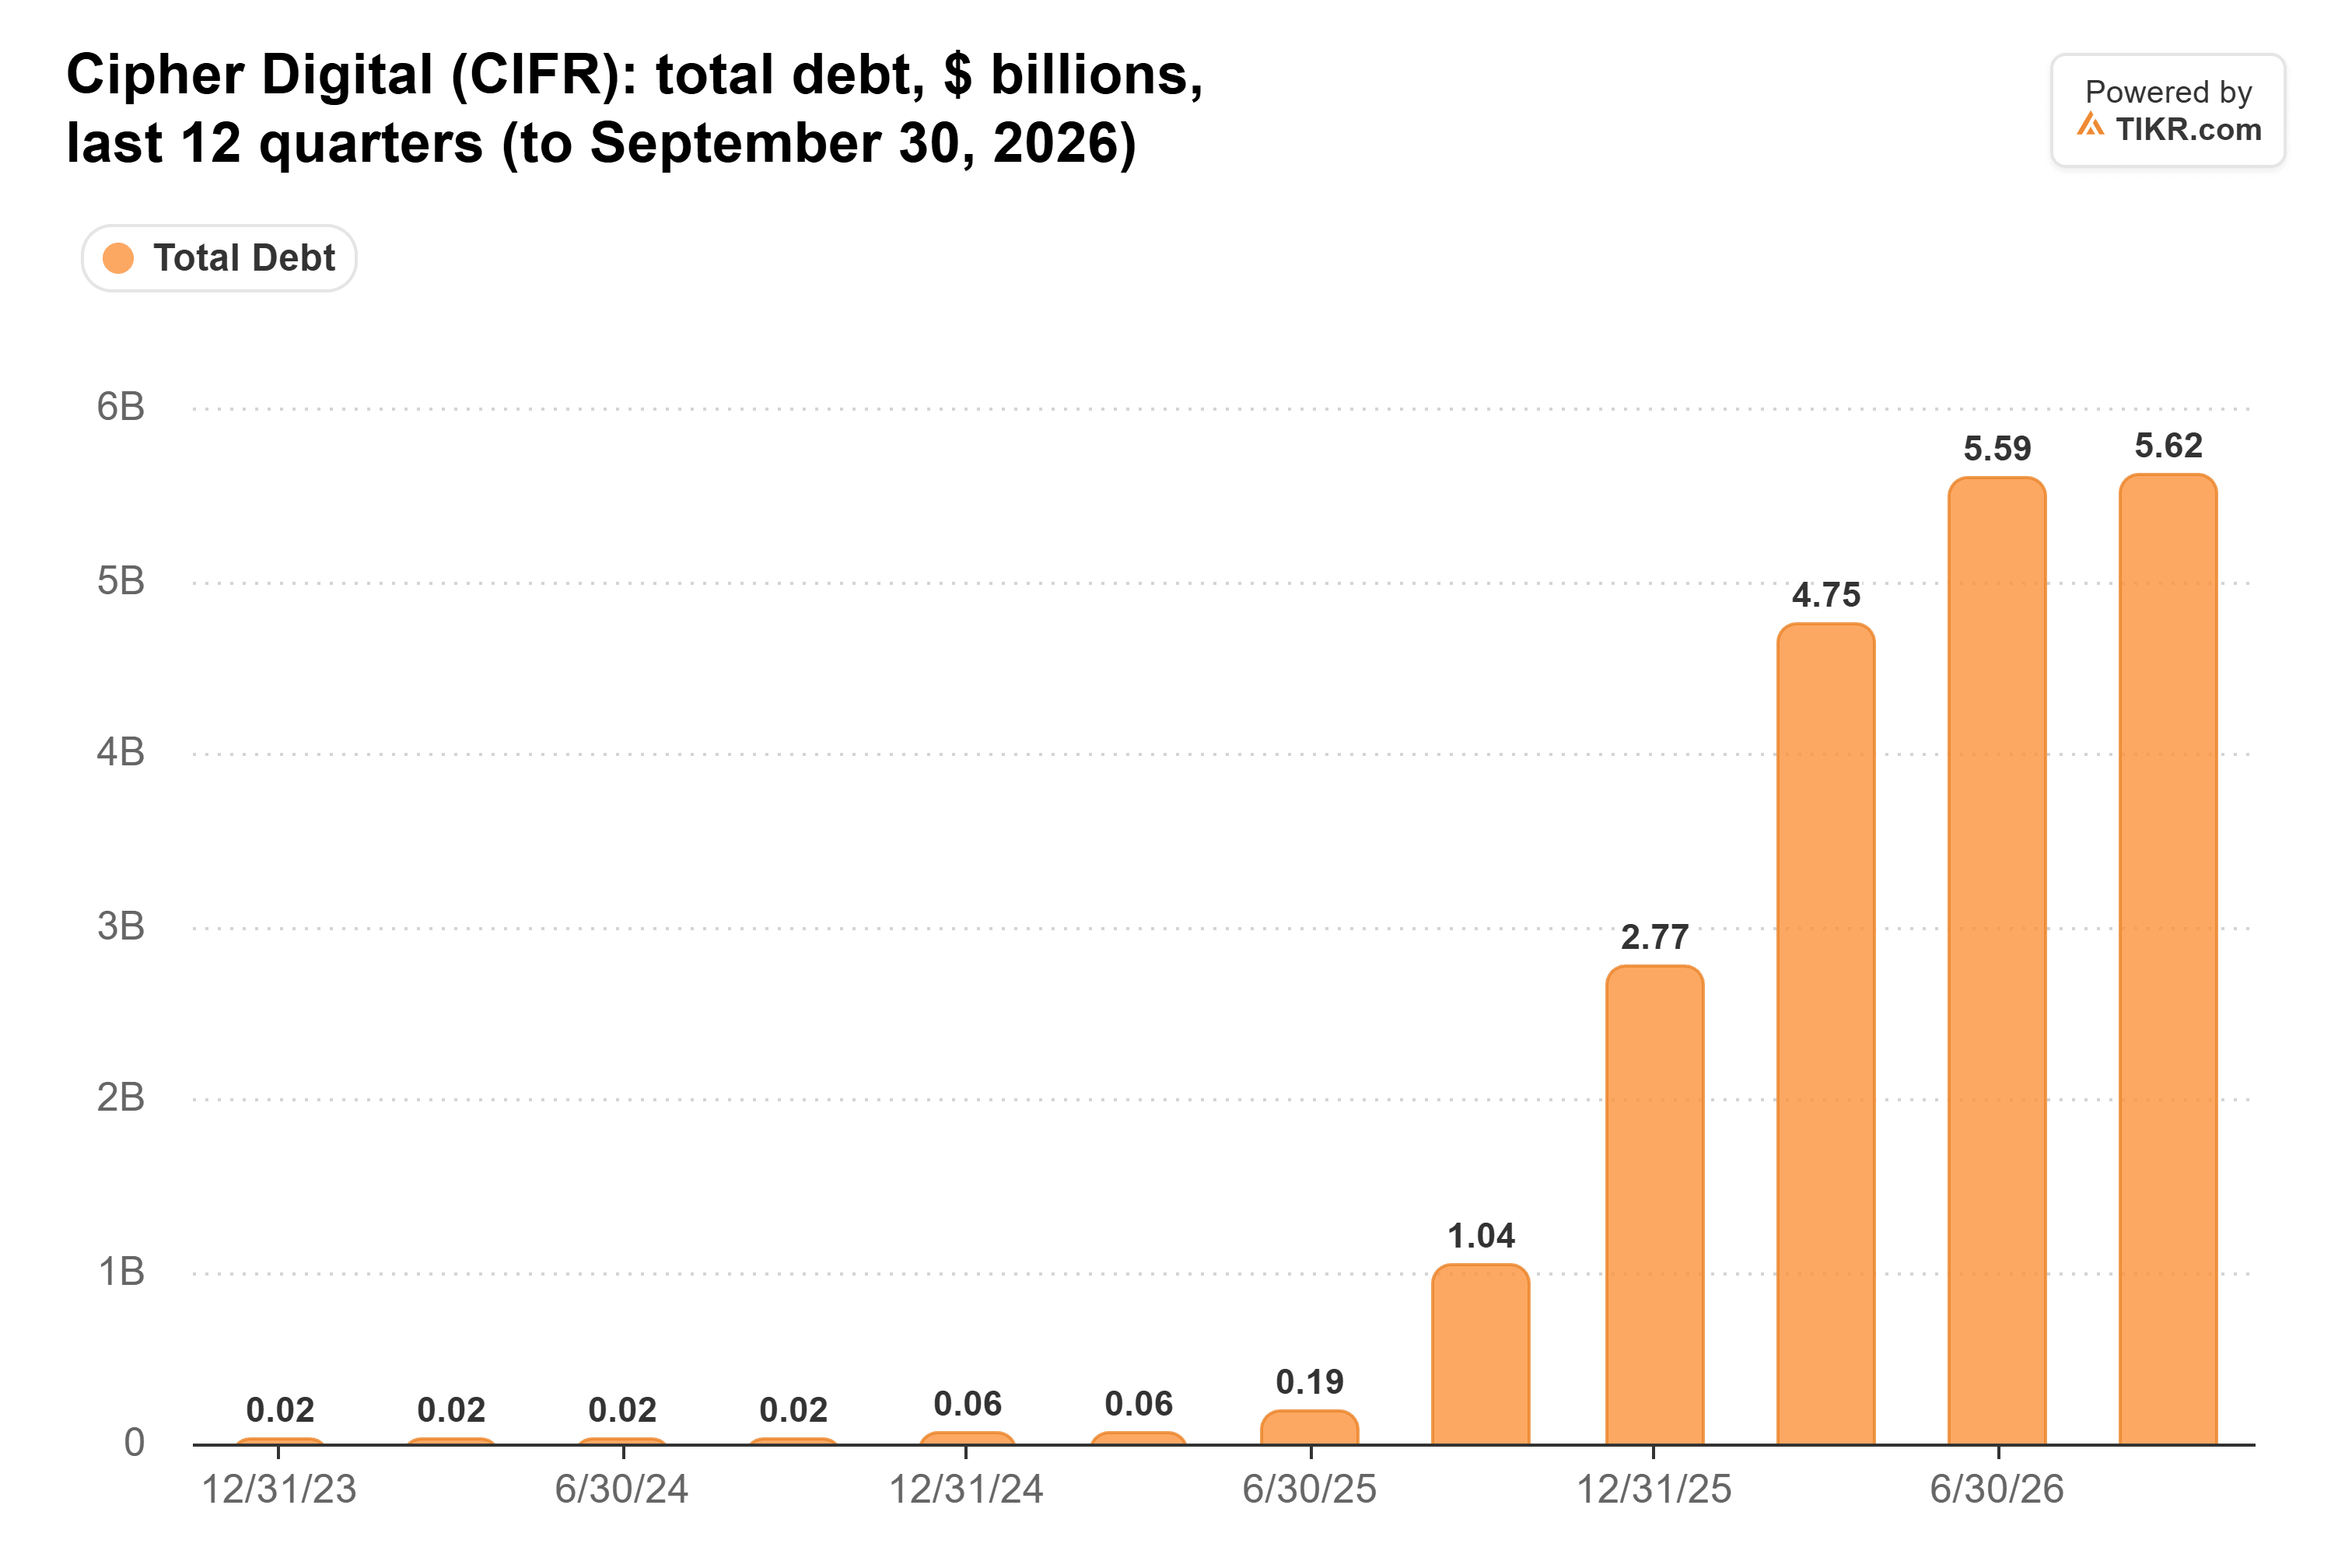
Black Pearl’s $2.0 billion bond initially costs $122.5 million a year in interest, against AWS rent averaging about $367 million a year. Once construction is complete, principal repayments start at $140 million a year. But the bond matures in 2031, a decade before the lease ends. And all three of Cipher’s contracted campuses are in Texas, where Governor-elect Gina Hinojosa campaigned on pausing new data center approvals until lawmakers pass protections.
What a 7% Cap Rate Would Imply for Cipher
At a 7% yield, Cipher’s $864 million of projected property income would be worth about $12.3 billion, roughly twice its debt. A buyer would want more yield for turnkey halls. Even at 9%, that income is worth about $9.6 billion, a cushion a 4.7x sales multiple doesn’t seem to credit.
Cipher’s next lease, at Reveille, Ulysses or Odessa, and how it funds it, will show whether that valuation looks achievable.
So What Is Cipher Digital Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cipher Digital could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!