Key Takeaways
- Ciena stock is up 58% in the past year, and its fiscal third-quarter revenue rose 37% to $1.67 billion.
- Analysts expect EPS to grow 65% in fiscal 2027 while management guides revenue up at least 30%, so the estimates only work if margins keep widening.
- Gross margin has gone up this year, but Ciena guides it lower for the fourth quarter and expects payments for supply deals to cut into its cash.
- December’s report has to show that the fourth-quarter dip is temporary and that Ciena’s growth is still turning into cash.
Ciena (CIEN) stock is up 58% in the past year, and its next report has to clear a higher bar than another big revenue number.
The past week showed how fast sentiment can swing. Ciena fell 11.3% on Nov. 2 as Marvell Technology’s all-stock deal for Lumentum and a broader AI selloff hit optical stocks, then bounced 5.5% on Nov. 3 as chip stocks recovered. After that day’s close, Arista Networks, which sells into the same hyperscaler buildout, reported third-quarter revenue up 58.5% to about $3.66 billion. That puts data-center networking back in front of investors a few weeks before Ciena’s fiscal fourth quarter comes out in December.
Demand looks secure. Ciena ended its fiscal third quarter, the three months to Aug. 1, with an $8.5 billion backlog. That’s up $800 million from the quarter before, and management expects it to top $10 billion by the end of fiscal 2026. Revenue from cloud providers buying directly from Ciena rose more than 80% from a year earlier.
The estimates need wider margins
Analysts expect profit to grow much faster than sales. The consensus has normalized EPS nearly tripling in fiscal 2026, the year that ended in October, then reaching $11.86 in fiscal 2027 and $17.54 in fiscal 2028:

Management guides fiscal 2027 revenue up at least 30%, to $8.3- $8.4 billion. The consensus has EPS up 65% that year. That gap only closes if margins widen, and Ciena says they will: it’s aiming for an adjusted operating margin of 25%-27% in fiscal 2027.
TIKR tracks 21 analysts on Ciena. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Ciena, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Ciena’s Analyst Ratings
So far, gross margin has held up
Ciena’s record here is stronger than you might think. As cloud sales took a bigger share of the business, its gross margin rose to 45.4% in the fiscal third quarter, from 41.3% a year earlier. In the second quarter it was 44.0%, against 40.2% a year before. Ciena’s quarterly report credits cost cuts, pricing and product mix, plus tariff refunds in the third quarter.
On an adjusted basis, third-quarter gross margin reached 46.4%, and the operating margin hit a record 22.5%.
Ciena’s fourth-quarter guidance is a step back, though: an adjusted gross margin of 45%, give or take half a point, and an adjusted operating margin around 20%. Part of that drop was flagged in advance. Tariff refunds added about 70 basis points to third-quarter adjusted gross margin, and management doesn’t expect them to repeat. December’s report needs an adjusted gross margin of 45% or better and a fiscal 2027 outlook that still points to 25%-27%.
The cash is the weaker half
Free cash flow has a bumpier record, swinging from negative $259 million in fiscal 2022 to $665 million in fiscal 2025:
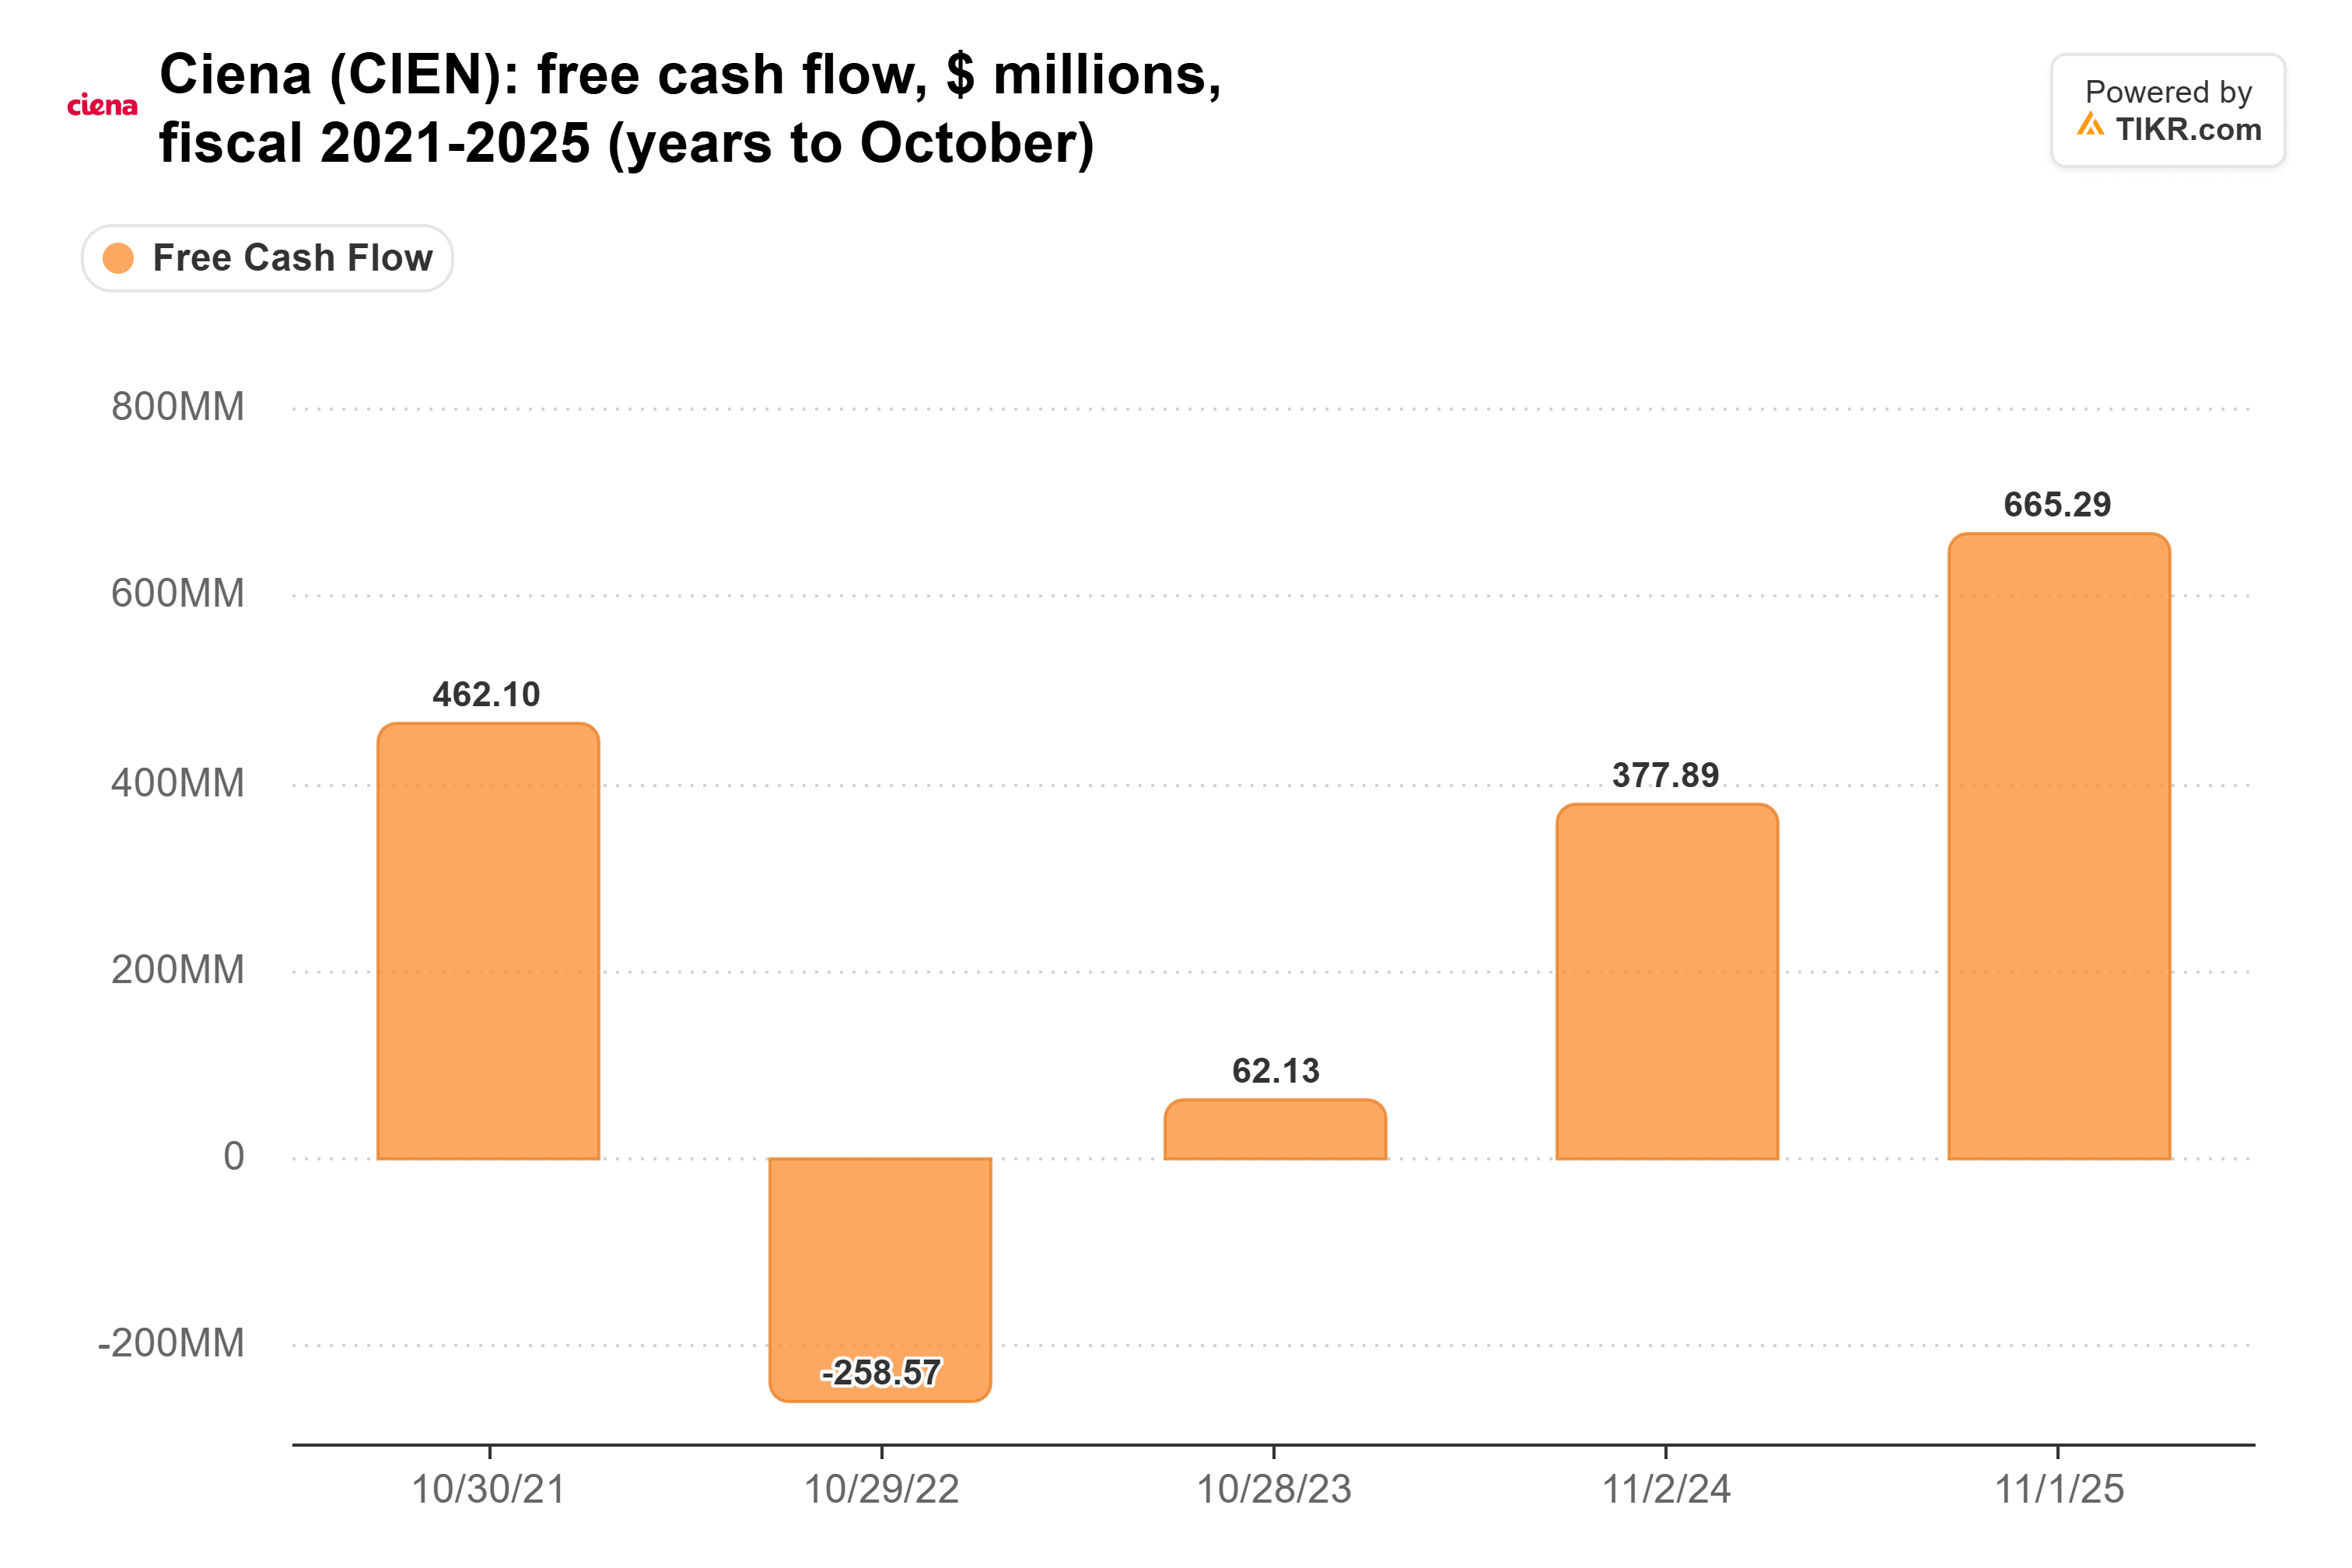
That $665 million was a five-year high, a good sign that growth is turning into cash. But key optical components are still scarce, and management doesn’t expect supply and demand to come back into balance before 2028. Ciena is paying to lock in capacity under supply agreements that run through 2029, and it expects operating cash flow to fall in the fourth quarter as those payments go out.
One quarter of that is manageable. December’s report should show how big those payments are, and whether they keep eating into cash next year. Also, two customers made up 41.7% of third-quarter revenue, up from 34.0% in the second quarter, so one hyperscaler pulling back would show up fast.
Reasonable, if the margins show up
At the Nov. 3 close of $300.08, about 53% below its 52-week intraday high of $637.51, Ciena traded at about 25x the fiscal 2027 consensus. Investors paying that are already counting on the margin step-up. Bernstein, which started coverage on Sept. 30 at Outperform with a $440 target, sees about 47% upside from that close, and the Street’s average target sits higher, around $513.
Ciena has already shown that cloud growth can come with wider margins, and that was the harder question. If December’s report shows the supply payments are a one-quarter hit and the backlog cleared $10 billion, the estimates look earnable, and the current price looks reasonable.
Of course, if the fiscal 2027 outlook trims that 25%-27% operating margin target, the estimates will come down with it.
So what is Ciena stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Ciena could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!