Key Takeaways
- Celestica stock is down 36% in the past month, even though it beat its own third-quarter guidance and forecast $40.0 billion of revenue for 2027.
- Celestica fell with the rest of the AI hardware group, including Dell and Super Micro, and had no bad news of its own.
- The main risk is cash: Celestica cut its 2026 free cash flow outlook to $460 million and plans $1.5 billion to $2.0 billion of capital spending in 2027.
- Analysts’ estimates and targets have held up through the drop, and if the 2027 outlook holds, the sell-off looks like an overreaction.
Celestica (CLS) stock is down 36% in the past month, and Celestica gave investors very little reason to sell. Its third-quarter results beat the top of its own guidance, and its first outlook for 2027 calls for 90% revenue growth.
It got caught in a sell-off of AI hardware stocks instead. It fell alongside Flex and Sanmina on Oct. 22 with no news of its own. Over the month, Dell Technologies lost 30% and Super Micro Computer 29%, while the Nasdaq 100 fell 9%.
Wall Street hasn’t wavered. On Oct. 29, CIBC analyst Todd Coupland kept his Buy rating and $500 price target, 101% above Monday’s close.
TIKR tracks 21 analysts on Celestica. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Celestica, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Celestica’s Analyst Ratings
The quarter was a blowout
Celestica reported after the close on Oct. 26, and the numbers beat both its own guidance and Wall Street’s:
- Third-quarter revenue of $5.83 billion, up 83% from a year earlier, against a $5.47 billion consensus
- Adjusted EPS of $3.30, up 109%, against $2.96
- A record adjusted operating margin of 8.5%
- A 2026 outlook raised to $21.0 billion of revenue and $11.55 of adjusted EPS
- A first 2027 outlook of $40.0 billion of revenue, $21.50 of adjusted EPS and a 9.0% margin, where analysts had expected $35.71 billion of revenue
Chair and CEO Rob Mionis went further in the release: “The demand environment continues to be very robust, supporting our 2027 revenue outlook, with customer demand forecasts meaningfully higher for 2028.”
The stock jumped 12% the next day and gave it back within a week. Analysts now expect normalized EPS to nearly double again in 2027, to $22.24, a touch above the company’s own $21.50 guide:
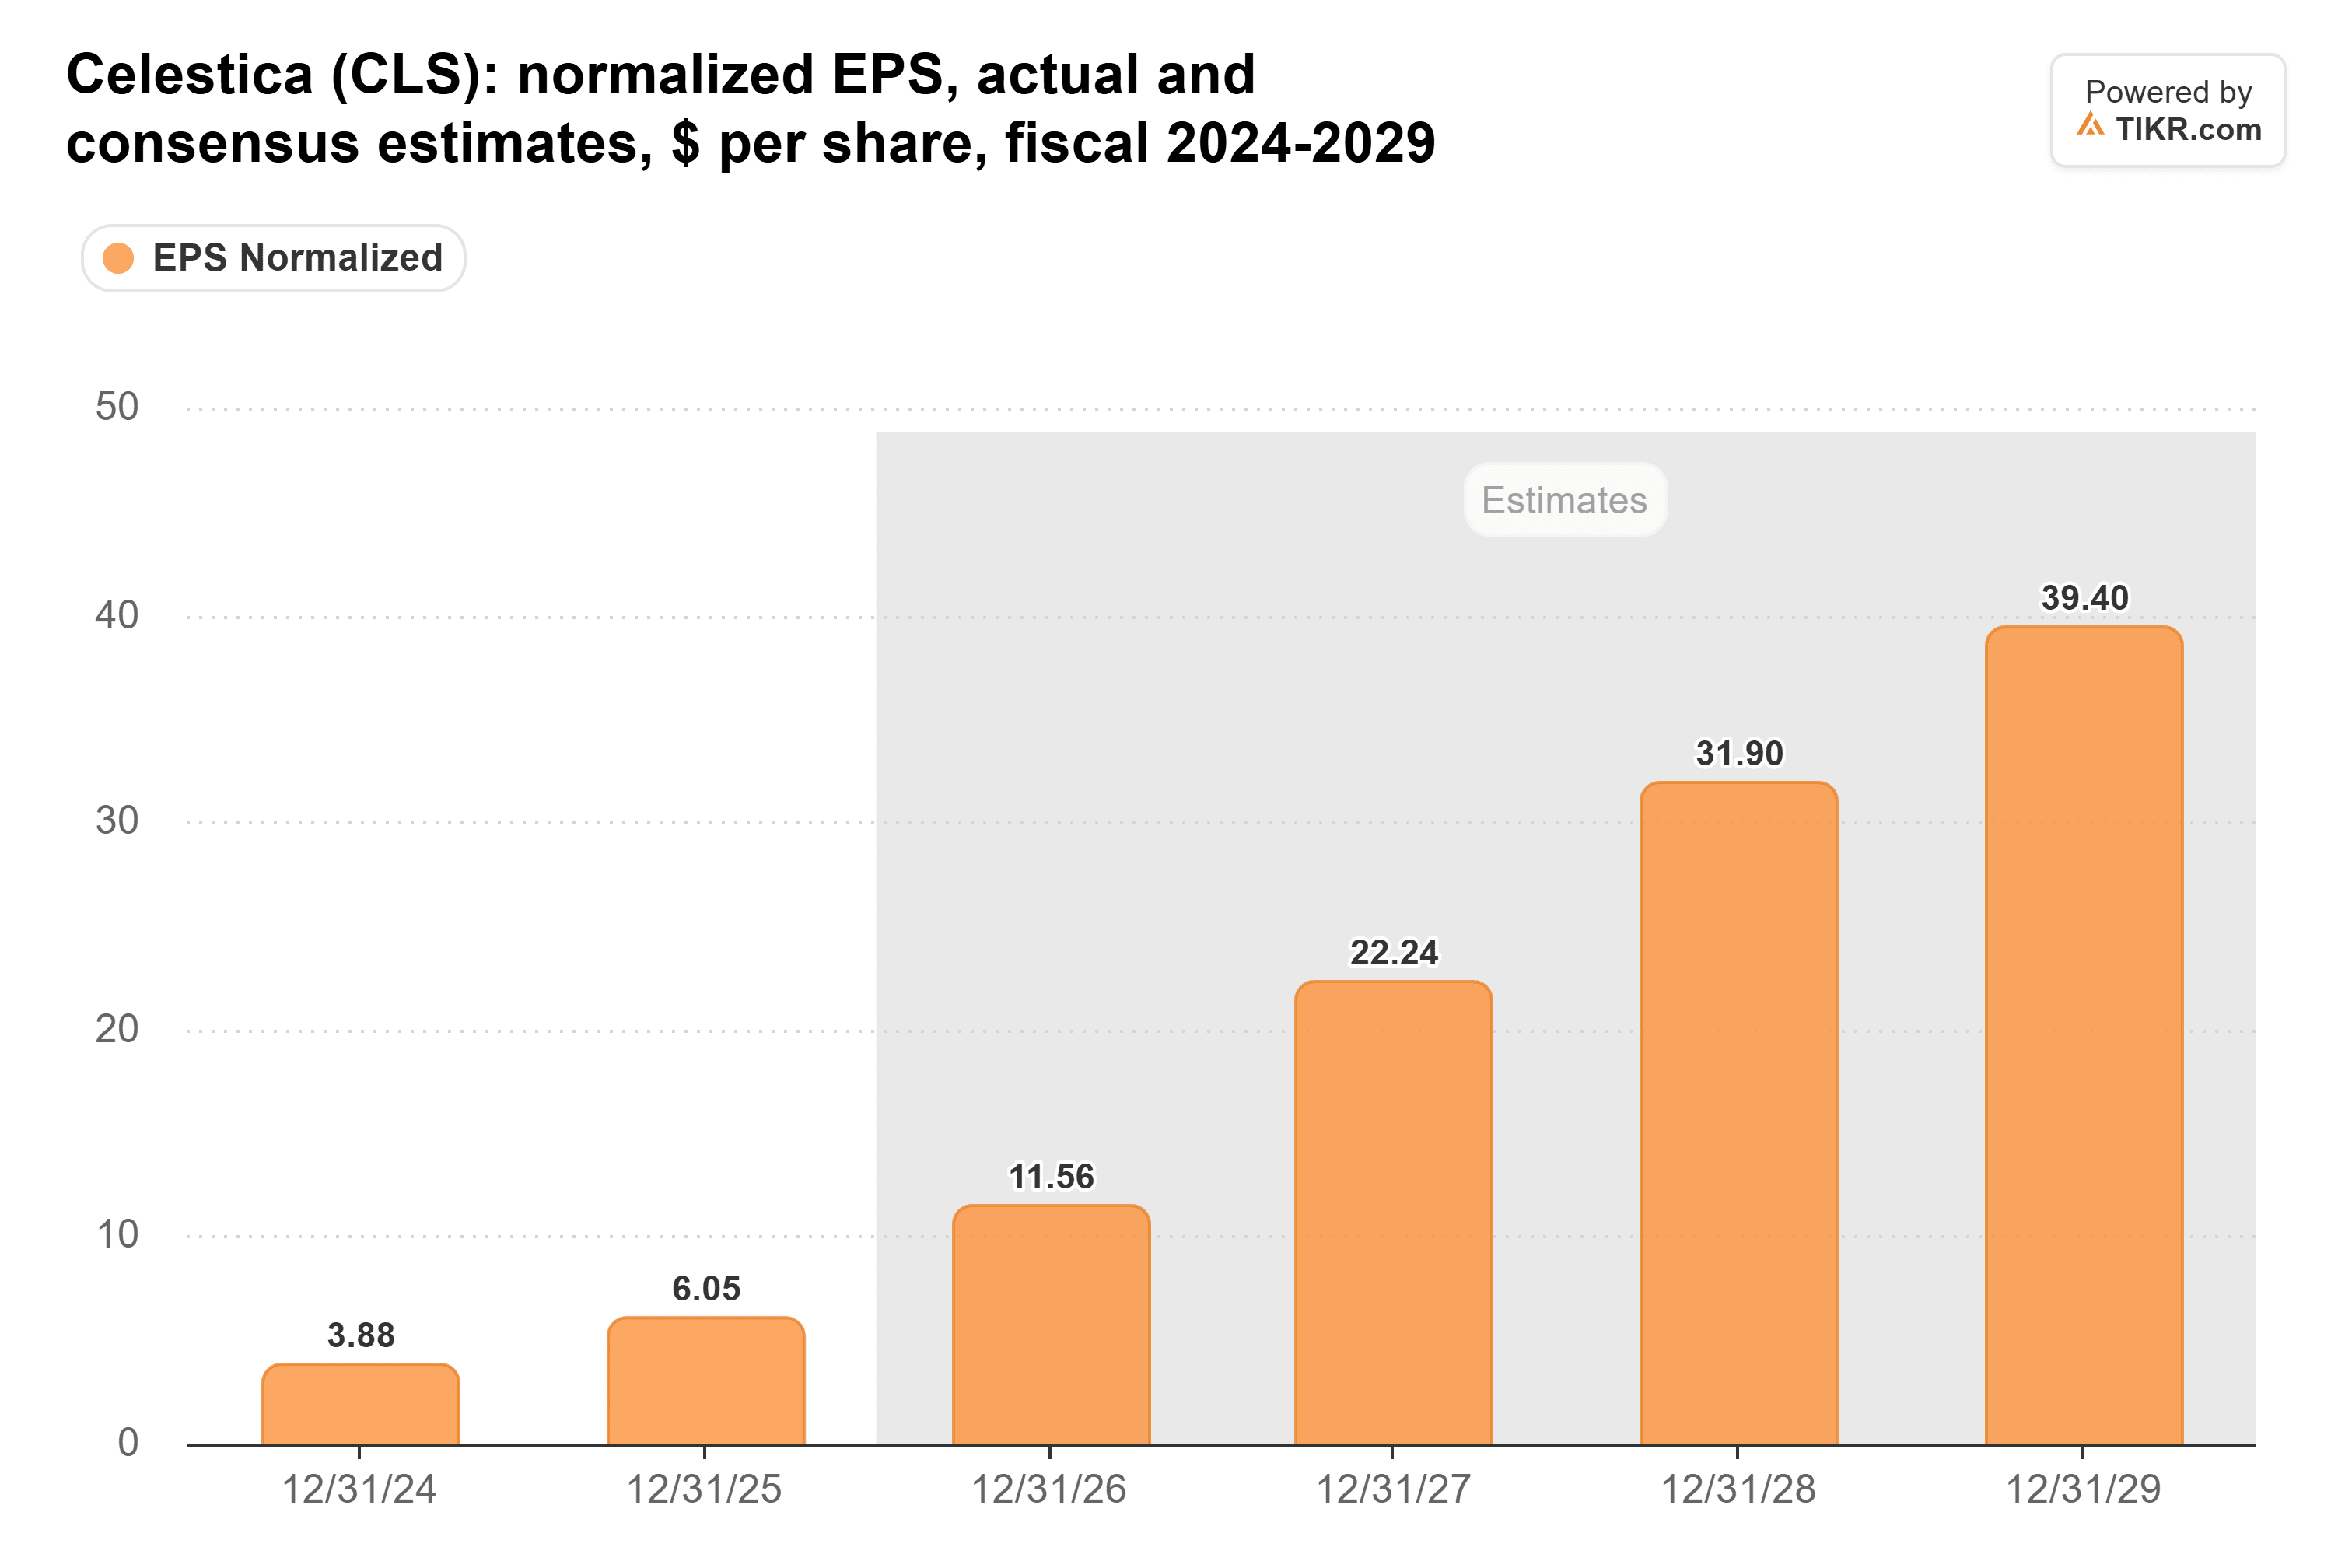
With Mionis pointing to even higher demand in 2028, nothing in this report argues for cutting those numbers.
The catch is the cash
That growth costs money, though. Celestica cut its 2026 free cash flow outlook to $460 million from $600 million, mainly to put more into working capital ahead of 2027. And it expects to spend $1.5 billion to $2.0 billion on capital expenditures in 2027.
It raised the money ahead of time. Celestica completed a $3.45 billion stock offering in the third quarter and ended September with $3.96 billion of cash. Shareholders paid for that in dilution: Celestica had 126.1 million shares outstanding on Oct. 20, about 10% more than at the end of 2025. Starting Nov. 3, it can buy back up to 3.13 million shares, about 2.5% of its public float, over the next year.
So 2027 is paid for. The question is whether customers actually place the orders they’ve forecast.
Is it a buy at 14x?
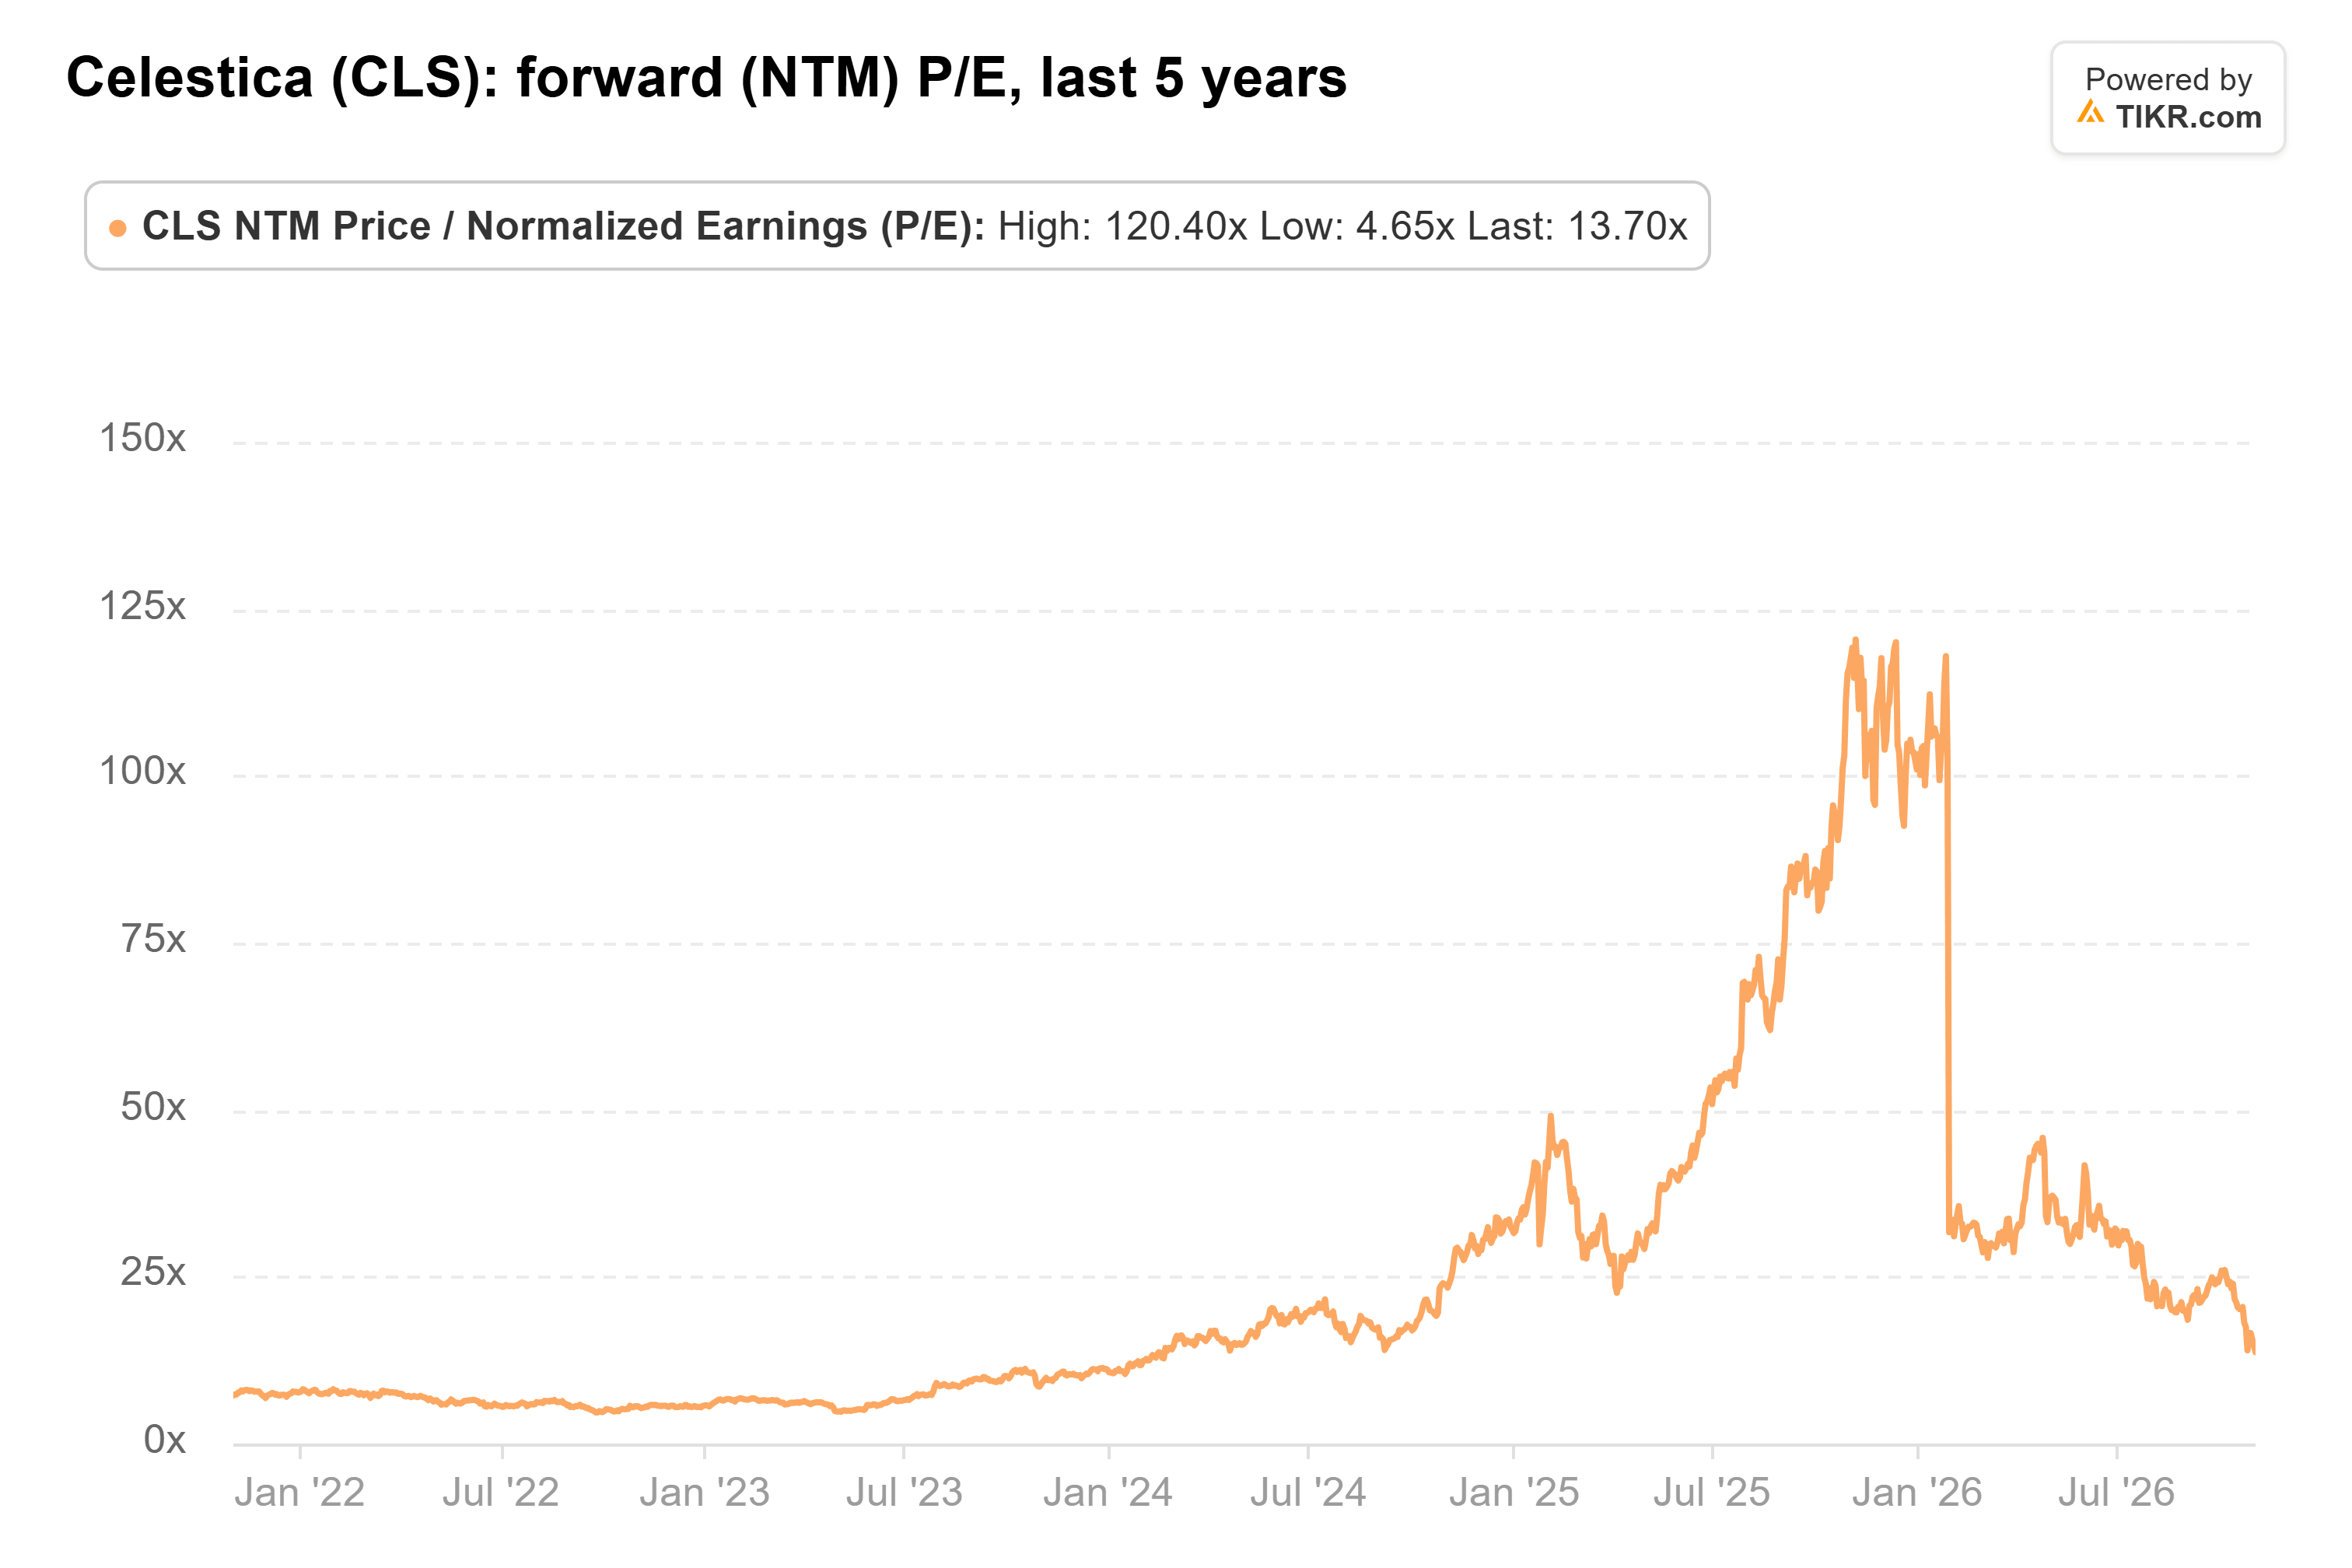
As of Monday’s close, the stock trades at 14x forward earnings, far below its 5-year average of 25x:
Analysts haven’t backed off either. Citi, UBS and Barclays all raised their targets on Oct. 28, and the average target has climbed to $465 from $324 a year earlier:
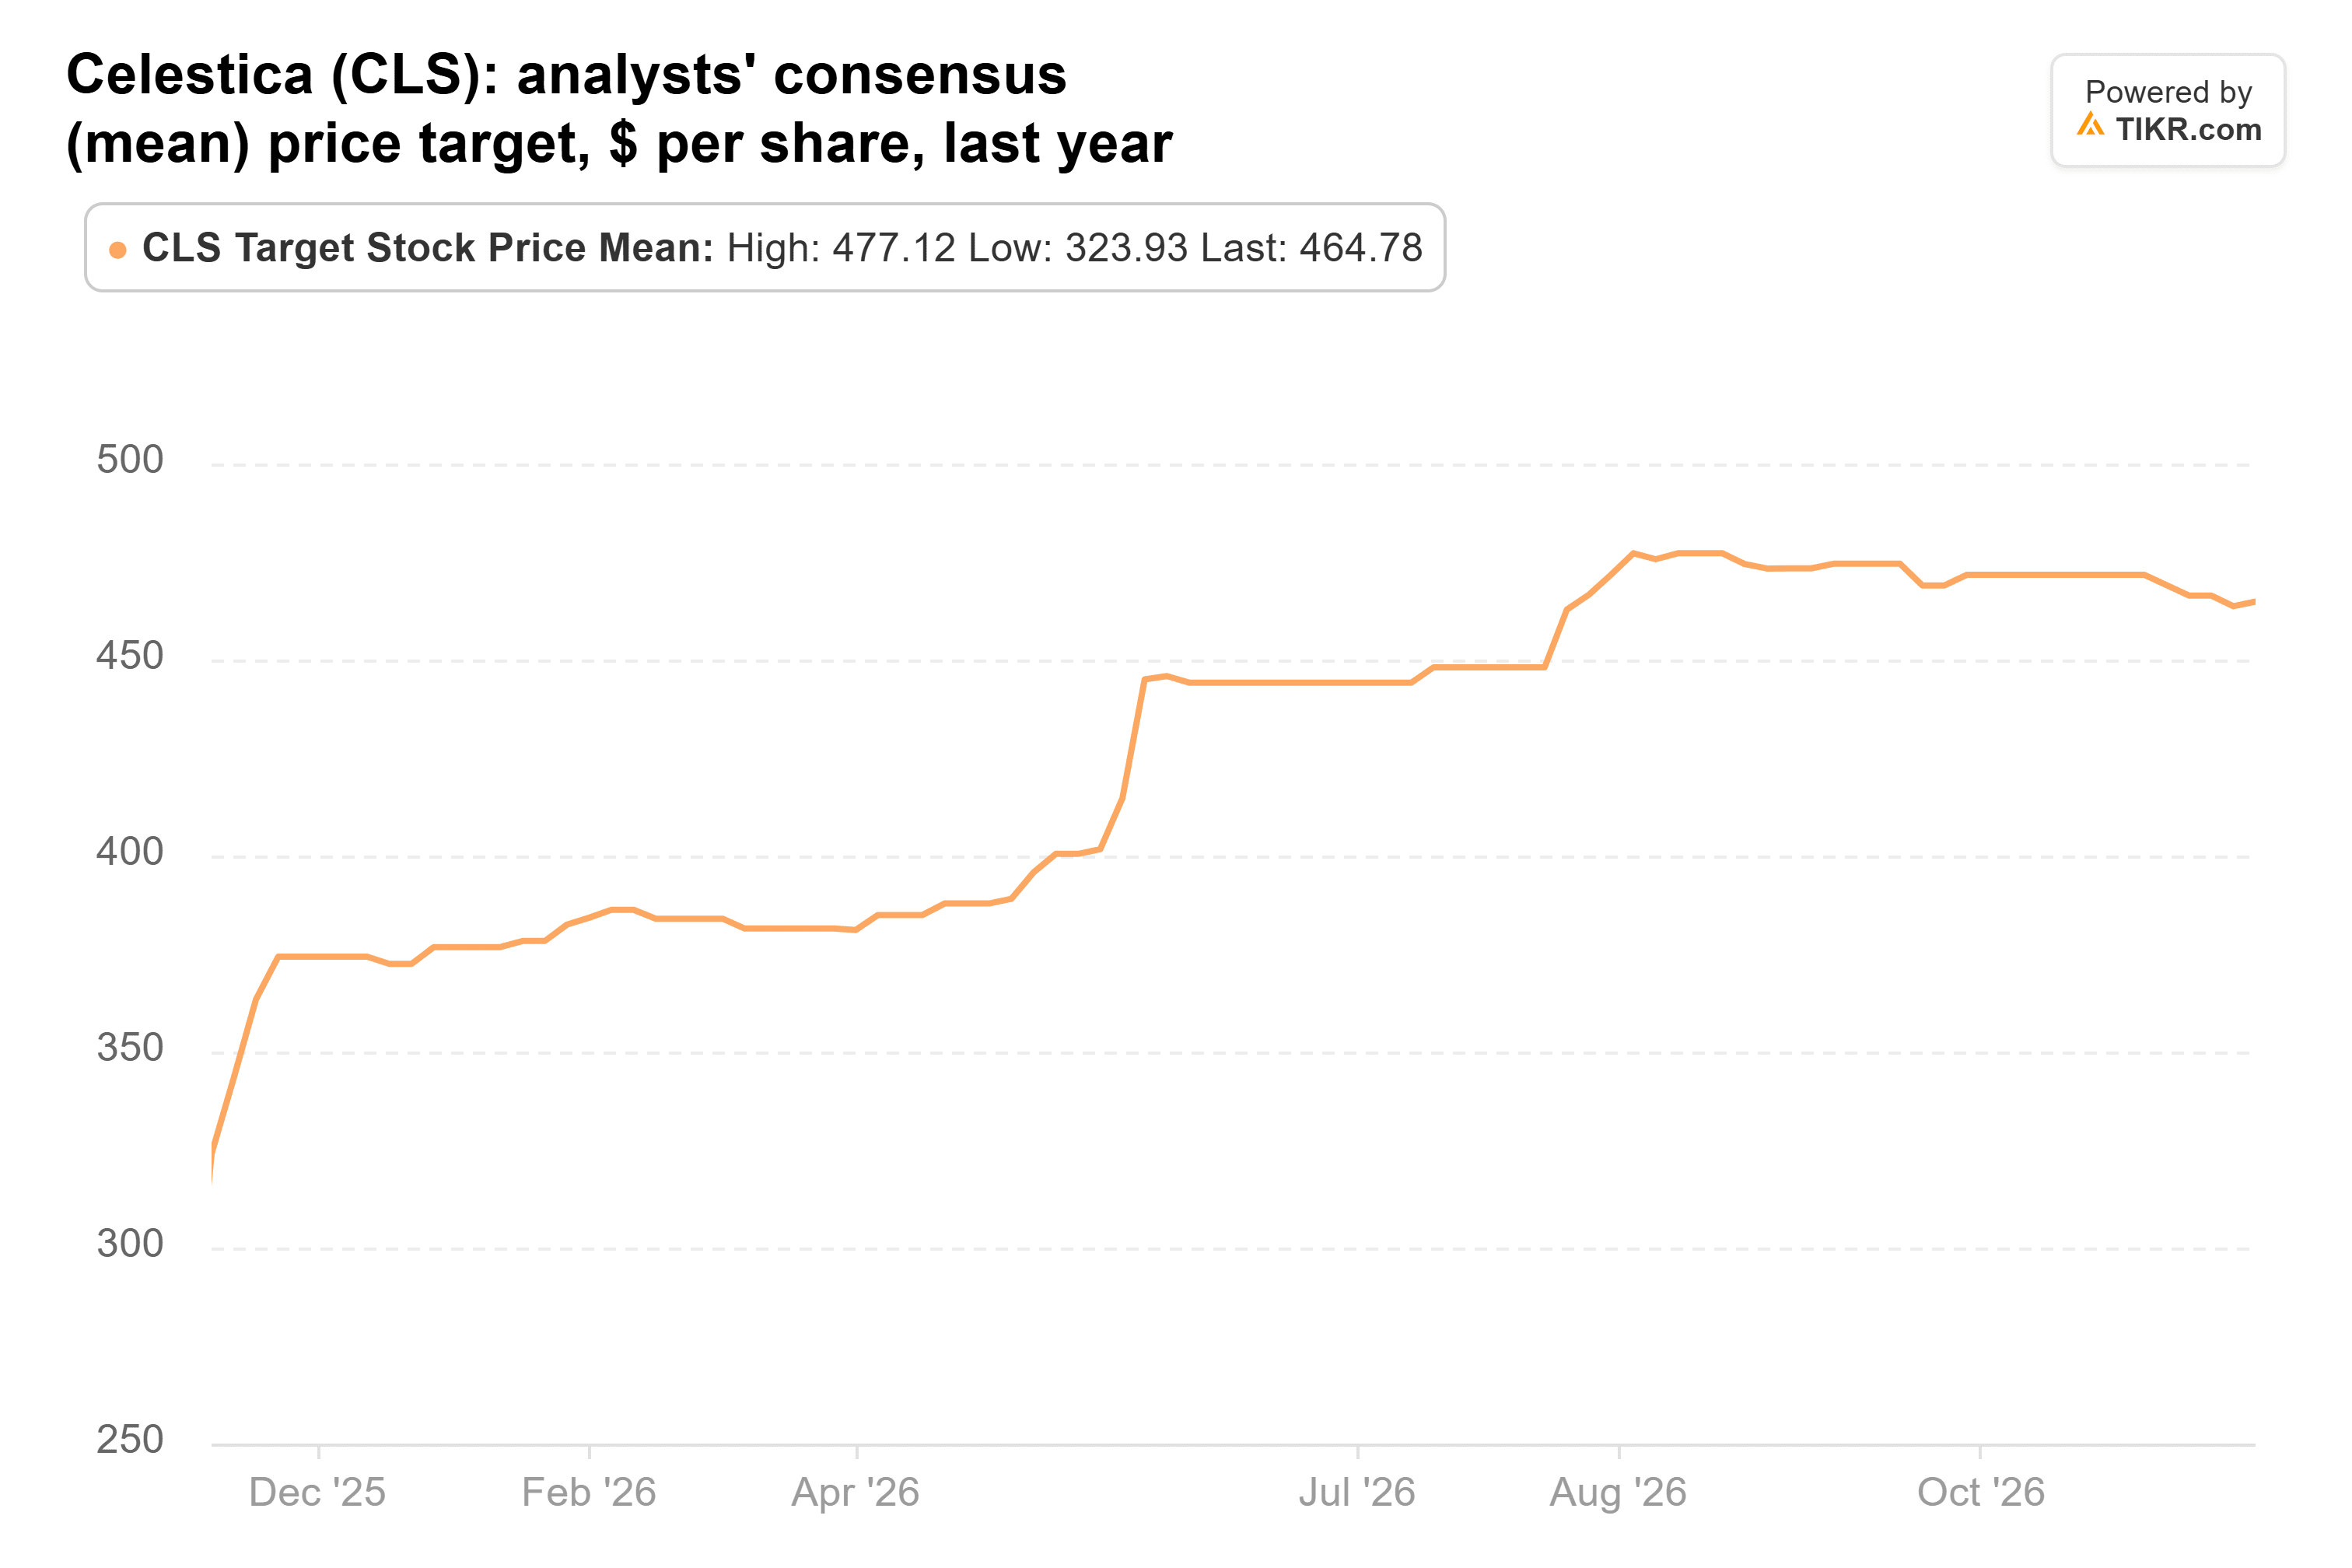
CIBC’s $500 works out to about 23x Celestica’s own 2027 EPS guide, which is still under the stock’s 5-year average. So CIBC only needs Celestica to hit its guide and the stock to return to its usual multiple.
Here’s where I land: 14x earnings for a company guiding to 90% revenue growth next year looks like an overreaction to the AI hardware sell-off. The risk is that Celestica spends the cash before the revenue shows up, or that AI spending cools before those 2028 forecasts turn into orders.
The next check comes with fourth-quarter results, likely in late January. Celestica guided to $6.275 billion to $6.575 billion of revenue and $3.37 to $3.57 of adjusted EPS for the quarter.
So what is Celestica stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Celestica could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!