Key Takeaways
- Caterpillar has lost about 44% of its market value since its June 30 peak, even after third-quarter sales rose 17% to a record $20.7 billion.
- Backlog hit a record $78.1 billion, and power generation sales grew 30% on demand for turbines and large engines sold into data centers.
- GE Vernova raised its 2026 guidance, but Caterpillar held its outlook and still expects about $2.2 billion of tariff costs this year.
- The fourth-quarter report, expected in January, should give the first detailed view of 2027 and test whether margins can rise.
Caterpillar’s order book has never been bigger. Its stock has rarely taken a harder beating.
Caterpillar (CAT) has lost about 44% of its market value since its June 30 peak, a Financial Times analysis found. The slide deepened on November 16 as investors dumped stocks tied to AI data center construction.
That makes the contrast with GE Vernova (GEV) hard to ignore. It raised its 2026 guidance on October 28 after orders jumped 96% organically. A day later, Caterpillar simply held its outlook.
The business still looks strong. So the real question is what investors should pay for it now.
A record quarter met a shrug
Caterpillar reported its biggest sales quarter ever on October 29. Adjusted EPS beat analyst estimates, yet the shares dropped 6% in premarket trading.
- Sales rose 17% to $20.7 billion.
- Adjusted EPS climbed 45% to $7.20.
- Backlog hit a record $78.1 billion, up from $72 billion a quarter earlier.
So why the drop? Management kept its full-year sales growth forecast in the mid-to-high teens. Investors who expected another raise got nothing new to price in.
The top line, at least, gives little cause for worry…
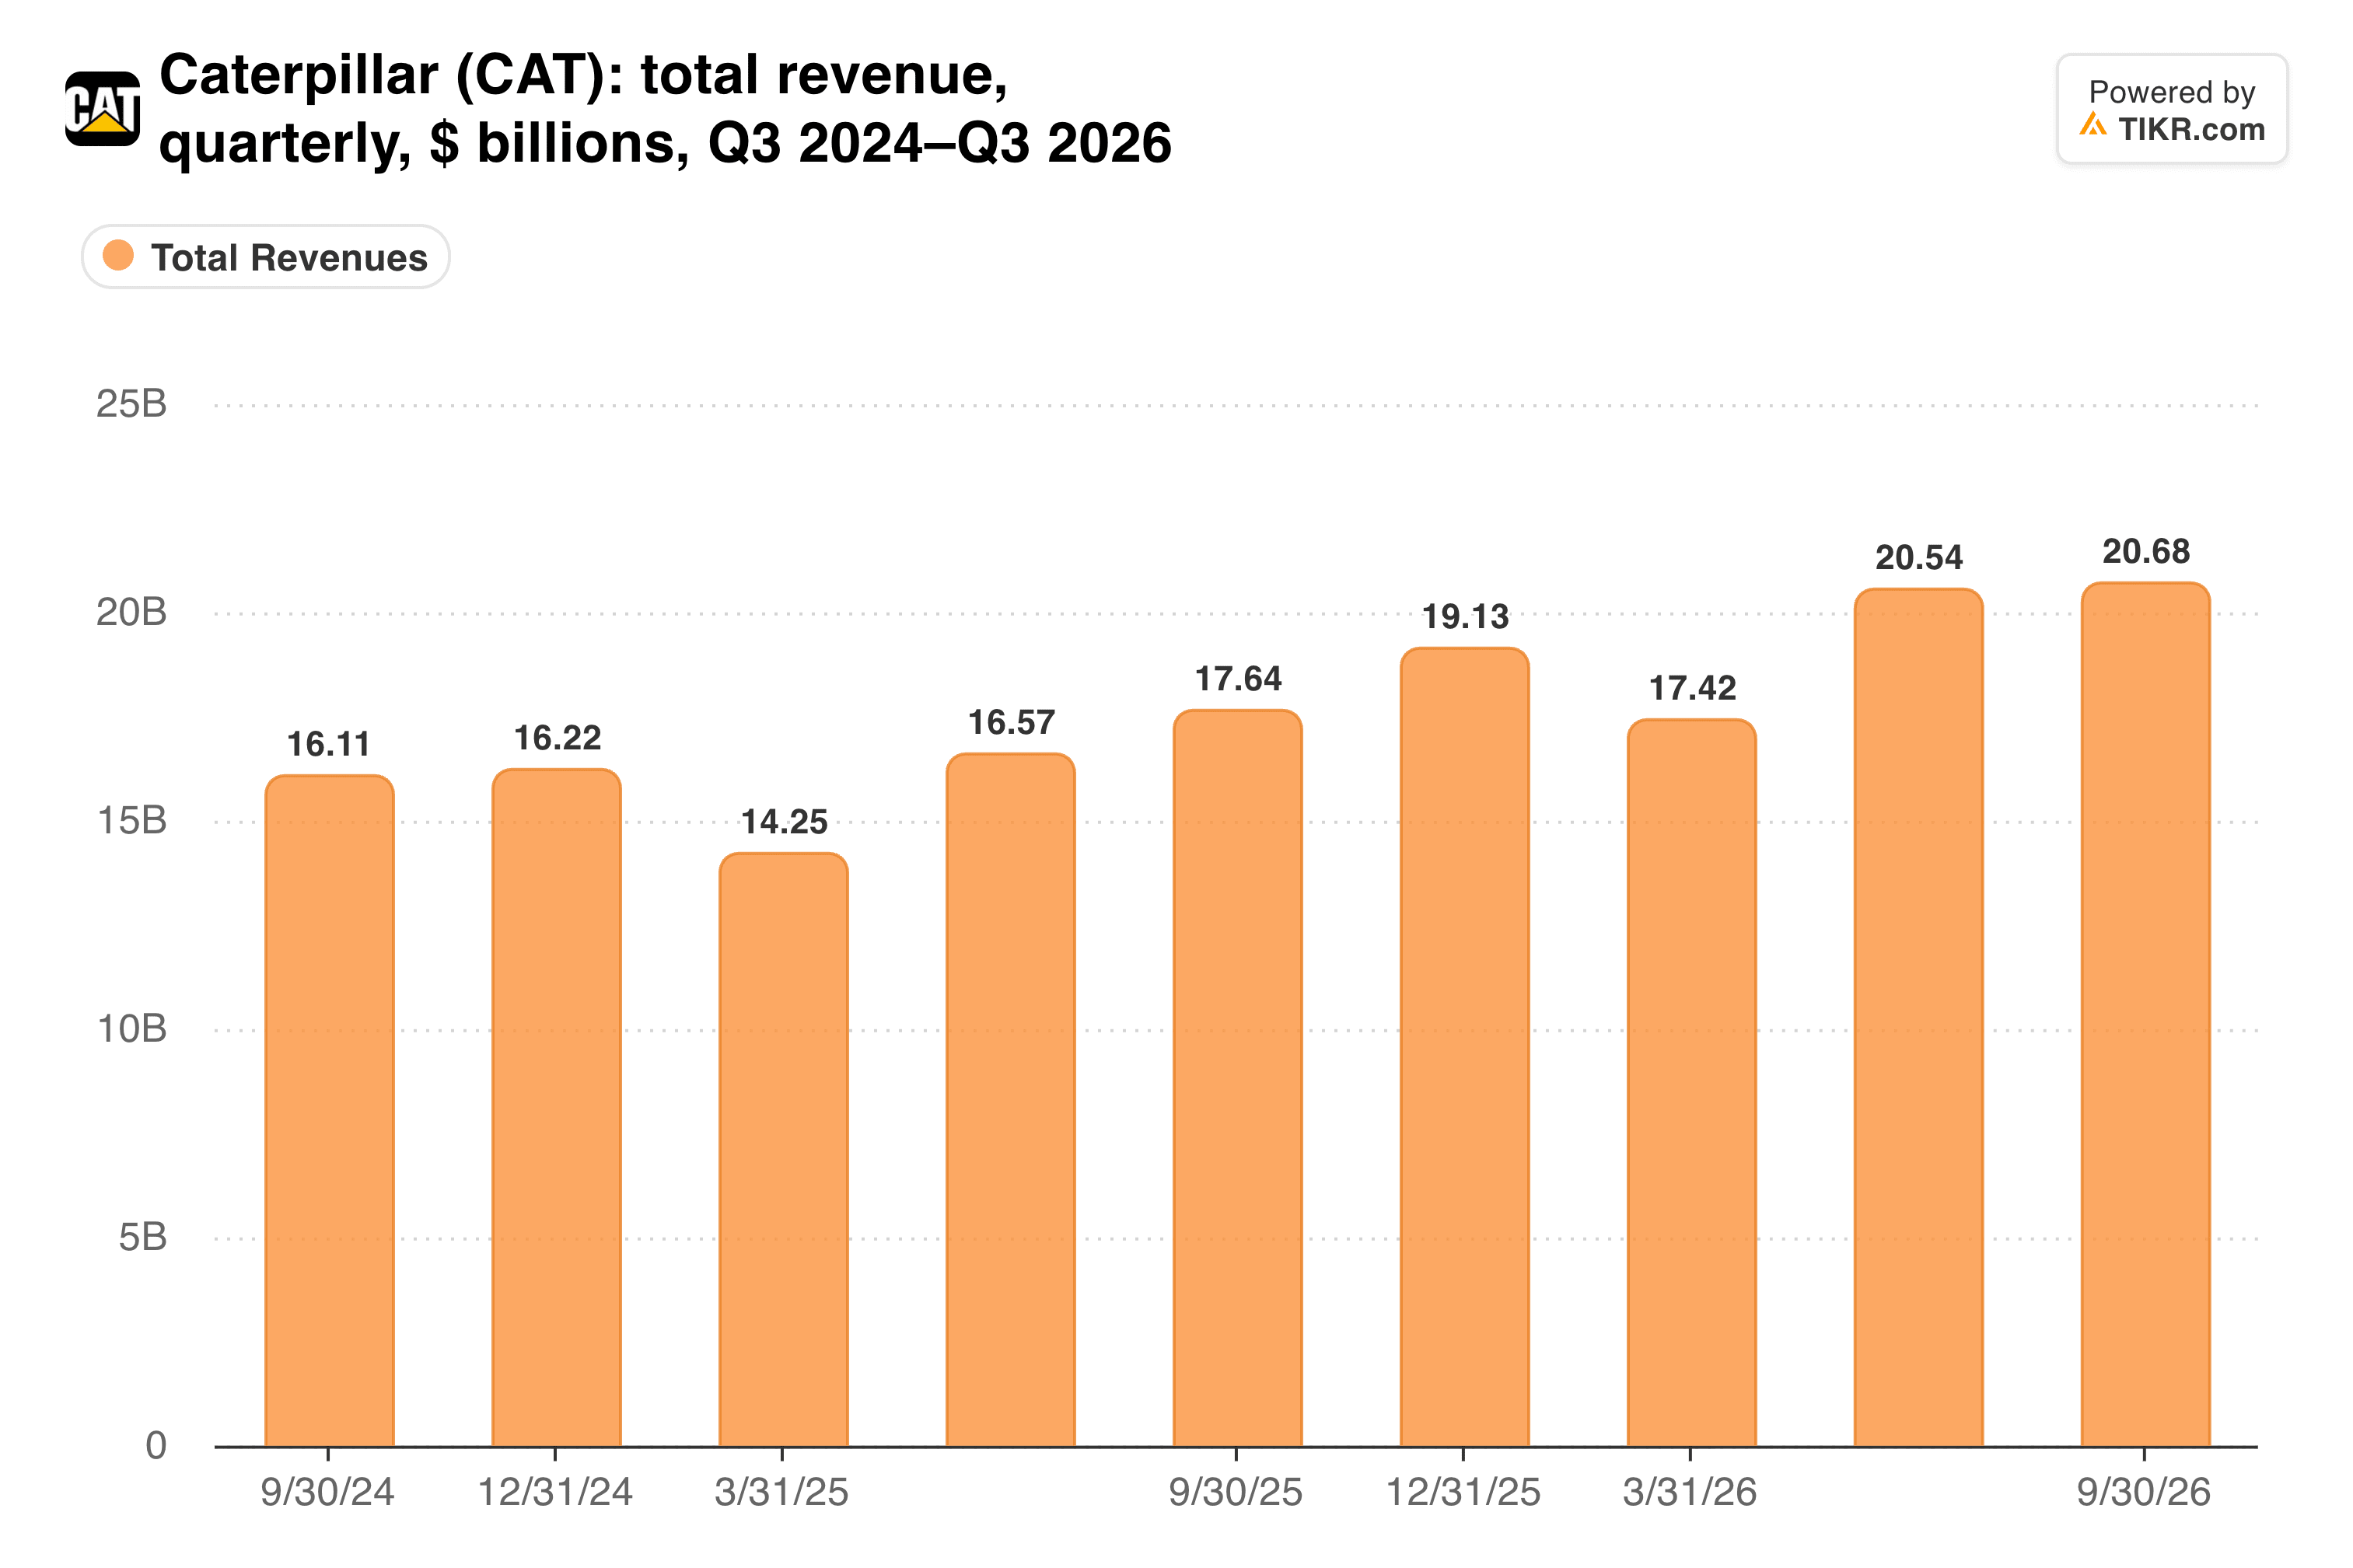
Quarterly sales have now topped $20 billion twice in a row, and the backlog has nearly doubled in a year.
Power is doing the heavy lifting
Power & Energy is where the data center money lands. Segment sales rose 18% to $8.8 billion, and profit jumped 31% to $2.1 billion. Power generation alone grew 30% to $3.4 billion, mainly from turbines and large engines sold into data centers.
CEO Joe Creed said the quarter showed “the durability of our end markets.” The order book backs him up.
Still, the peer comparison stings. GE Vernova grew revenue 27% to $12.6 billion last quarter and now carries a $197 billion backlog, more than twice Caterpillar’s. That bigger book and a raised outlook gave investors the upgrade Caterpillar didn’t.
So how fast has this segment been growing?
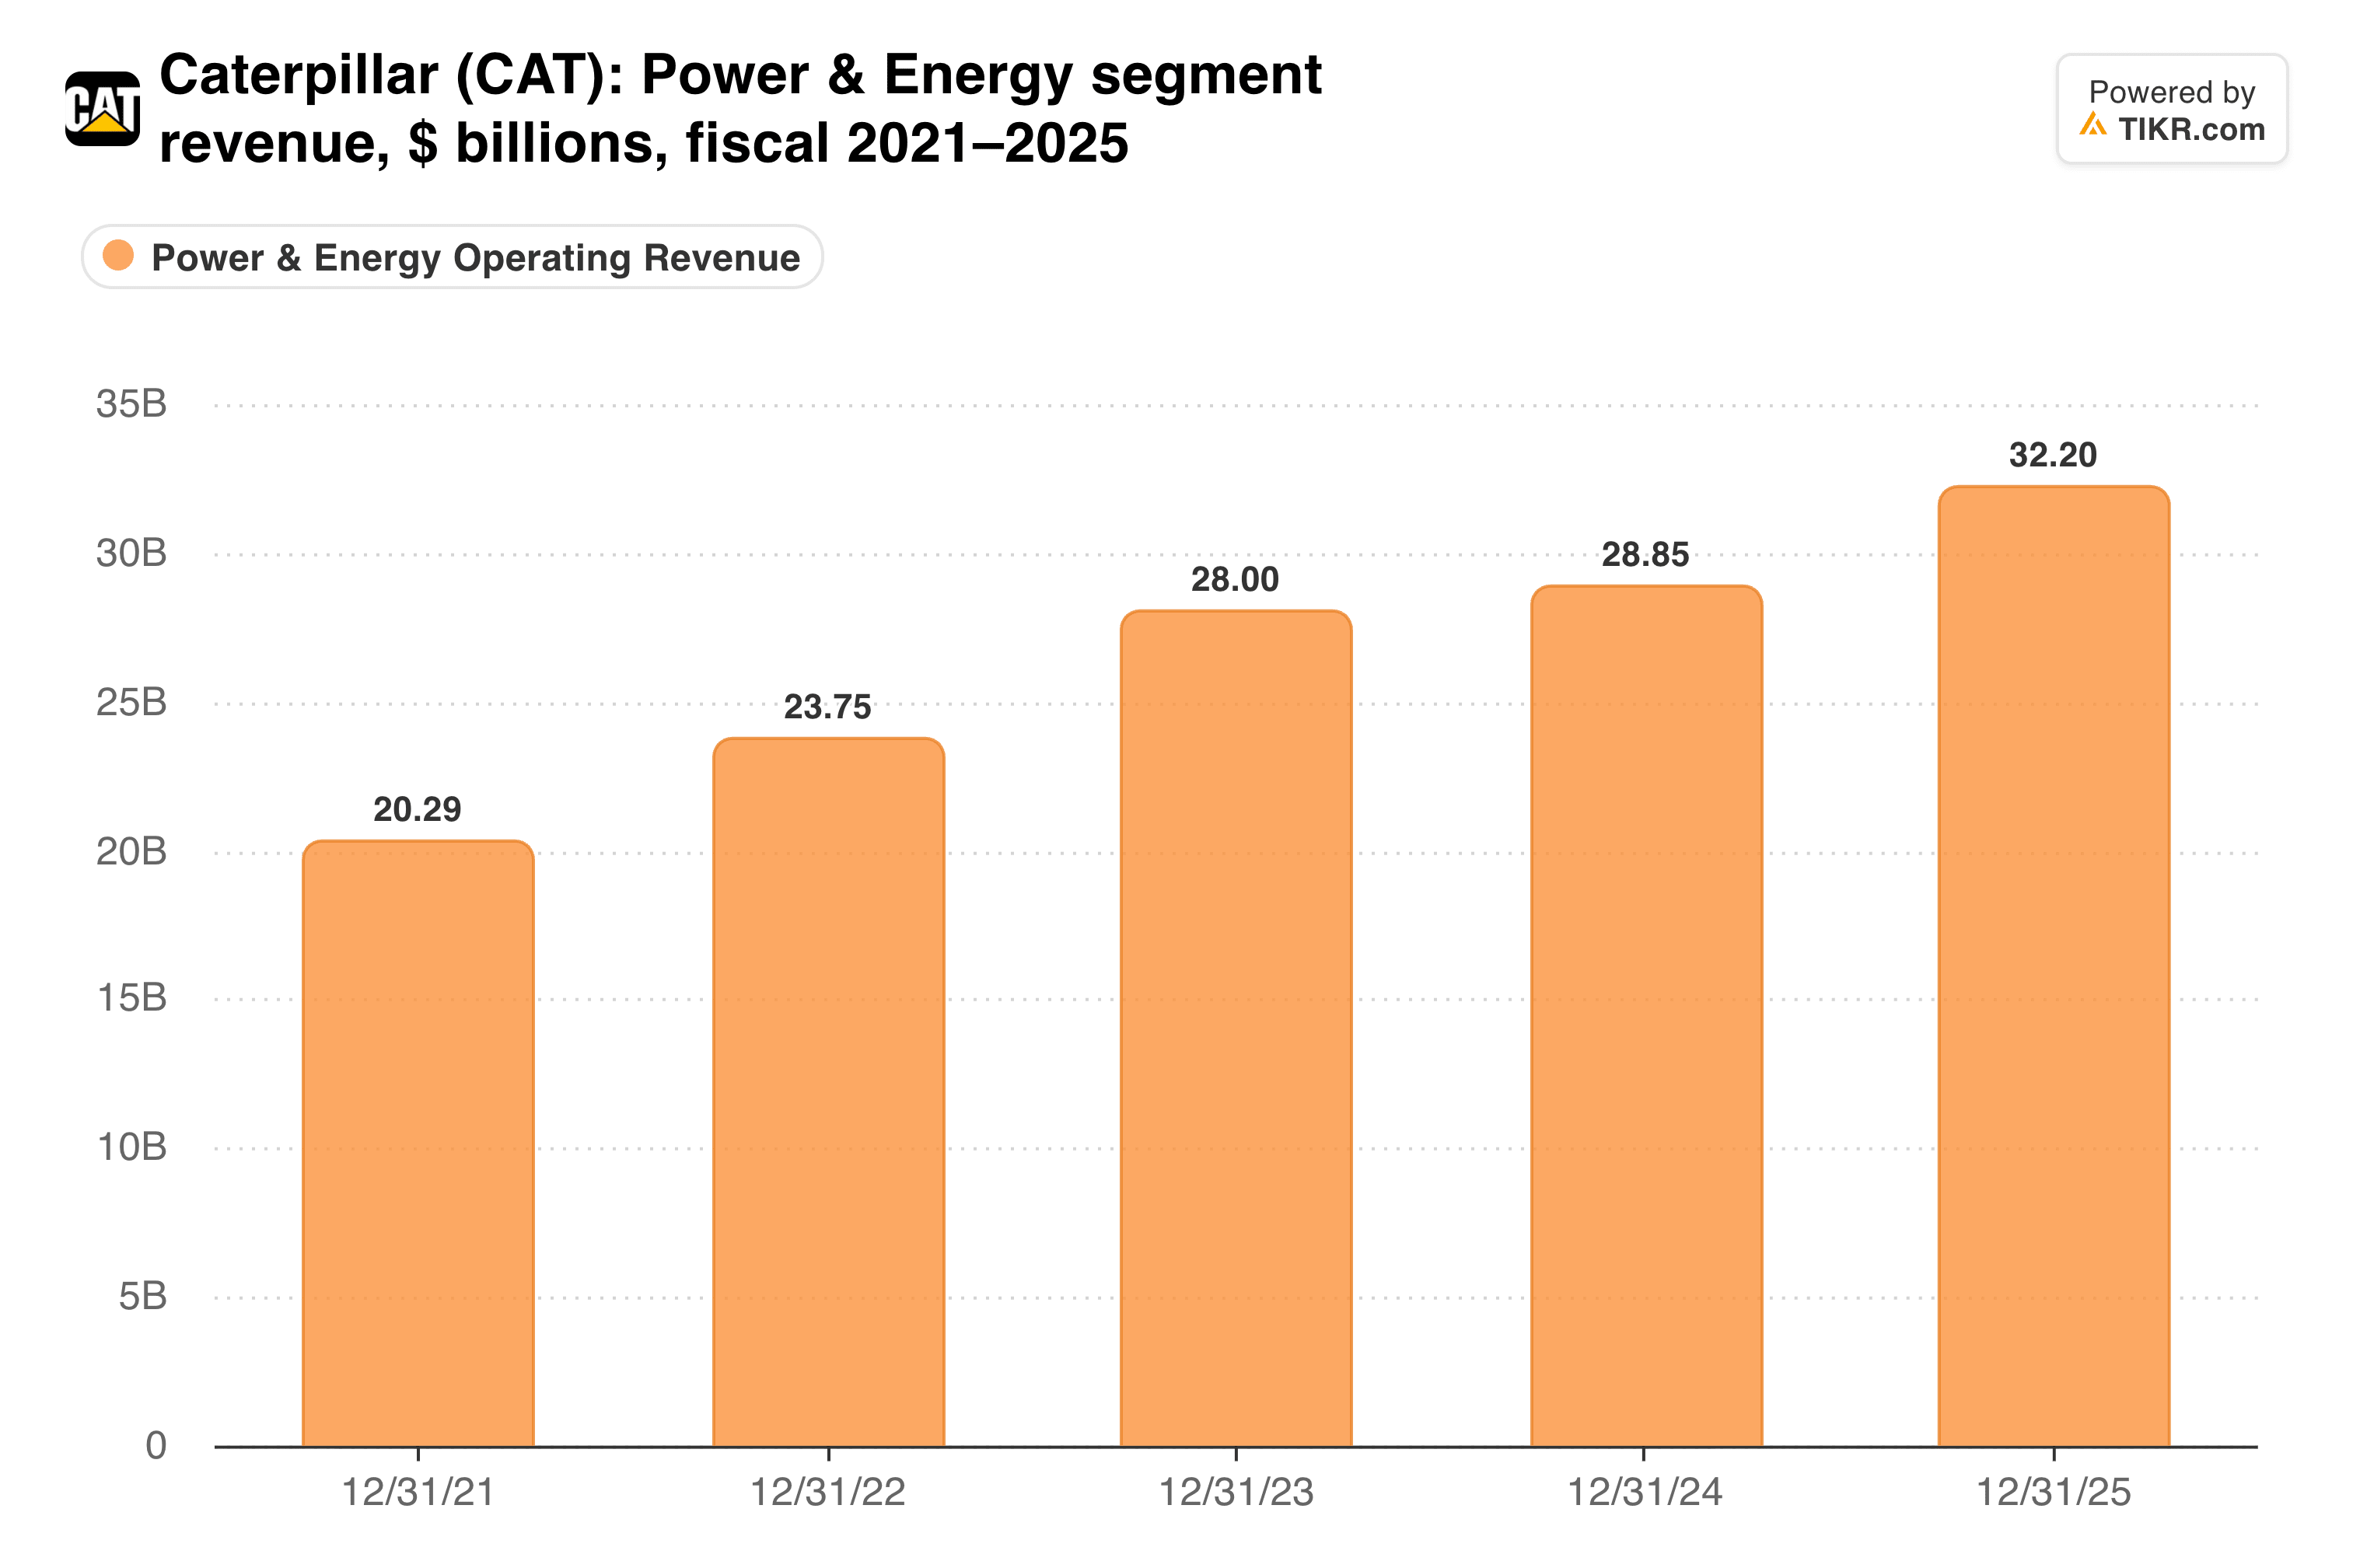
Its 24.4% profit margin is now the highest of Caterpillar’s three main segments, ahead of Construction Industries at 22.9%.
TIKR tracks 29 analysts on Caterpillar. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Caterpillar, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Caterpillar’s Analyst Ratings
Tariffs keep margins near the floor
Costs are the harder part. Caterpillar still expects about $2.2 billion of tariff costs this year, and its adjusted operating margin sits near the bottom of its own target range. Third-quarter operating profit also included $128 million of IEEPA tariff recoveries, a benefit that may not repeat.
Resource Industries shows the squeeze clearly. Its sales rose 15%, but $208 million of higher manufacturing costs, including tariffs, held its margin flat at 13.5%.
The fourth quarter looks softer too. Management expects only moderate sales growth against a strong prior-year quarter, while construction dealers trim inventory by about $1.6 billion.
Earnings kept climbing this year. The multiple went the other way.
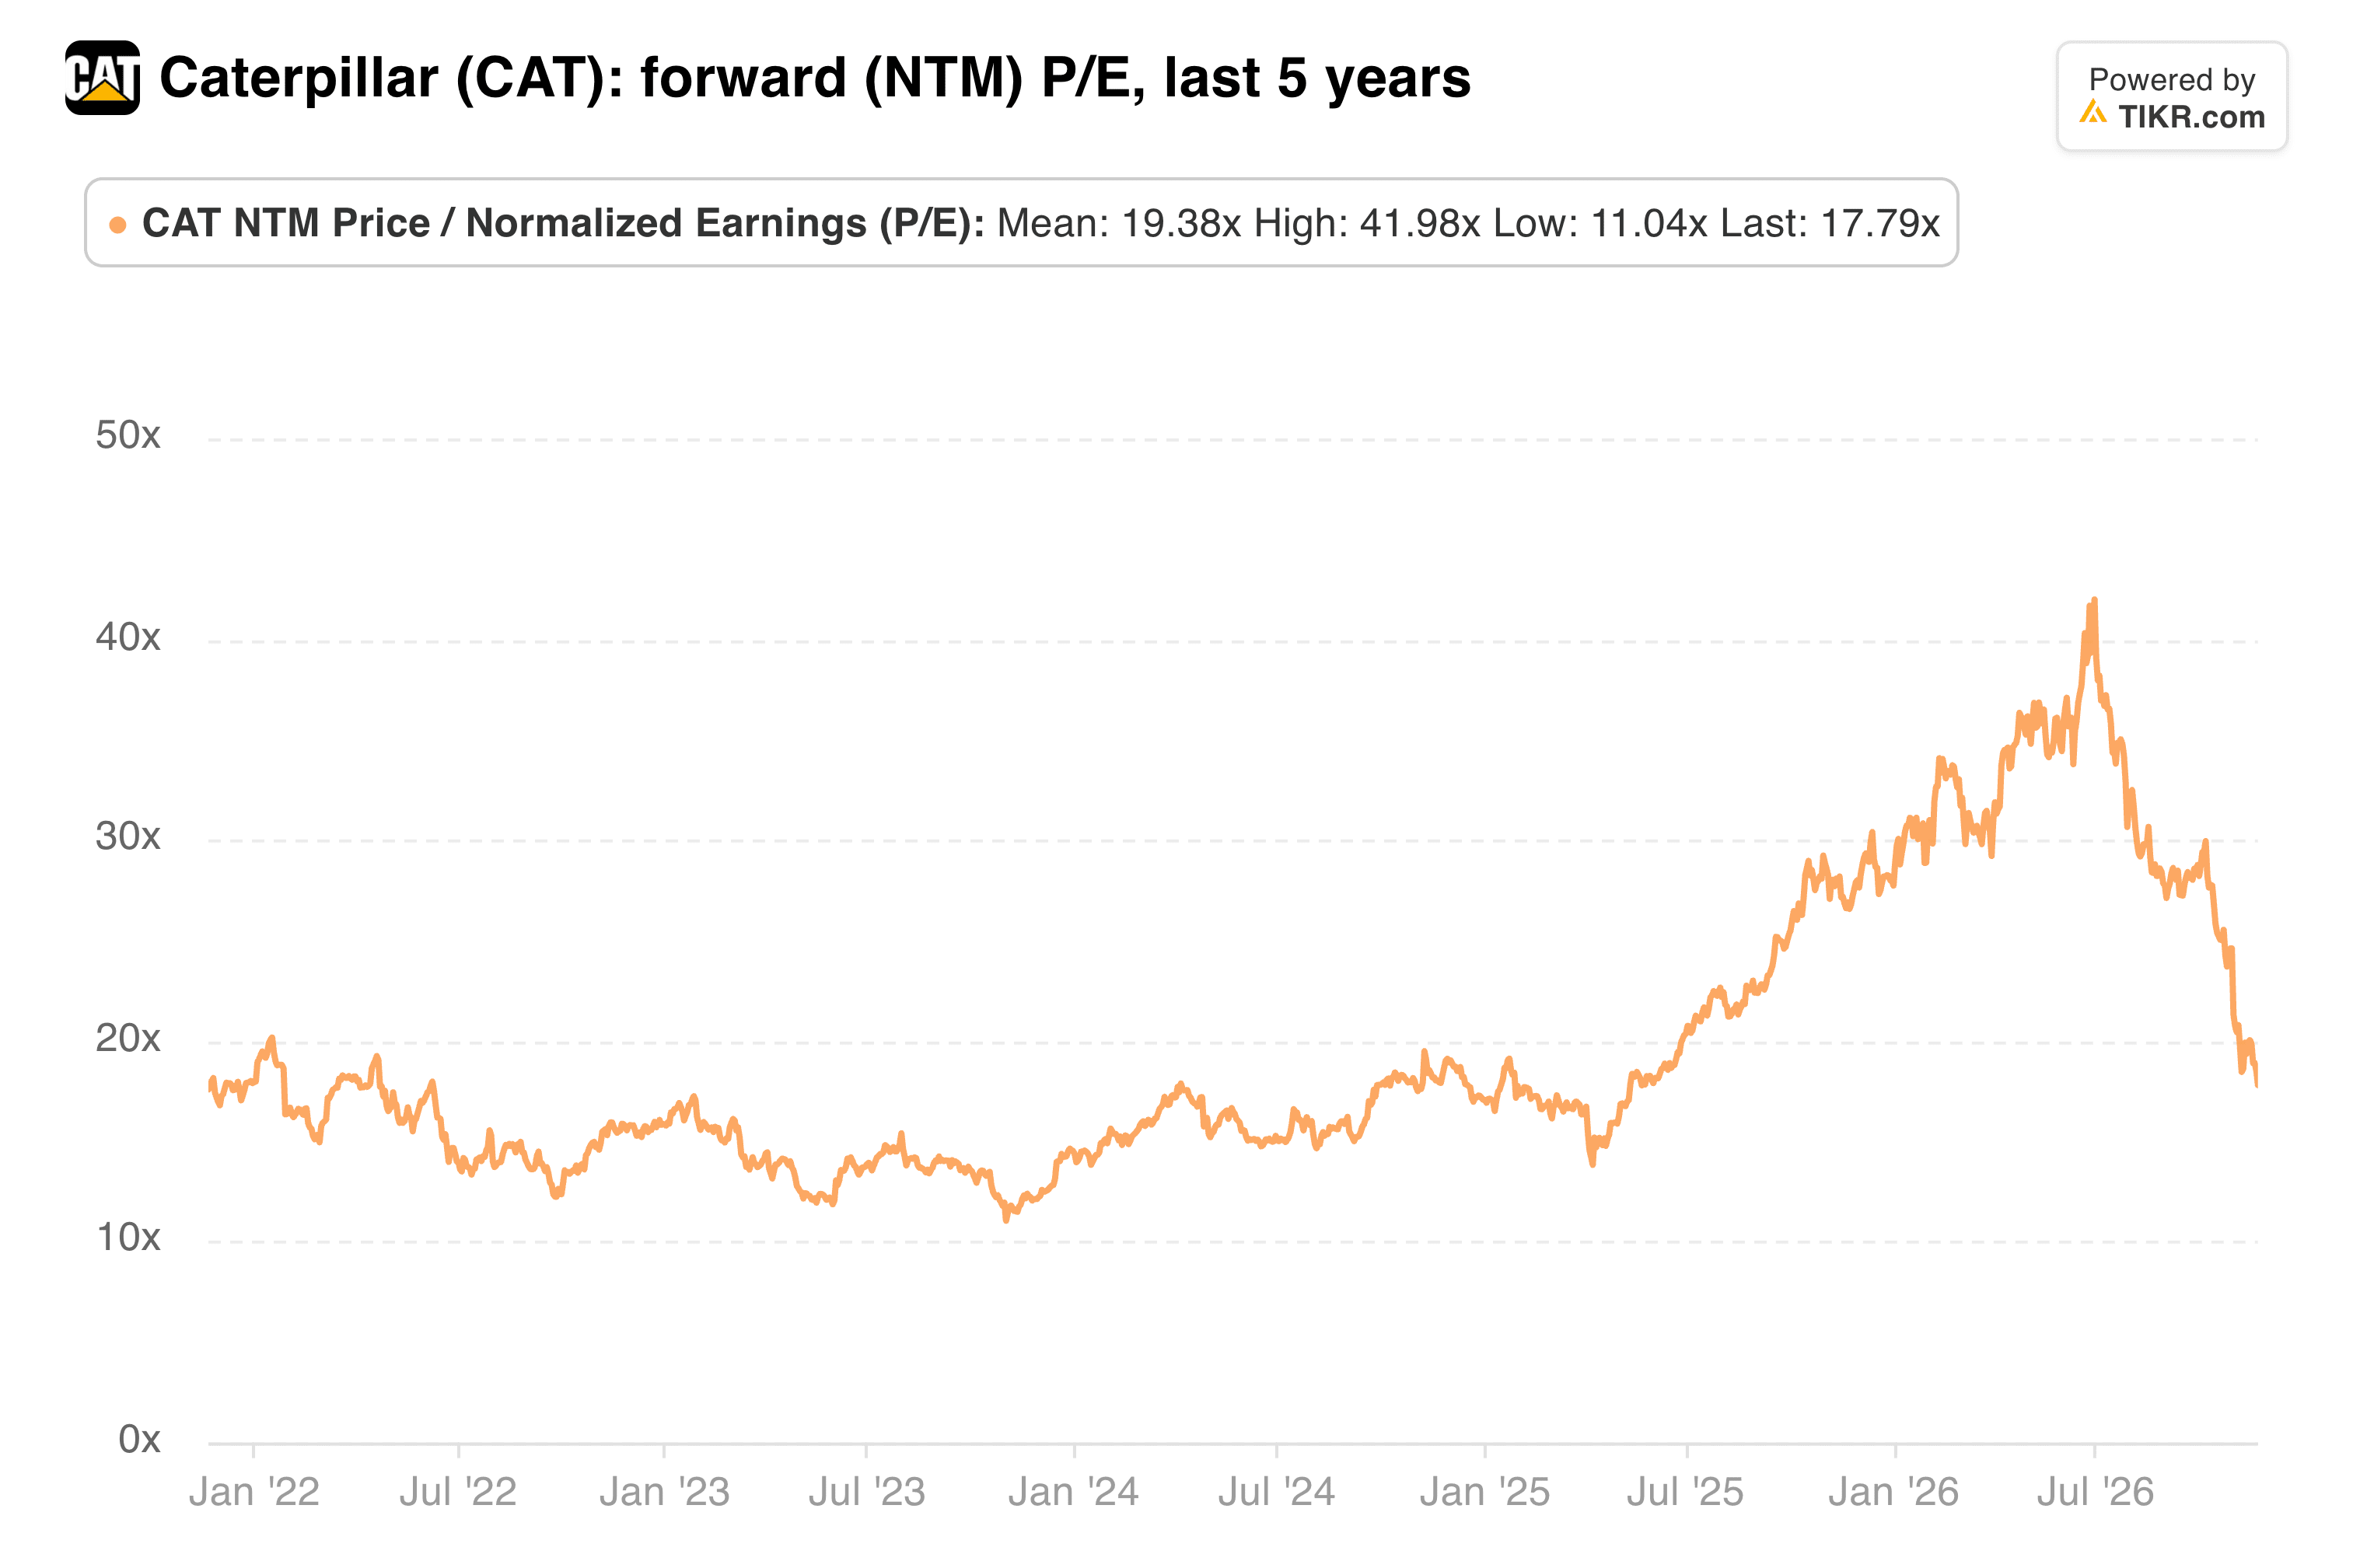
Caterpillar earned $20.36 per share in the first nine months, up from $13.69 a year earlier. Even so, its forward multiple now sits far below its June high.
My take: The selloff priced Caterpillar as if data center demand were already fading, and nothing in the third quarter showed that. I’d still be patient, though. Tariffs and capacity costs could keep margins pinned near the floor into 2027, and a slower data center build would hit the most profitable segment first. At these levels, I think risk and reward look far more balanced than they did in June.
The fourth-quarter report, expected in January, is the next test. It should give the first detailed view of 2027 and show whether that $78.1 billion backlog ships fast enough to lift margins.
So what is Caterpillar stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Caterpillar could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!