

Key Takeaways
- BTIG cut its Salesforce price target to $250 from $300 on Nov. 18 and kept its Buy rating, so the target is still 33% above the share price.
- Salesforce fell 9% on Nov. 17 after tech outages and a data breach hit software stocks ahead of Anthropic’s IPO, adding to a year of worries about growth, debt and AI.
- At $250, Salesforce would trade at about 14x the earnings analysts expect for the year ending January 2029, close to its multiple today and about half its five-year average.
- BTIG’s lower target looks too cautious, and the third-quarter report on Dec. 2 will show whether organic growth is picking up.
Salesforce (CRM) sits 30% below its December high, and one of its bulls just lowered the bar. BTIG cut its price target to $250 from $300 on Nov. 18 and kept its Buy rating. That’s still 33% above today’s $188.
Slow growth, more debt and a rough week
Salesforce’s revenue rose 11% to $11.3 billion in its second quarter, ended July 31, but $456 million of that came from Informatica. Without it, revenue grew 6%. Chief Financial and Operating Officer Robin Washington said the company is “on track for second-half organic revenue reacceleration.”
Salesforce’s debt rose to $39.5 billion by July 31, from $14.5 billion at the end of January, to pay for a $25 billion buyback. S&P cut its credit rating to A from A+ on Nov. 4, citing the deals and shareholder returns.
On Nov. 17, the stock fell 9% as a run of tech outages and a data breach at Optimizely that named Salesforce hit software stocks ahead of Anthropic’s IPO.
TIKR tracks 56 analysts on Salesforce. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Salesforce, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Salesforce’s Analyst Ratings
BTIG is still a buyer
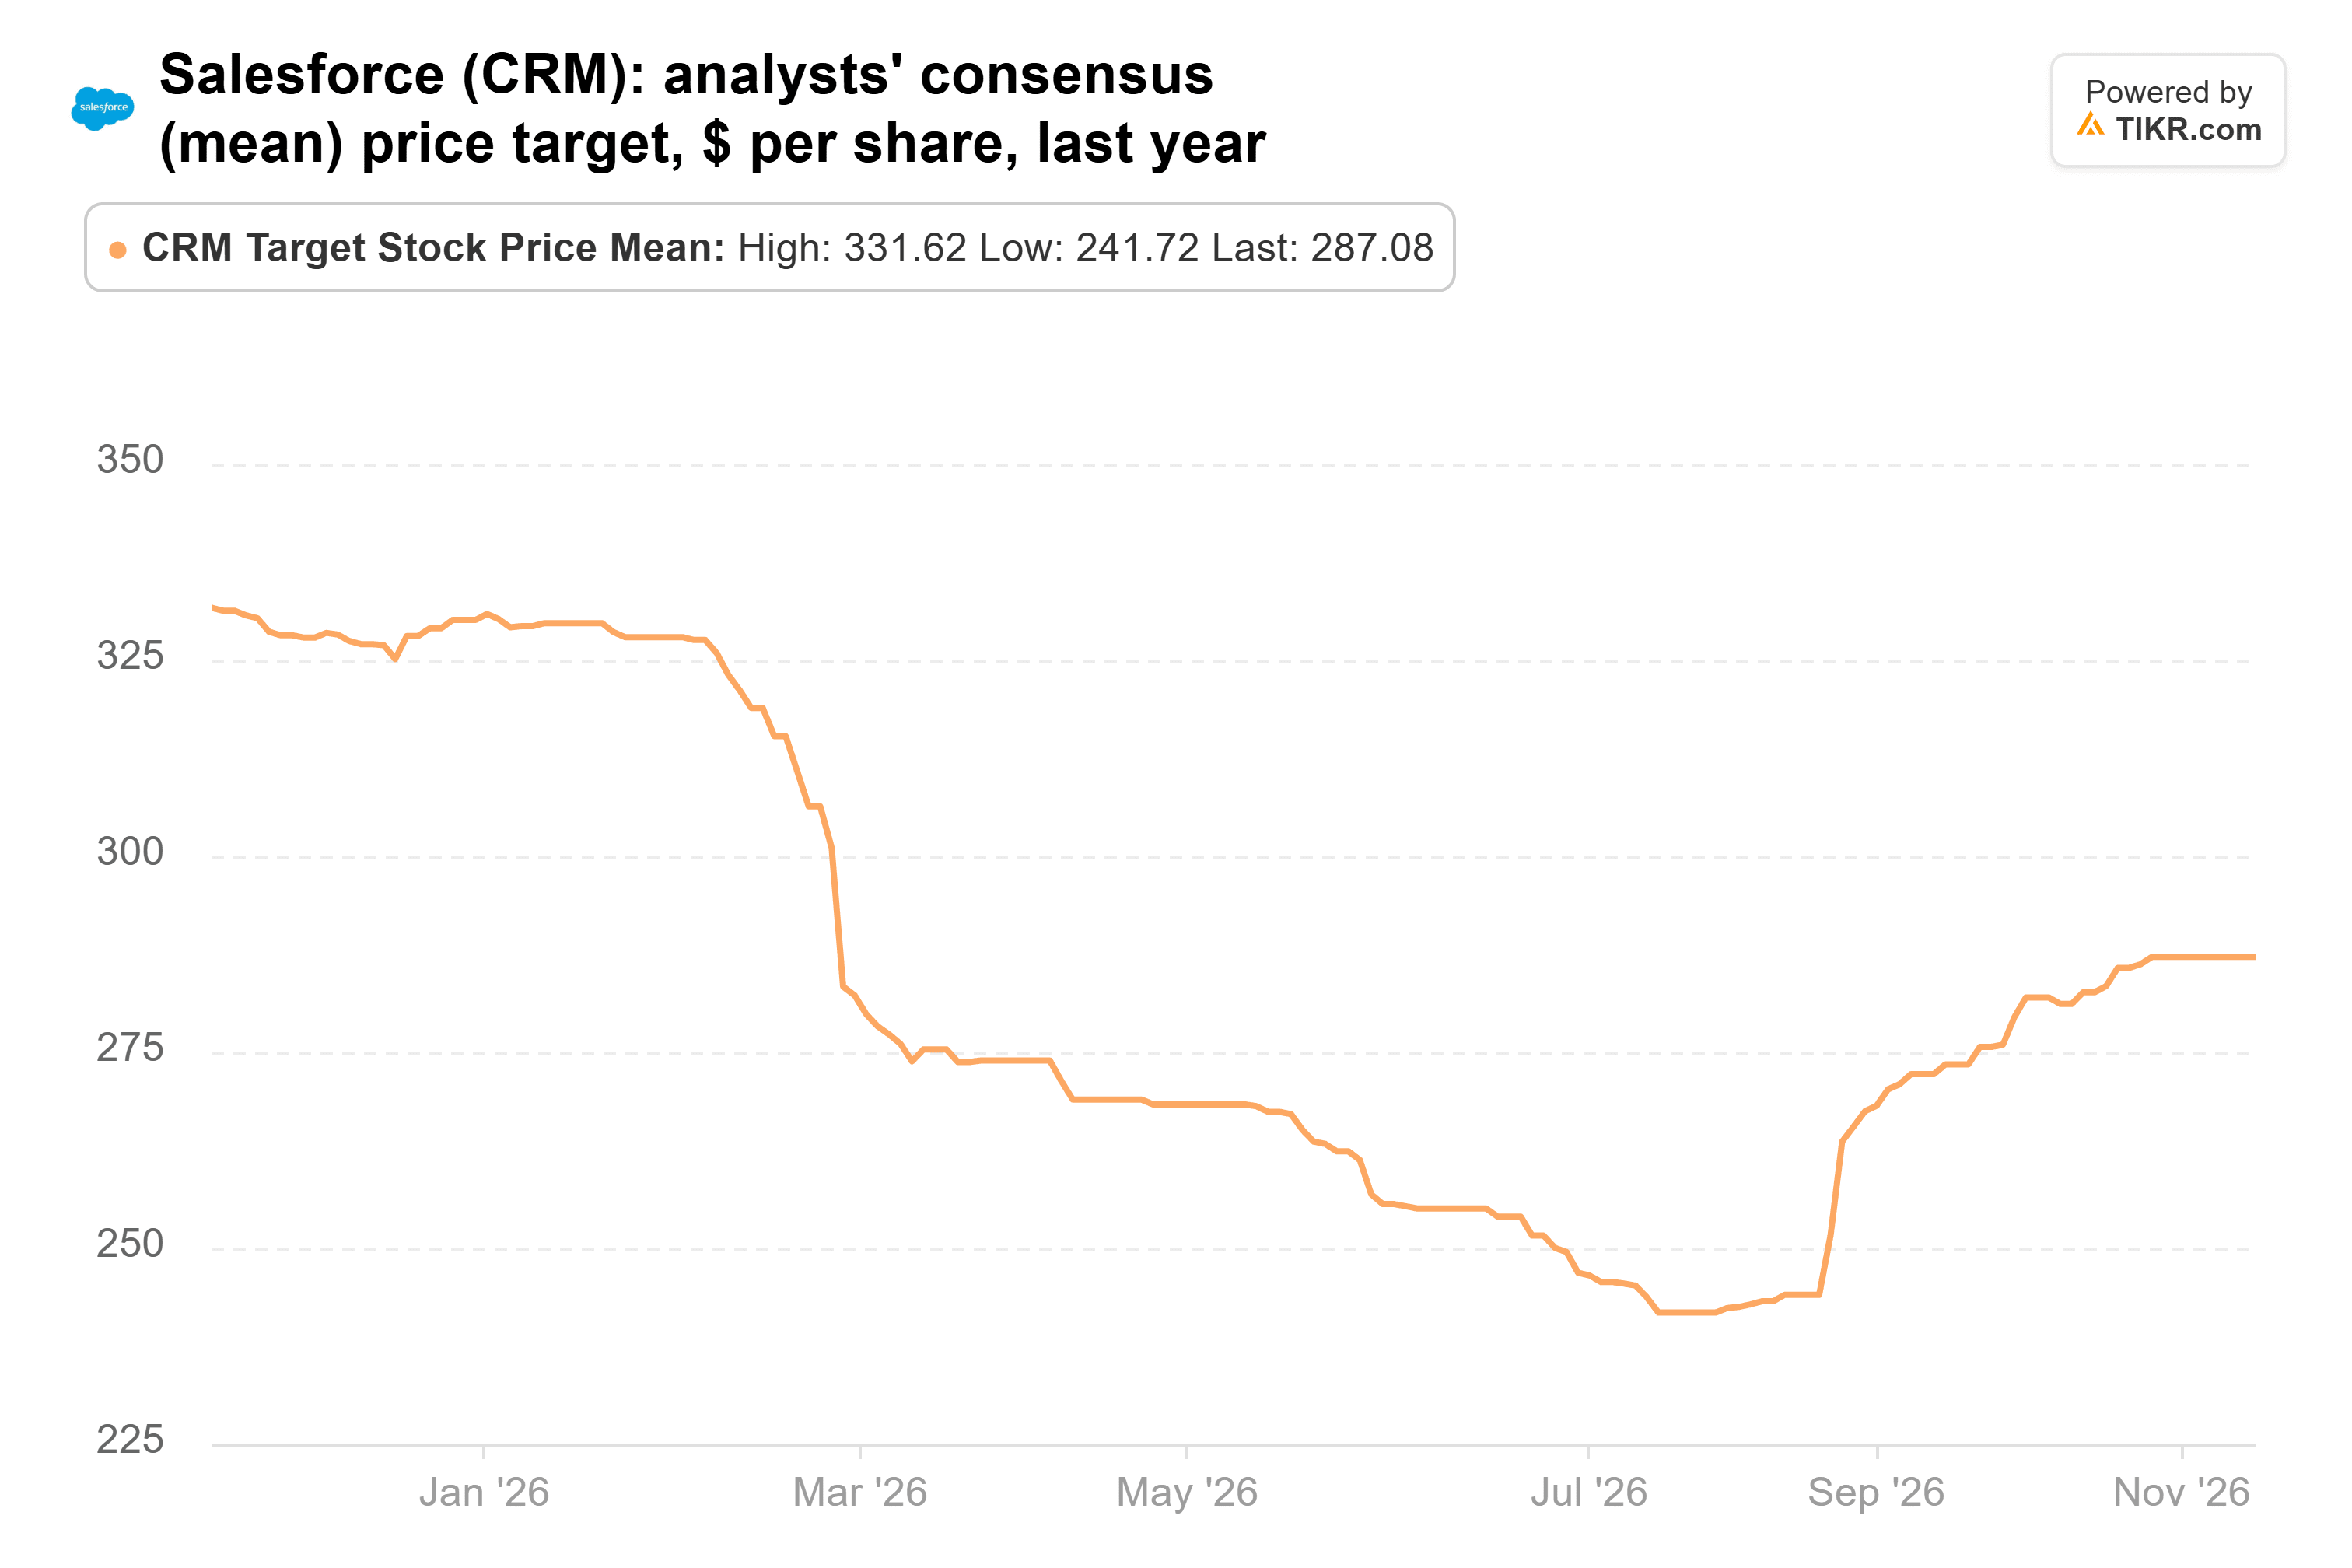
BTIG analyst Allan Verkhovski made the cut in an update across application software. His $250 is 13% below the $287 consensus target of the 56 analysts who cover Salesforce. The consensus target started the past year at $332, bottomed at $242 in July, and has climbed back since:
Does $250 add up?
Analysts expect normalized EPS of $16.75 for the fiscal year ending January 2027, a touch above Salesforce’s own guide of $16.67-$16.71. For the year ending January 2029, they expect $18.46:
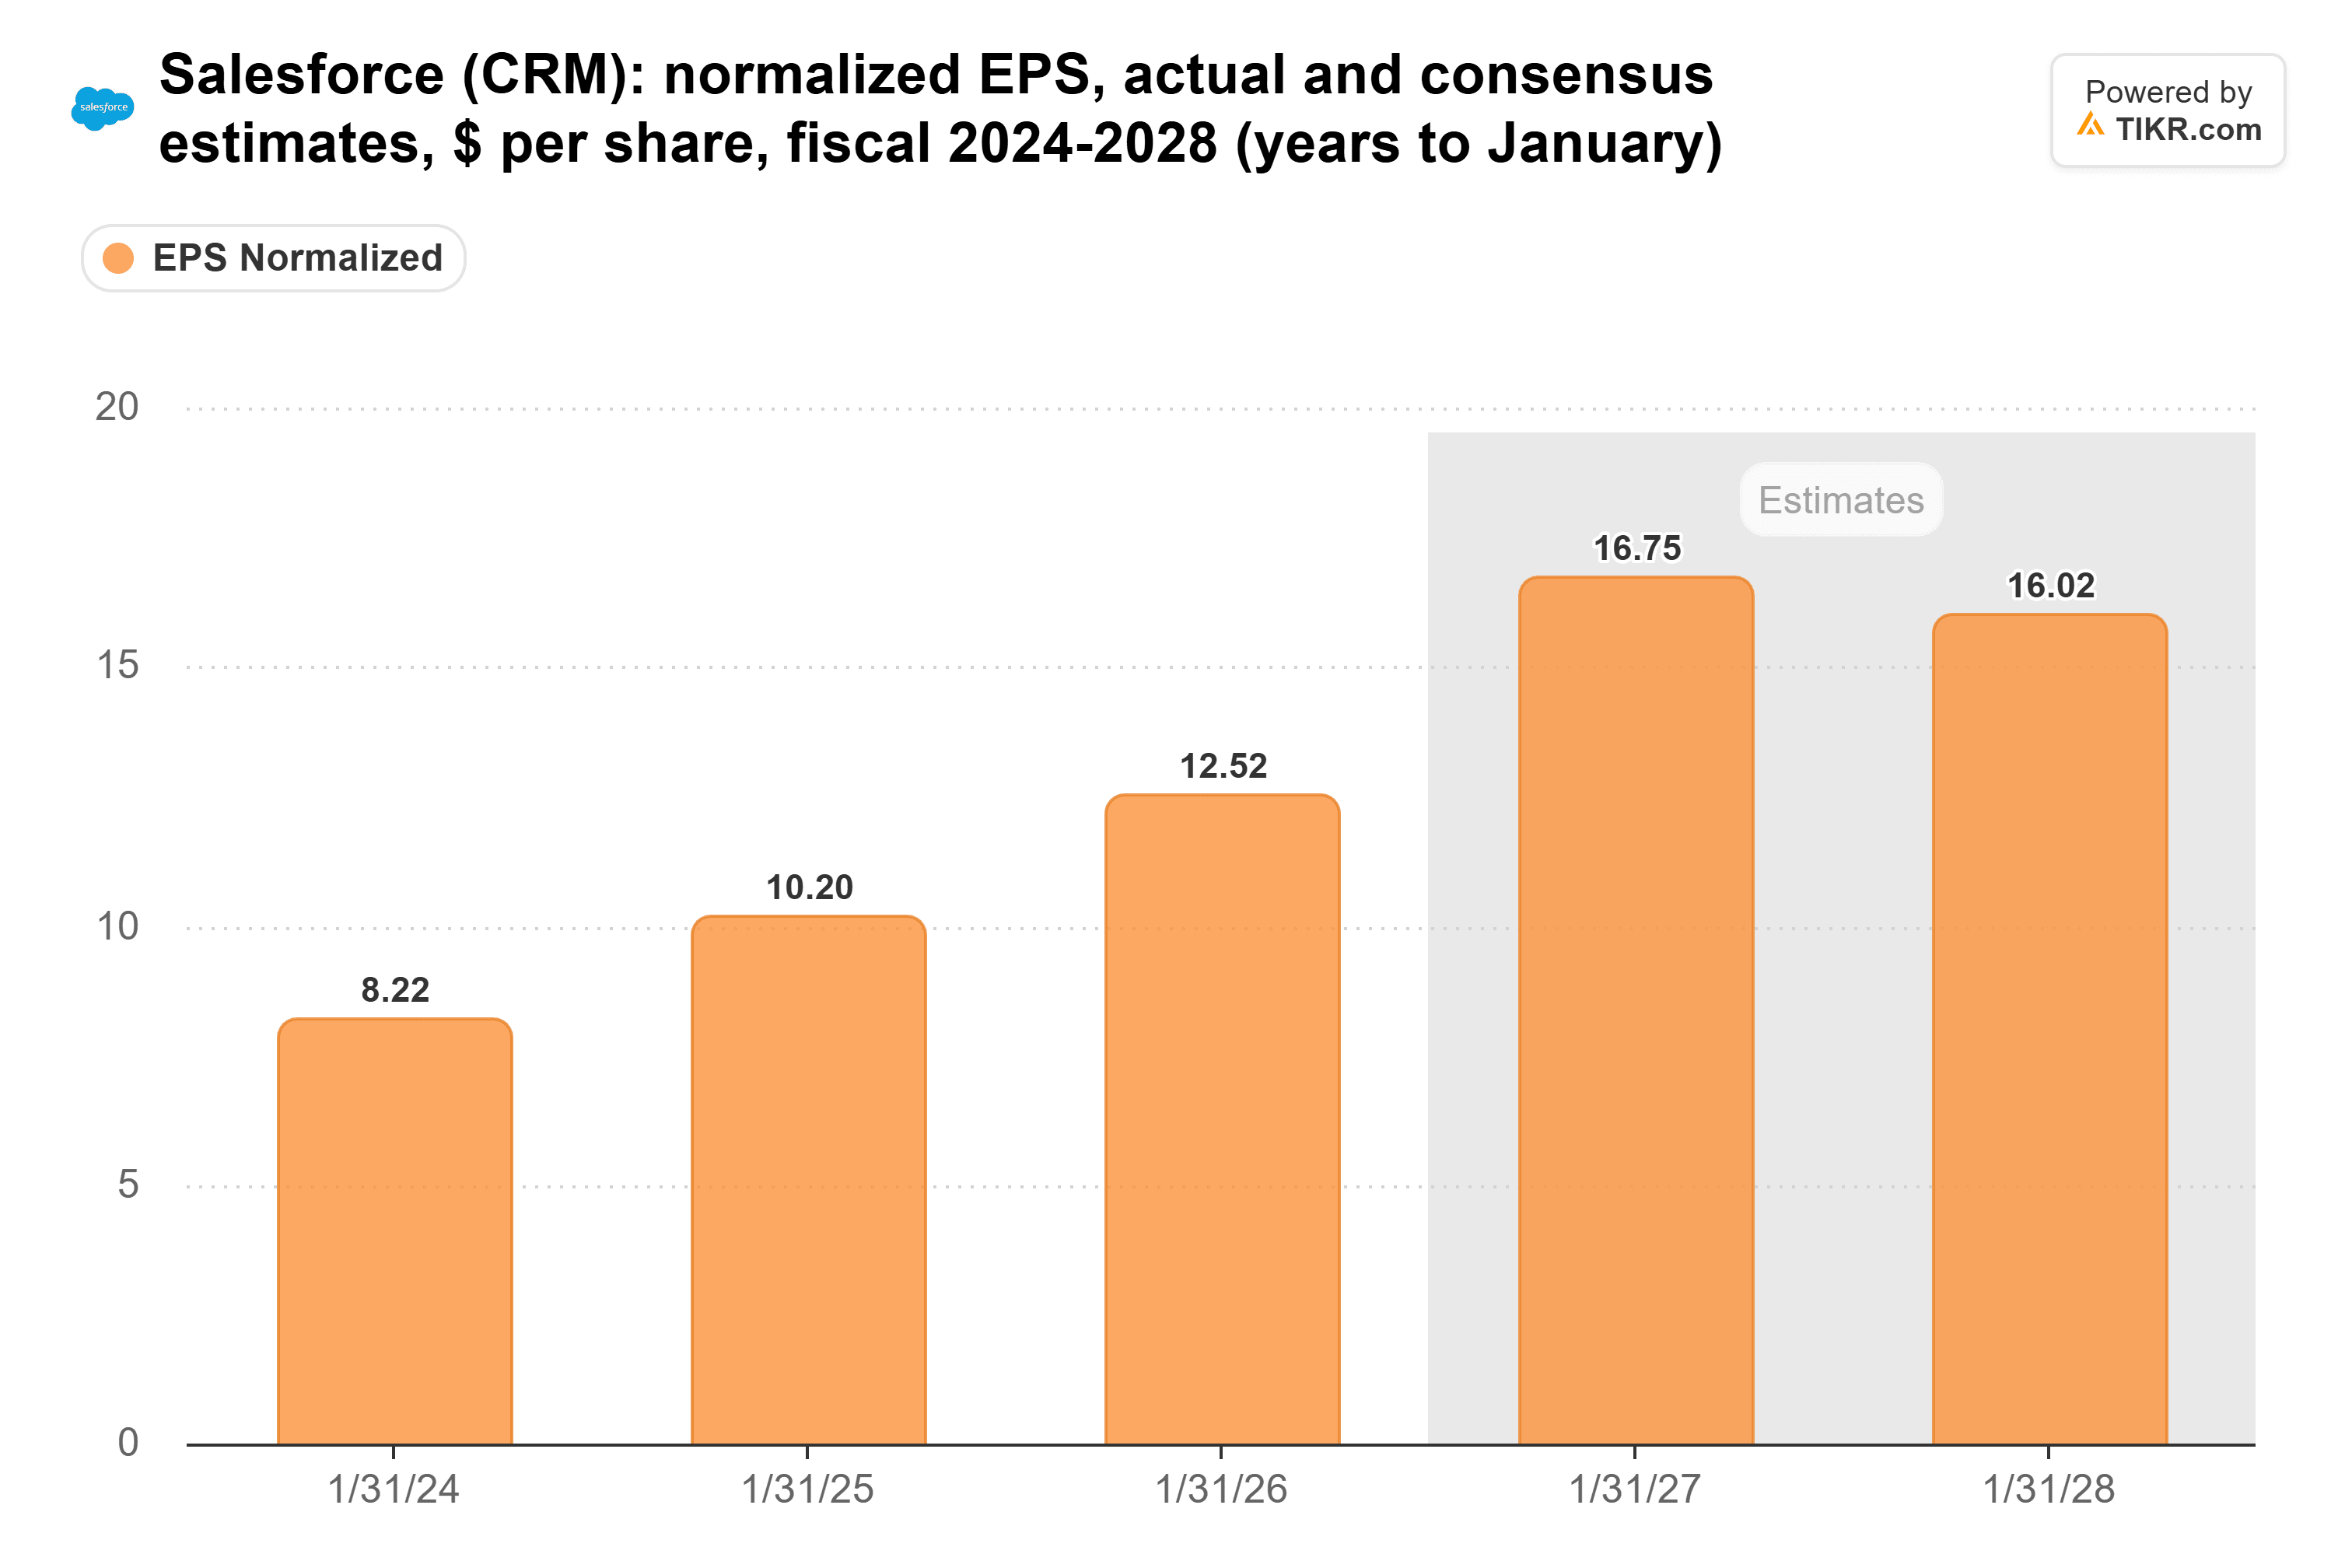
The dip in between comes from this year’s gains on Salesforce’s Anthropic stake, which added $2.98 a share to non-GAAP EPS in the first half alone. And the estimate for the year in between has risen to $16.02 from $15.52 in three months.
Salesforce trades at 13x forward earnings. That’s near June’s five-year low of 11x and well under its 27x average:
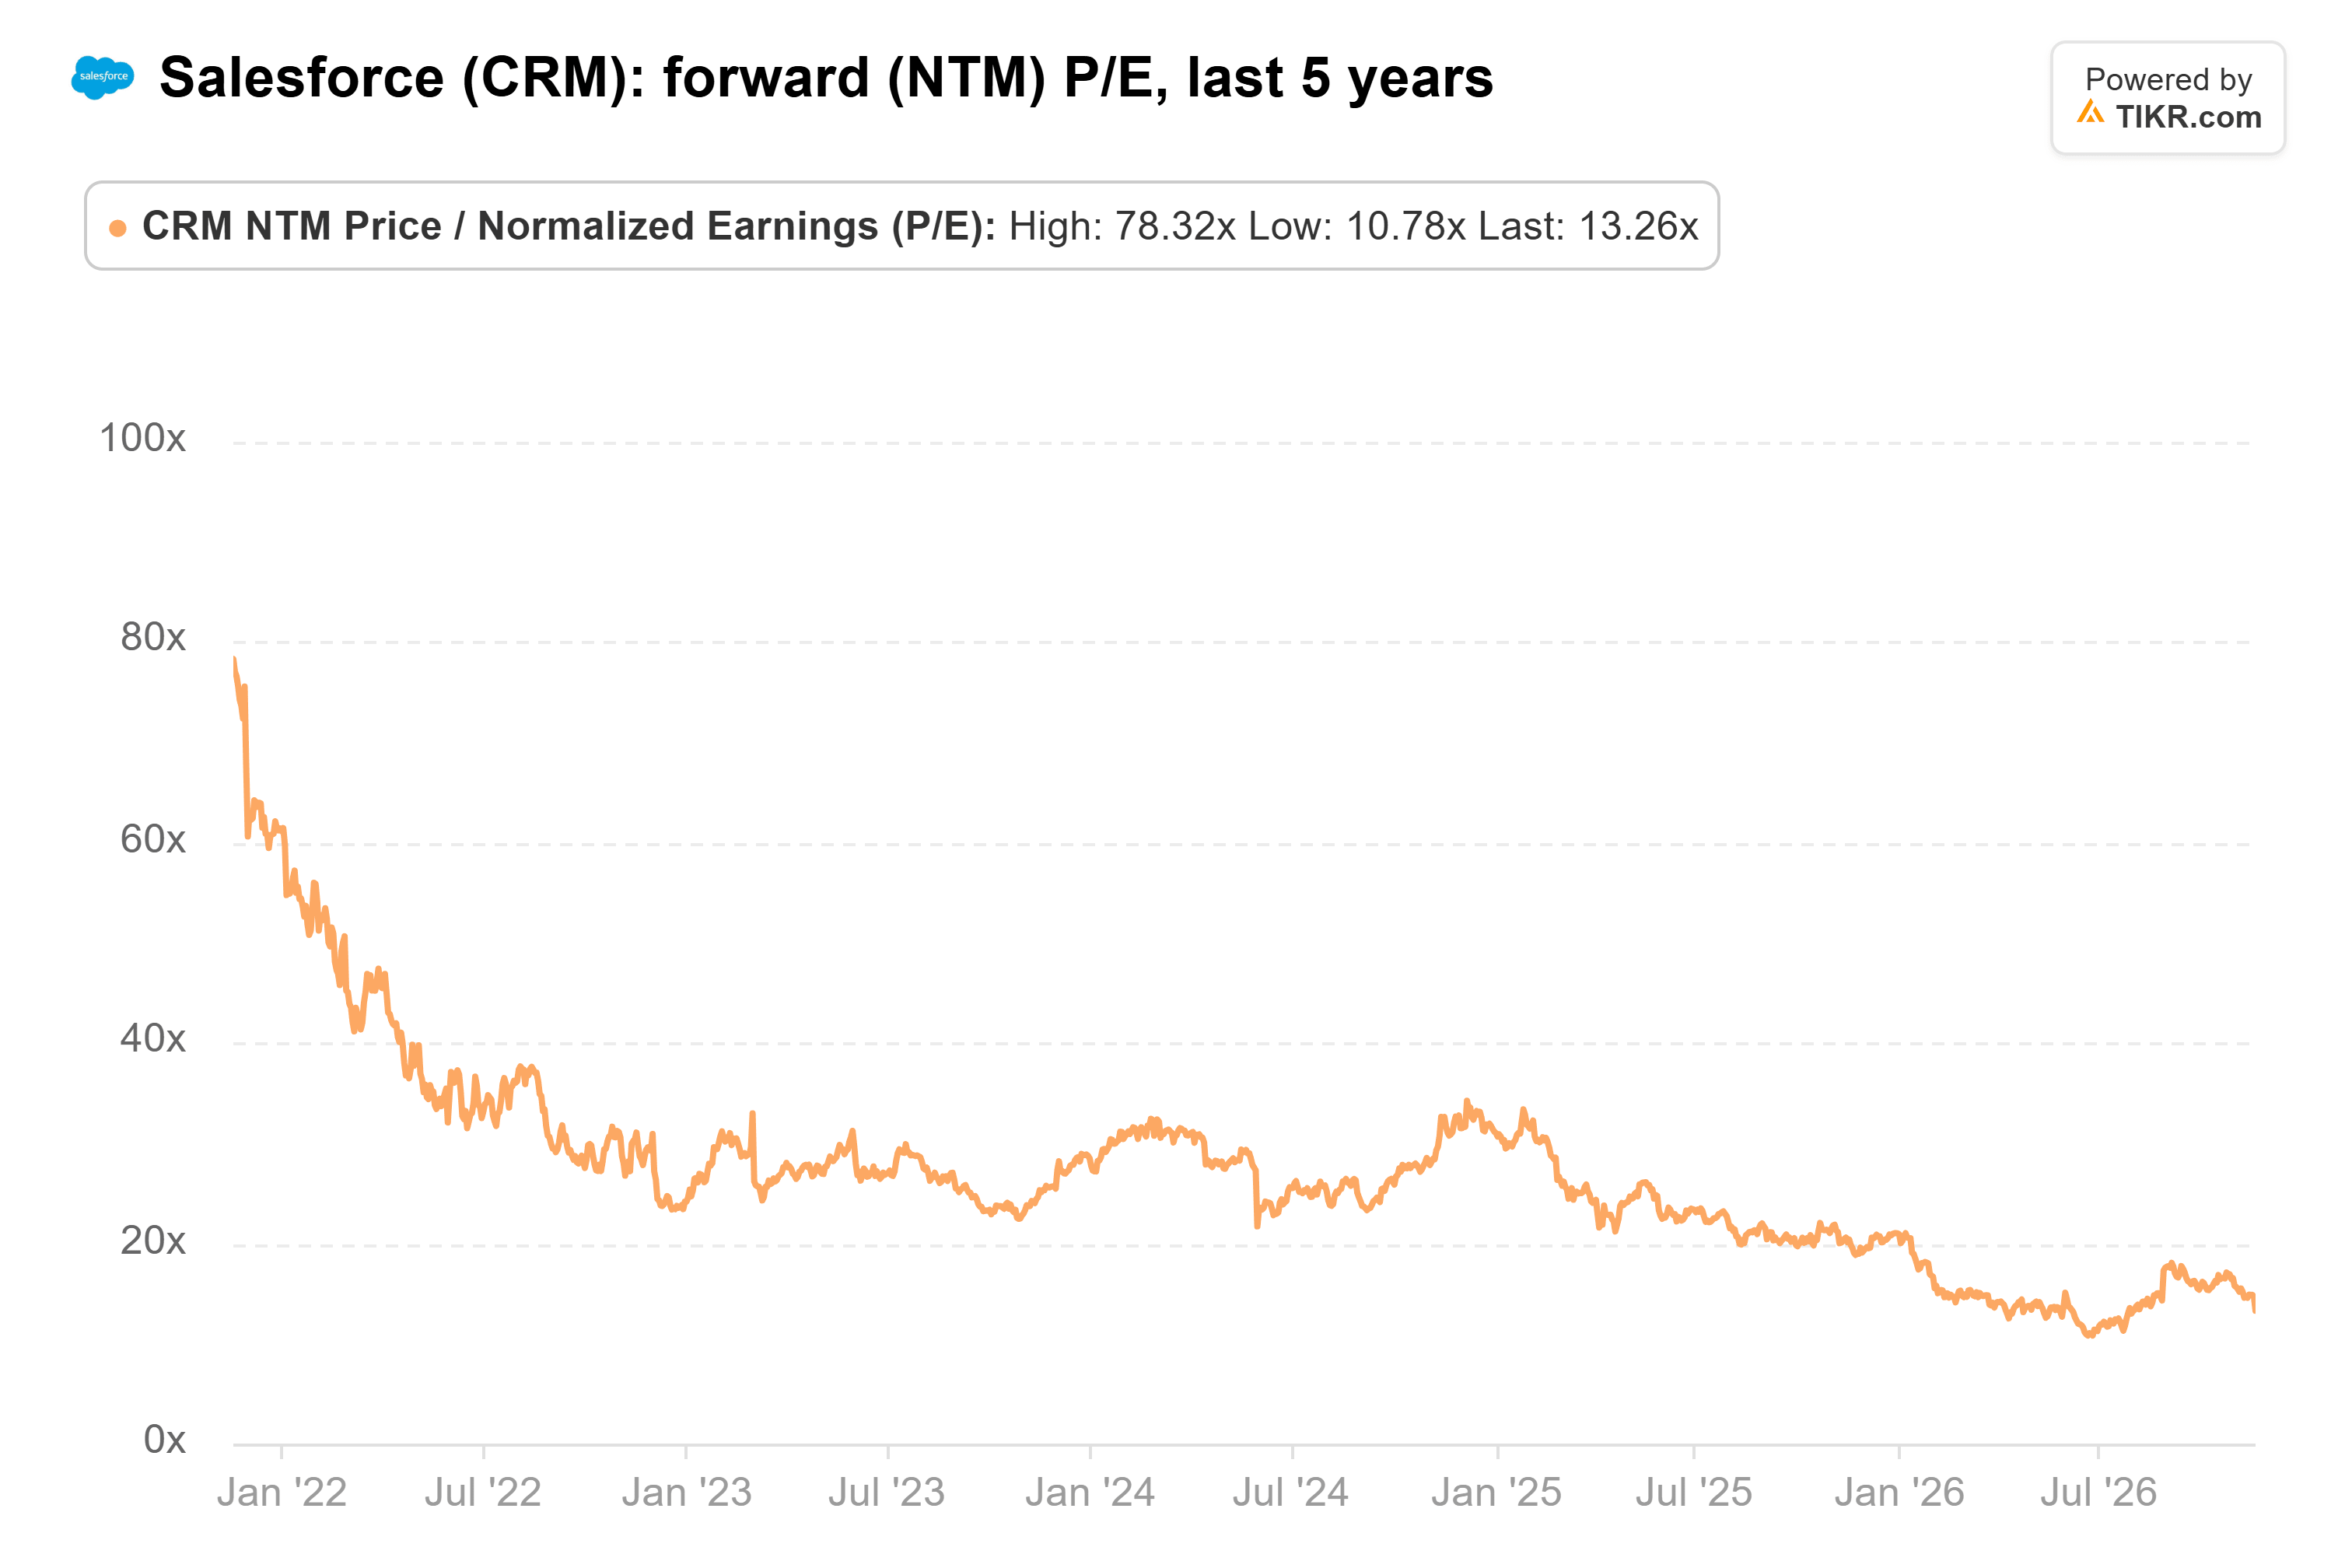
BTIG hasn’t shown its math, but by mine, $250 is about 14x the earnings analysts expect for the year ending January 2029, roughly today’s multiple. Nearly all of the upside comes from earnings growing 26% from the next twelve months’ $14.67, and the multiple adds about 2%.
BTIG got too careful
The main risk is AI. Agents could let customers do their work outside Salesforce and pay for fewer seats, and the company now has far more debt to carry if that happens.
Frankly, I think BTIG cut too far: its target needs no re-rating at all, so any recovery in the multiple would put the stock well above $250.
Salesforce reports third-quarter results on Dec. 2. Revenue at or above the $11.42 billion low end of guidance, with organic growth above the second quarter’s 6%, would back the bulls.
So what is Salesforce stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Salesforce could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



