Key Takeaways
- Bill Ackman said on CNBC’s Squawk Pod that Pershing Square bought Meta at a huge discount after it announced big capex spending, and that it had bought Microsoft and Amazon the same way when their stocks dropped.
- Ackman says analysts put the cost of the AI build-out into their models but give no credit for faster growth, and he sees Muse as Meta’s payoff.
- Since the end of September 2025, analysts have raised their 2027 revenue estimate for Meta 19% and their 2027 earnings estimate only 1.4%, while consensus has free cash flow negative through 2028.
- Meta trades at 18x forward earnings, below its five-year average of 21x, and the next test is its fourth-quarter call in late January.
Bill Ackman says Wall Street’s models for Meta Platforms (META) are missing something big:
They count every dollar of its AI build-out and give it no credit for faster growth.
On Election Day’s episode of CNBC’s Squawk Pod, Ackman explained how Pershing Square uses the market’s big swings. It bought Microsoft (MSFT) when investors worried about its capex, and Amazon (AMZN) when tariffs were announced. And then:
“When Meta announced big capex spend, we were able to buy Meta at a huge discount.”
Asked whether he likes all three spending so heavily, Ackman said yes. They can afford it, he said, and they’re seeing strong demand and high returns on what they invest. Then he took aim at the analysts:
“The analysts are kind of factoring into the model the capex associated with the build-out, but not any meaningful change in the growth rate. And I think that’s just wrong.”
That’s a contrarian call: Meta’s stock fell 15% in October.
TIKR tracks 62 analysts on Meta Platforms. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Meta Platforms, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Meta Platforms’ Analyst Ratings
Analysts have growth settling near 20%
Meta’s revenue grew 22% in 2025, to $201 billion. Consensus has it jumping 28% this year, then growing about 20% a year in 2027 and 2028:
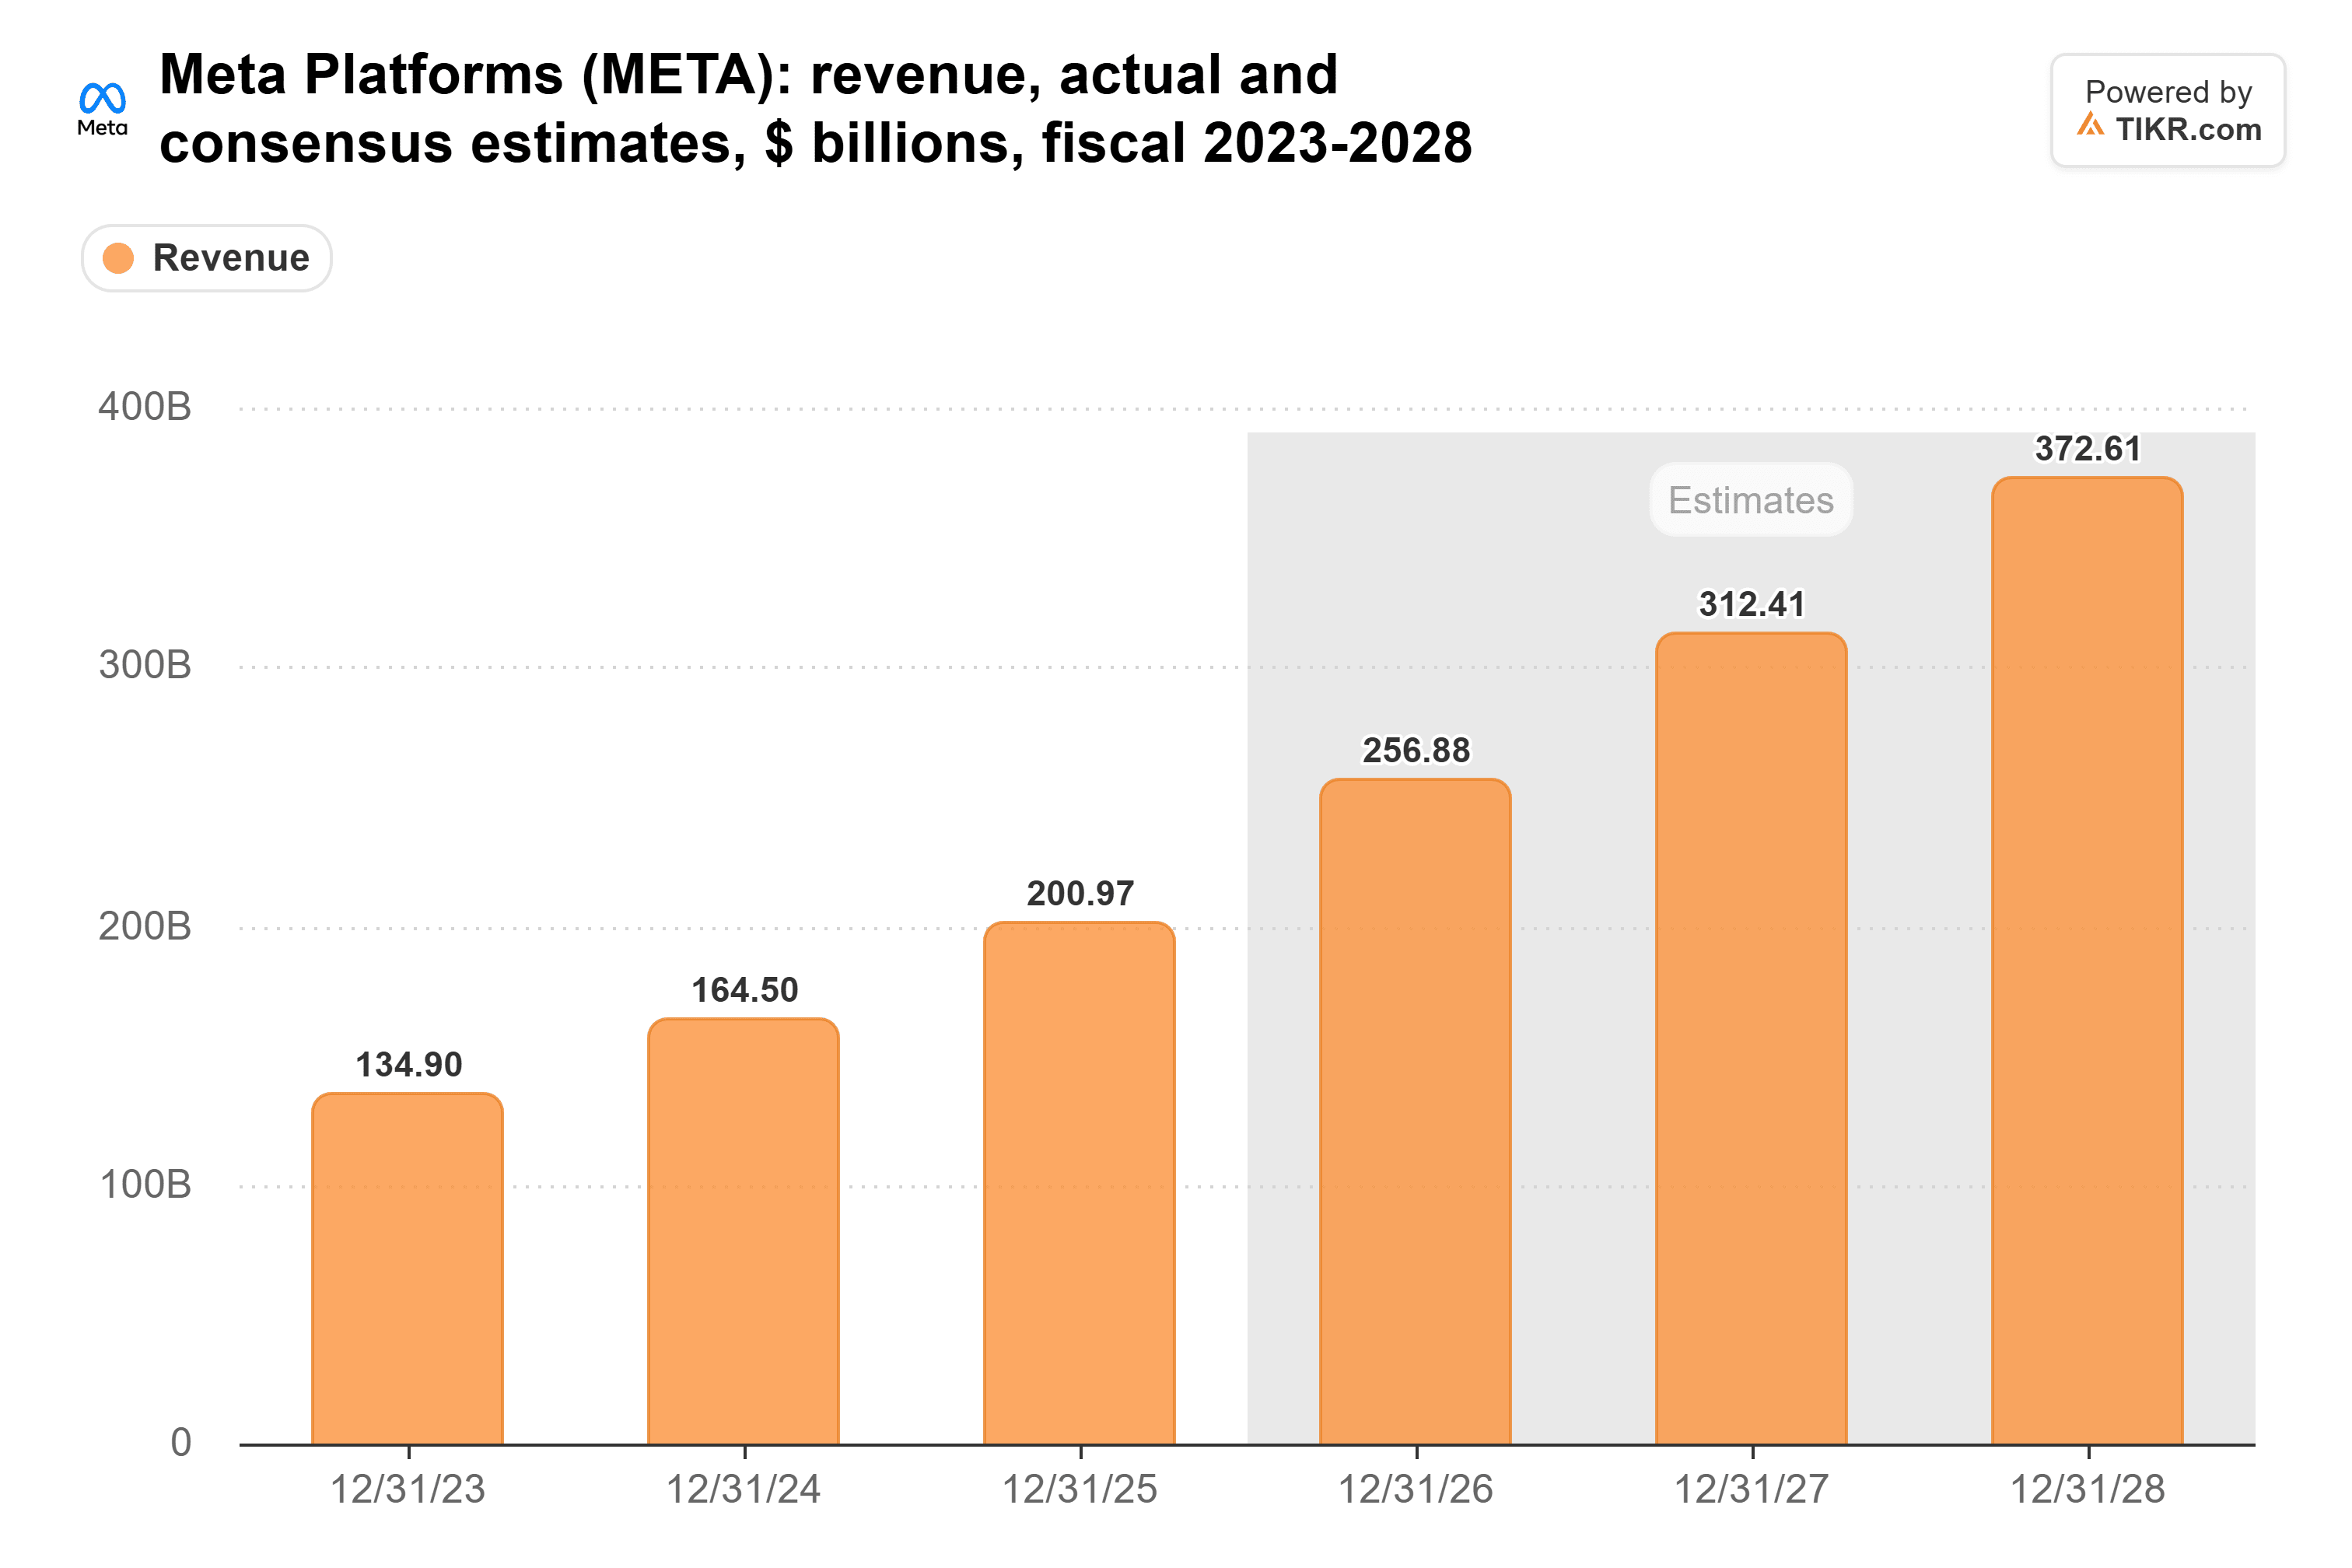
So once this year is done, the models have Meta growing at about its 2025 pace, with the full cost of the build-out on top.
Analysts have been raising their numbers. Since the end of September 2025, they’ve lifted their 2027 revenue estimate 19%, and their 2027 earnings estimate just 1.4%. In their models, nearly all the extra sales go to costs.
The bill is already in the model
And those costs are huge. Meta’s capital spending nearly doubled in 2025, to $69.7 billion:
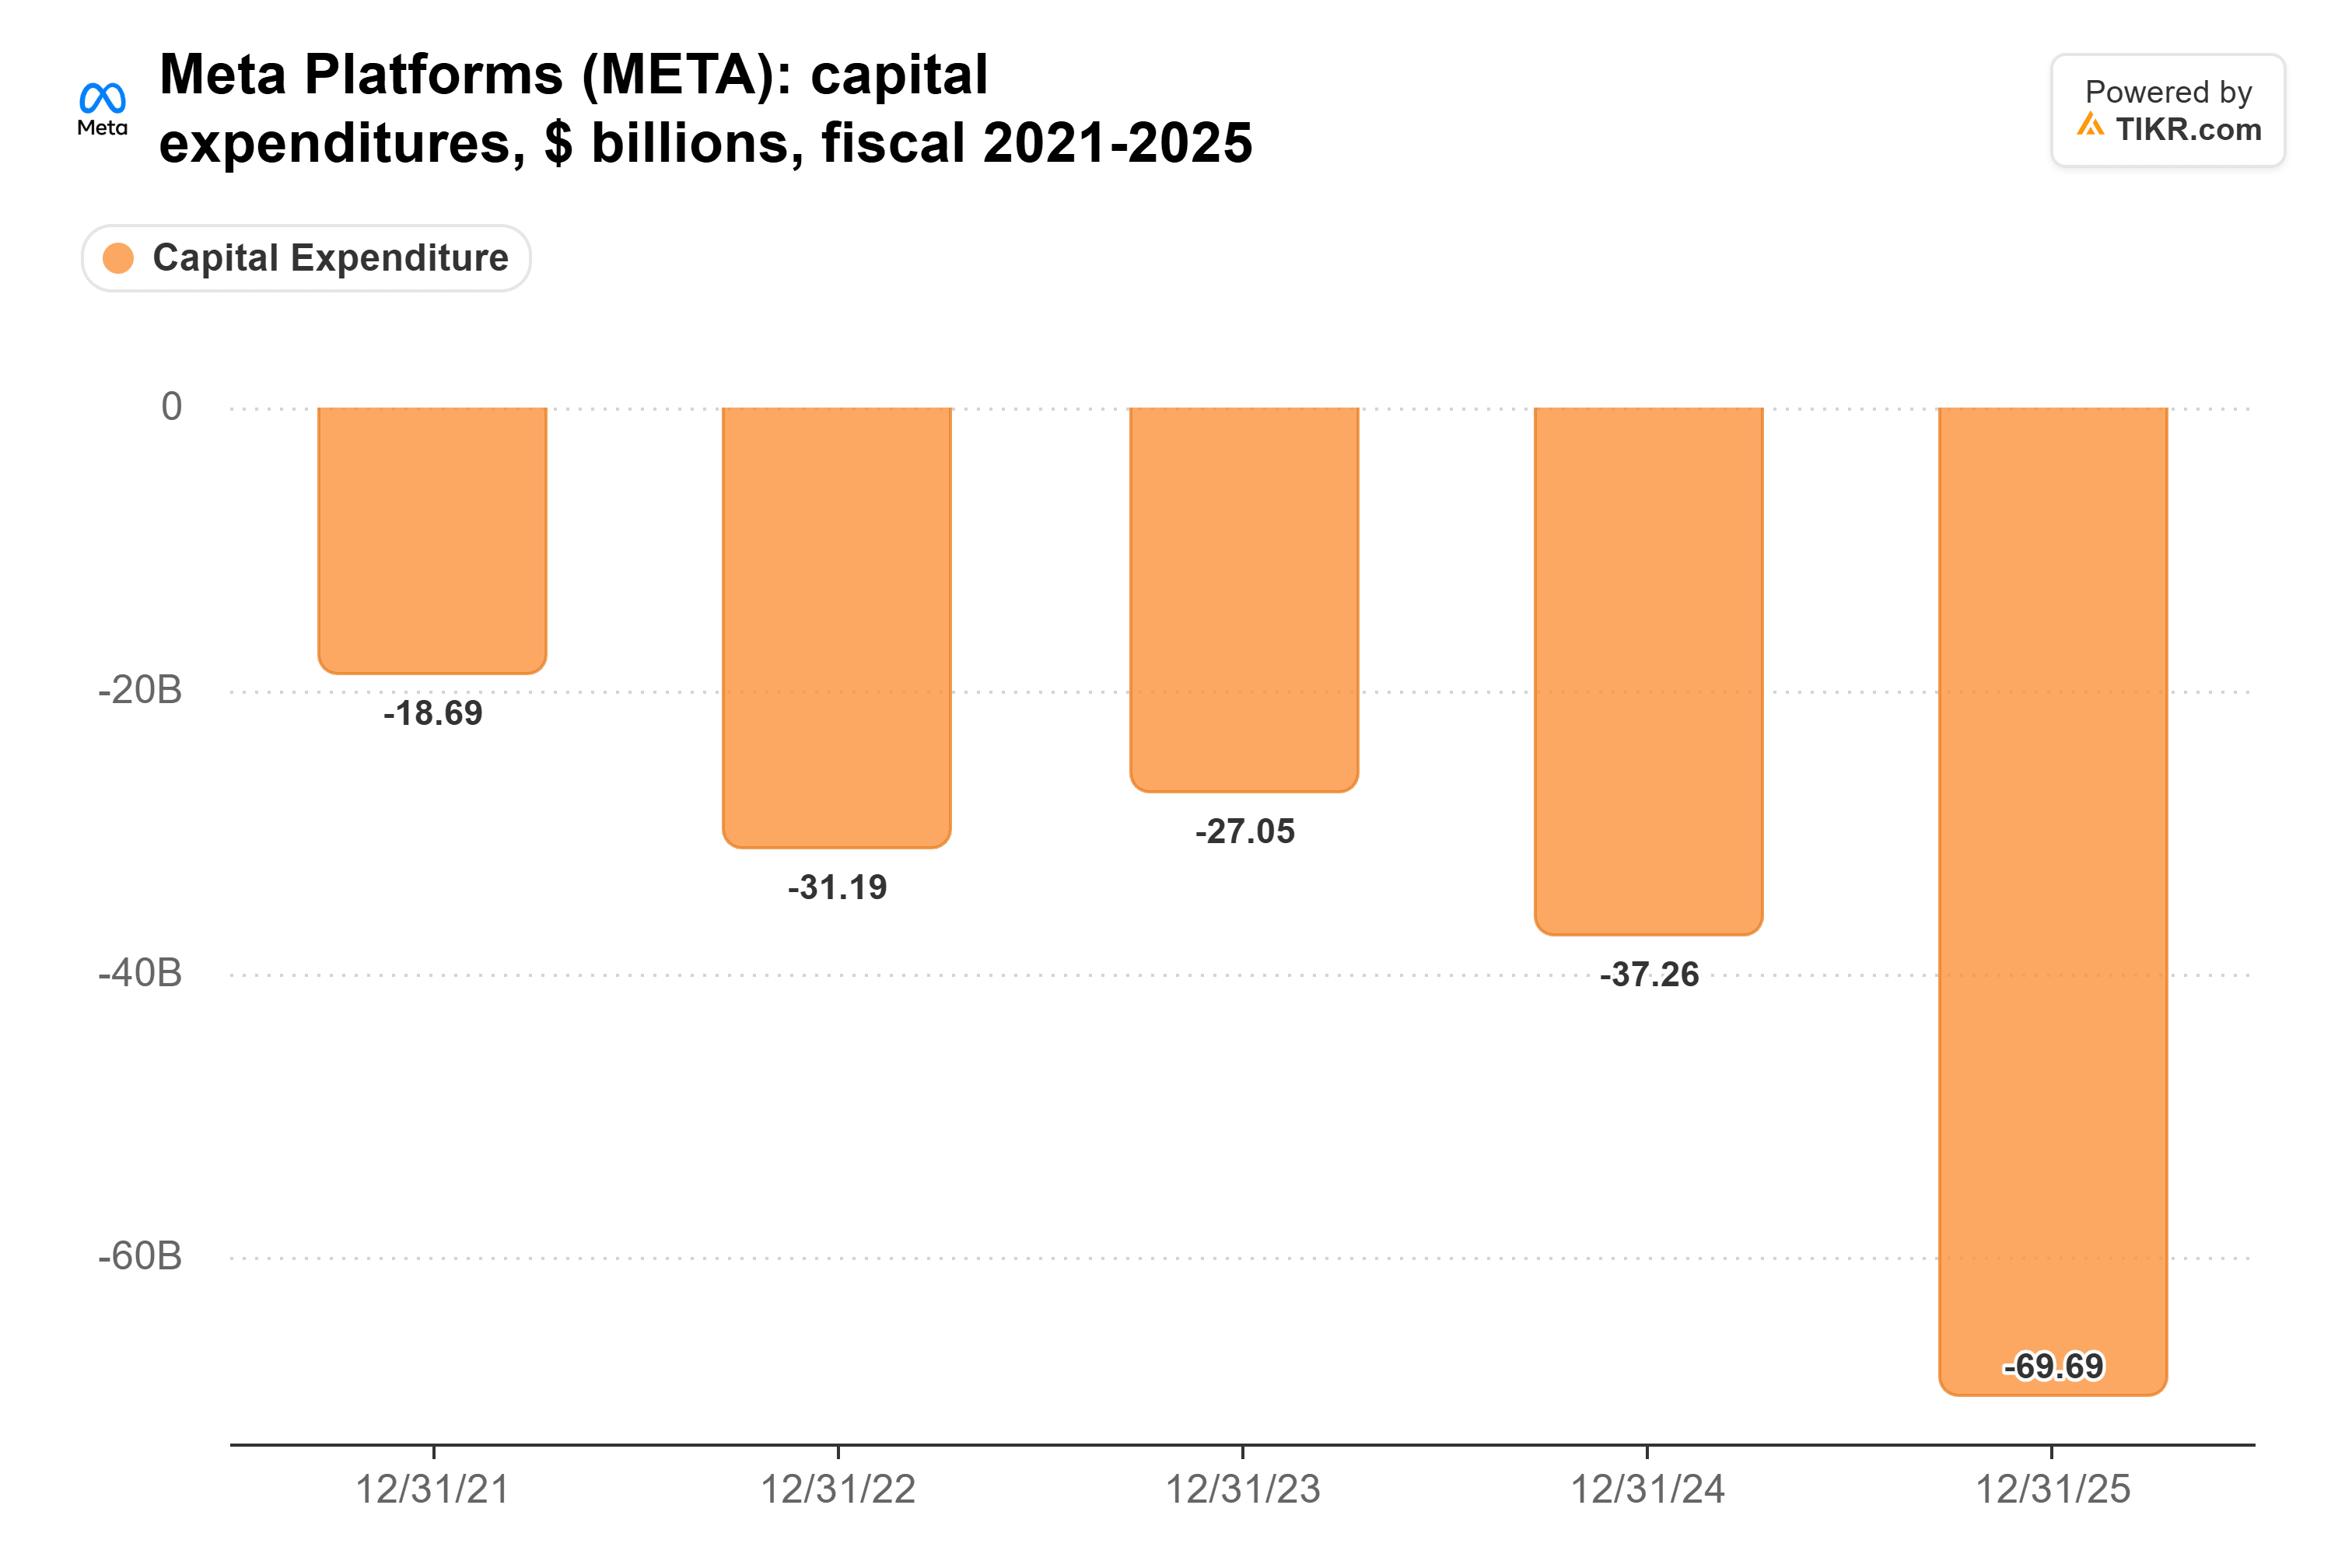
Management guides 2026 to $135 billion to $145 billion, finance leases included, and analysts expect $209.7 billion in 2027. In the earnings models that spending turns into depreciation, which consensus has climbing from $18.6 billion in 2025 to $64.1 billion in 2028.
That’s Ackman’s point. If all that compute pushes Meta’s growth even a few points above 20%, consensus earnings of $34.80 a share in 2027 and $40.42 in 2028 are too low.
Meta’s ad business is already growing faster than that. Third-quarter revenue rose 26% to $64.6 billion, with price per ad up 14%, and management guides fourth-quarter revenue up 22% to 27%.
Meta still has to charge for Muse
Ackman’s bigger bet is Muse, Meta’s personal AI agent. Asked about Meta’s fight with Amazon, which has blocked Muse from shopping its store, he said: “We’ll do very well with Meta if Muse becomes pervasive around the world.”
Muse has the users for that. More than 10 million people in the US and Canada set it up in its first six weeks, management said on its third-quarter call. But most of them pay nothing. Meta’s chief AI officer, Alexandr Wang, told Nikkei the company has no plans for ads inside Muse, and management hasn’t put a revenue figure on it yet.
Meanwhile, Meta is spending more than it brings in. Ackman said the big spenders “don’t have to create financial risk for themselves in order to spend the money.” But at Sept. 30, Meta owed more than it held: $83.7 billion of debt, against $82.45 billion of cash and marketable securities. Consensus has its free cash flow negative in 2026, 2027 and 2028. S&P Global Ratings cut its outlook on Meta to negative on Oct. 30, and on its own measure it sees a cash deficit more than twice the size Wall Street does.
The discount is still there
Meta trades at 18x forward earnings, below its five-year average of 21x:
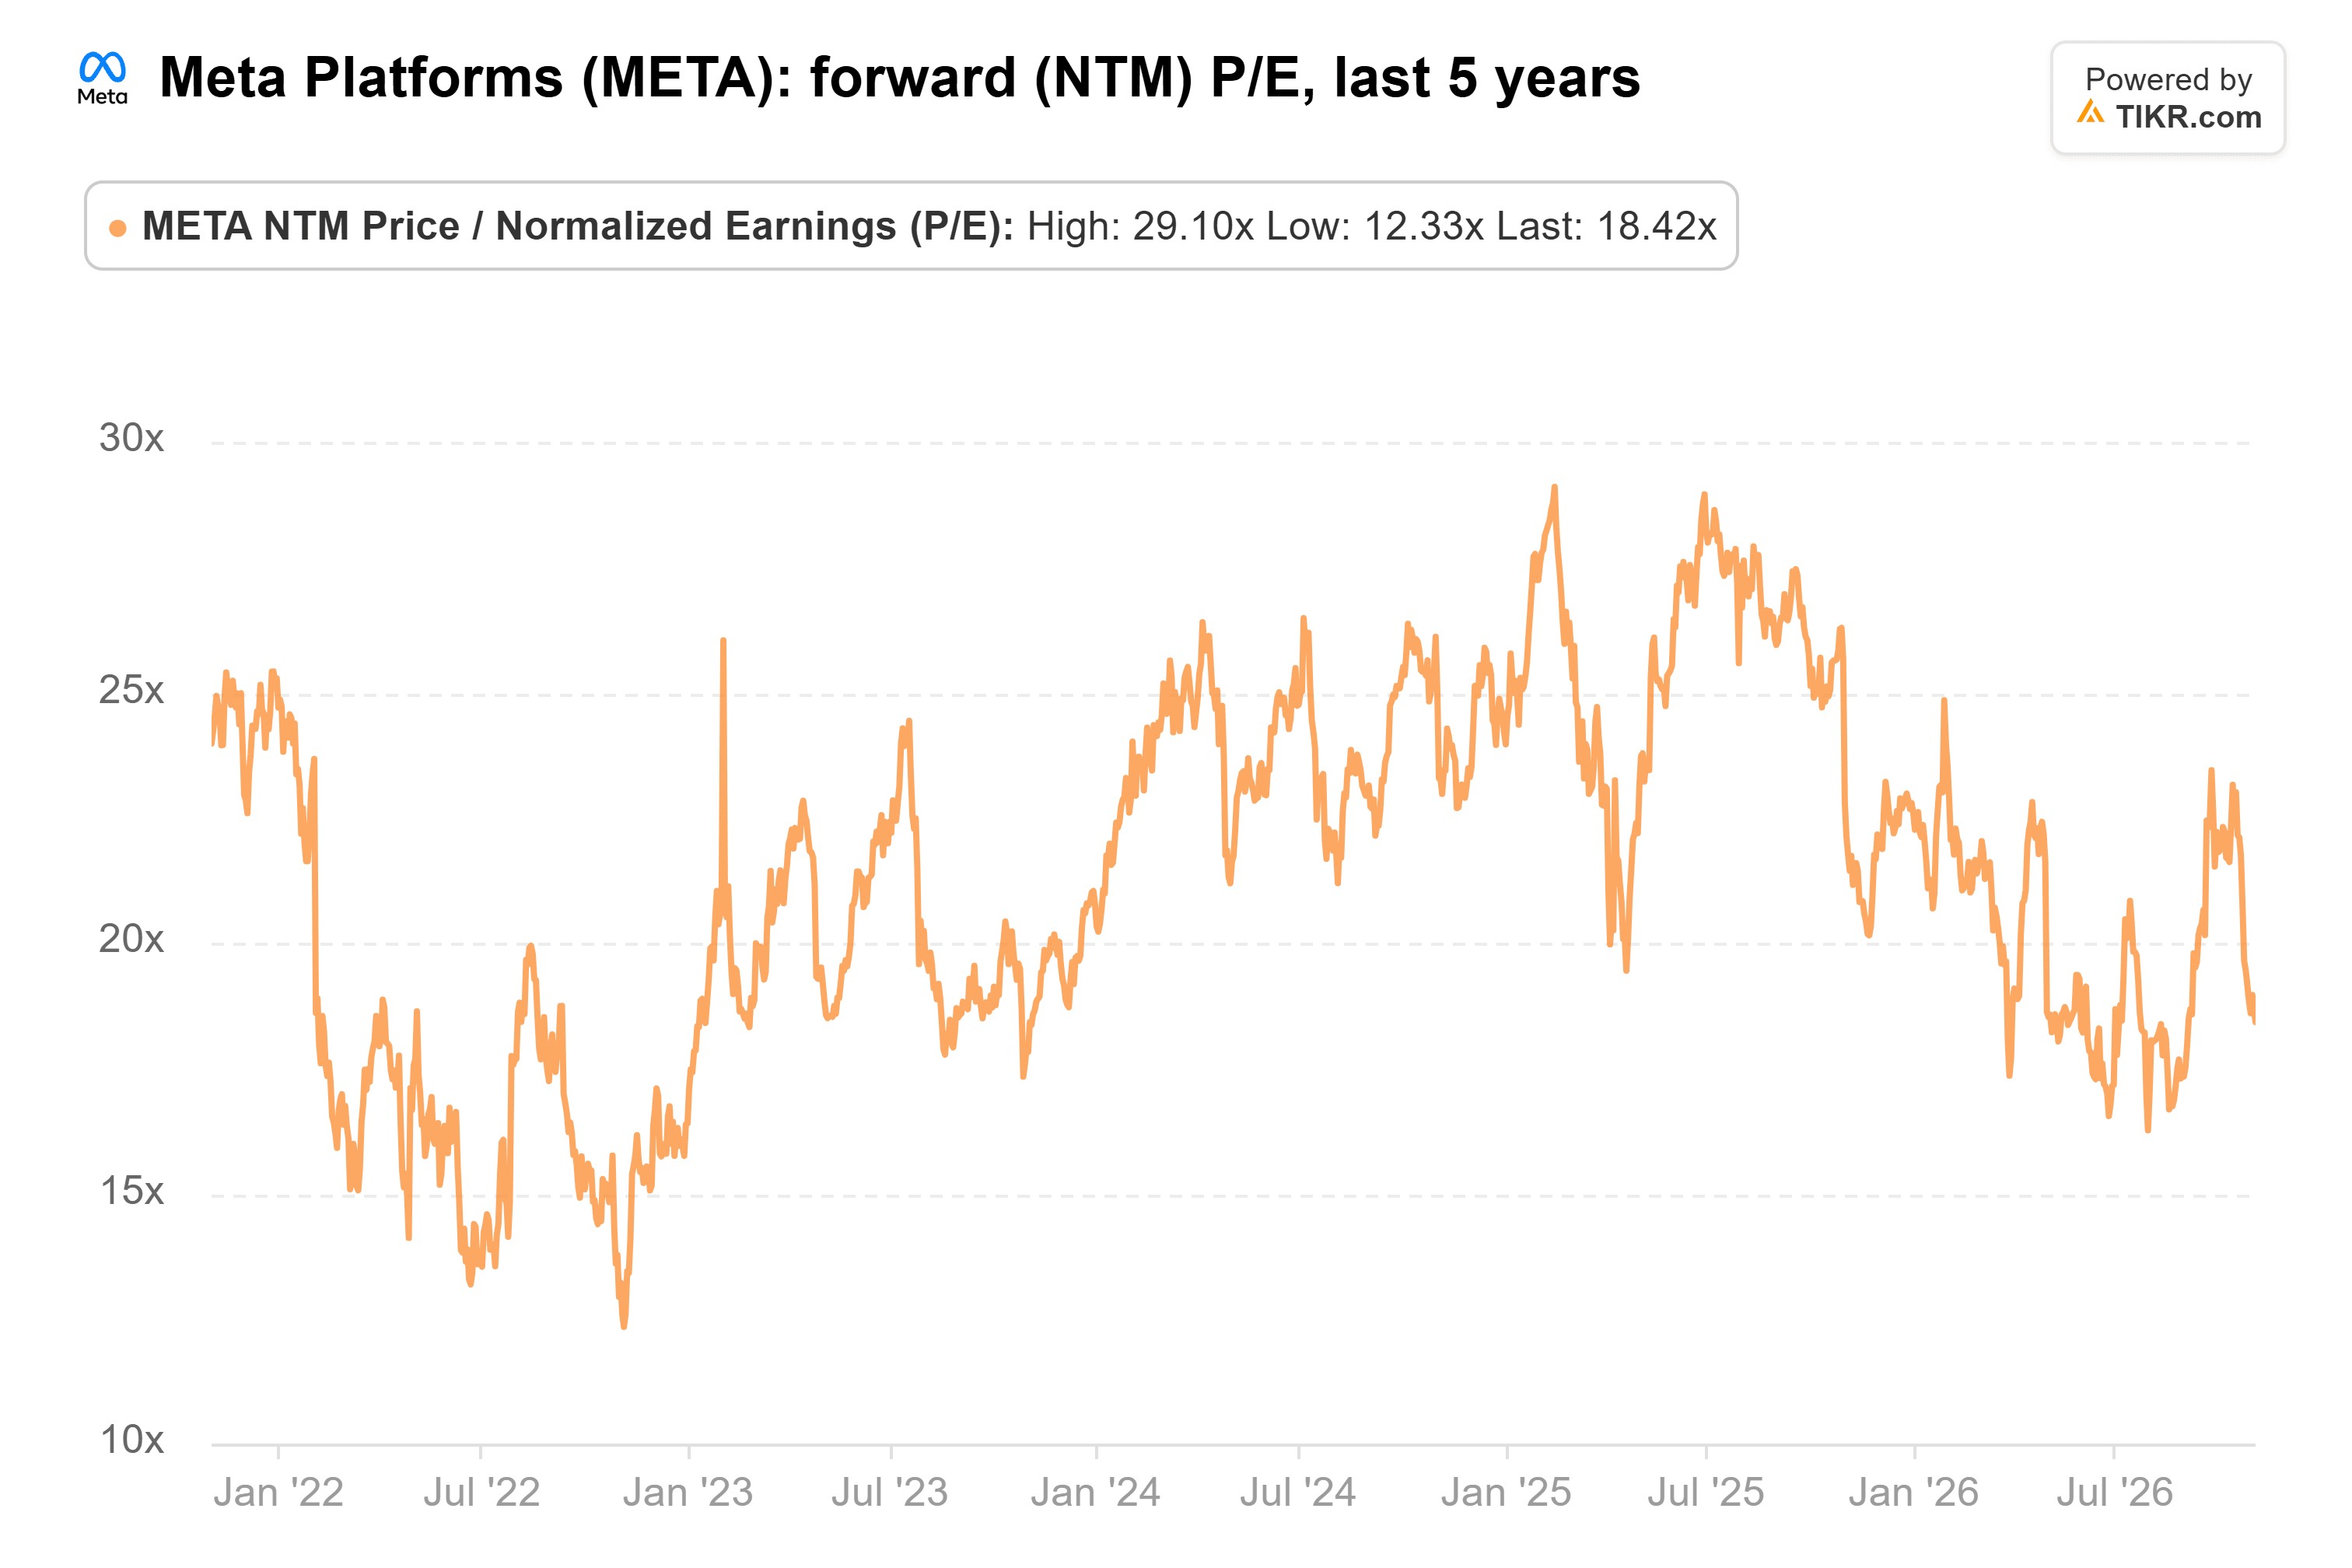
That’s a modest price for earnings analysts expect to grow 15% in 2027 and 16% in 2028.
The way I see it, at this price you’re paying for Meta’s ad business and getting Muse thrown in. If Muse catches on the way its first six weeks suggest, today’s price will look like a bargain.
Of course, Meta has to keep funding the build until then. The first real test is Meta’s fourth-quarter call in late January, when management lays out its 2027 capex plan and maybe gives a first revenue figure for Muse.
So what is Meta stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Meta could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!