Key Takeaways
- General Mills yields 7.0% and Comcast yields 5.4%, and both kept their quarterly dividends flat in their latest declarations.
- General Mills’s dividend took 85% of its free cash flow over the trailing 12 months, and management plans to hold the rate while it pays down debt.
- Comcast’s dividend took 24% of its free cash flow, and analysts expect 36% this year even as that cash flow falls.
- Comcast plans to finish separating NBCUniversal by the middle of next year and hasn’t said what either company will pay afterward.
General Mills (GIS) declared its quarterly dividend on Sept. 29 at the same $0.61 a share it was already paying. At the latest price, that’s a 7.0% yield.
Comcast (CMCSA) is holding its dividend steady, too. It declared $0.33 a share on Oct. 22, the same day management said it’s on track to spin off NBCUniversal by the middle of next year. Its yield is a smaller 5.4%, so which is the better high-yield dividend stock?
| Metric | General Mills (GIS) | Comcast (CMCSA) |
|---|---|---|
| Dividend yield | 7.0% | 5.4% |
| Dividend growth, 5 years | 3.9% a year (fiscal 2021-2026) | 7.5% a year (fiscal 2020-2025) |
| Cash dividend payout ratio, TTM | 85% | 24% |
| Cash dividend payout ratio, forward | 76% (fiscal 2027) | 36% (fiscal 2026) |
| Net debt/EBITDA | 3.7x | 2.3x |
| Interest coverage | 4.9x | 4.3x |
| Forward P/E | 11x | 7.2x |
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
General Mills is putting debt first
General Mills’s organic sales were flat in its fiscal 2027 first quarter, which ended Aug. 30, 2026, as North America Retail fell 3% organically on weak cereal and snacks. Management expects adjusted EPS of $3.00 to $3.20 for fiscal 2027.
Free cash flow fell from $2.29 billion in fiscal 2025 to $1.63 billion in fiscal 2026 (its years end in May), and the dividend’s share of it rose from 58% to 81%. The chart below shows free cash flow covering the dividend every year, by the slimmest margin in fiscal 2026:
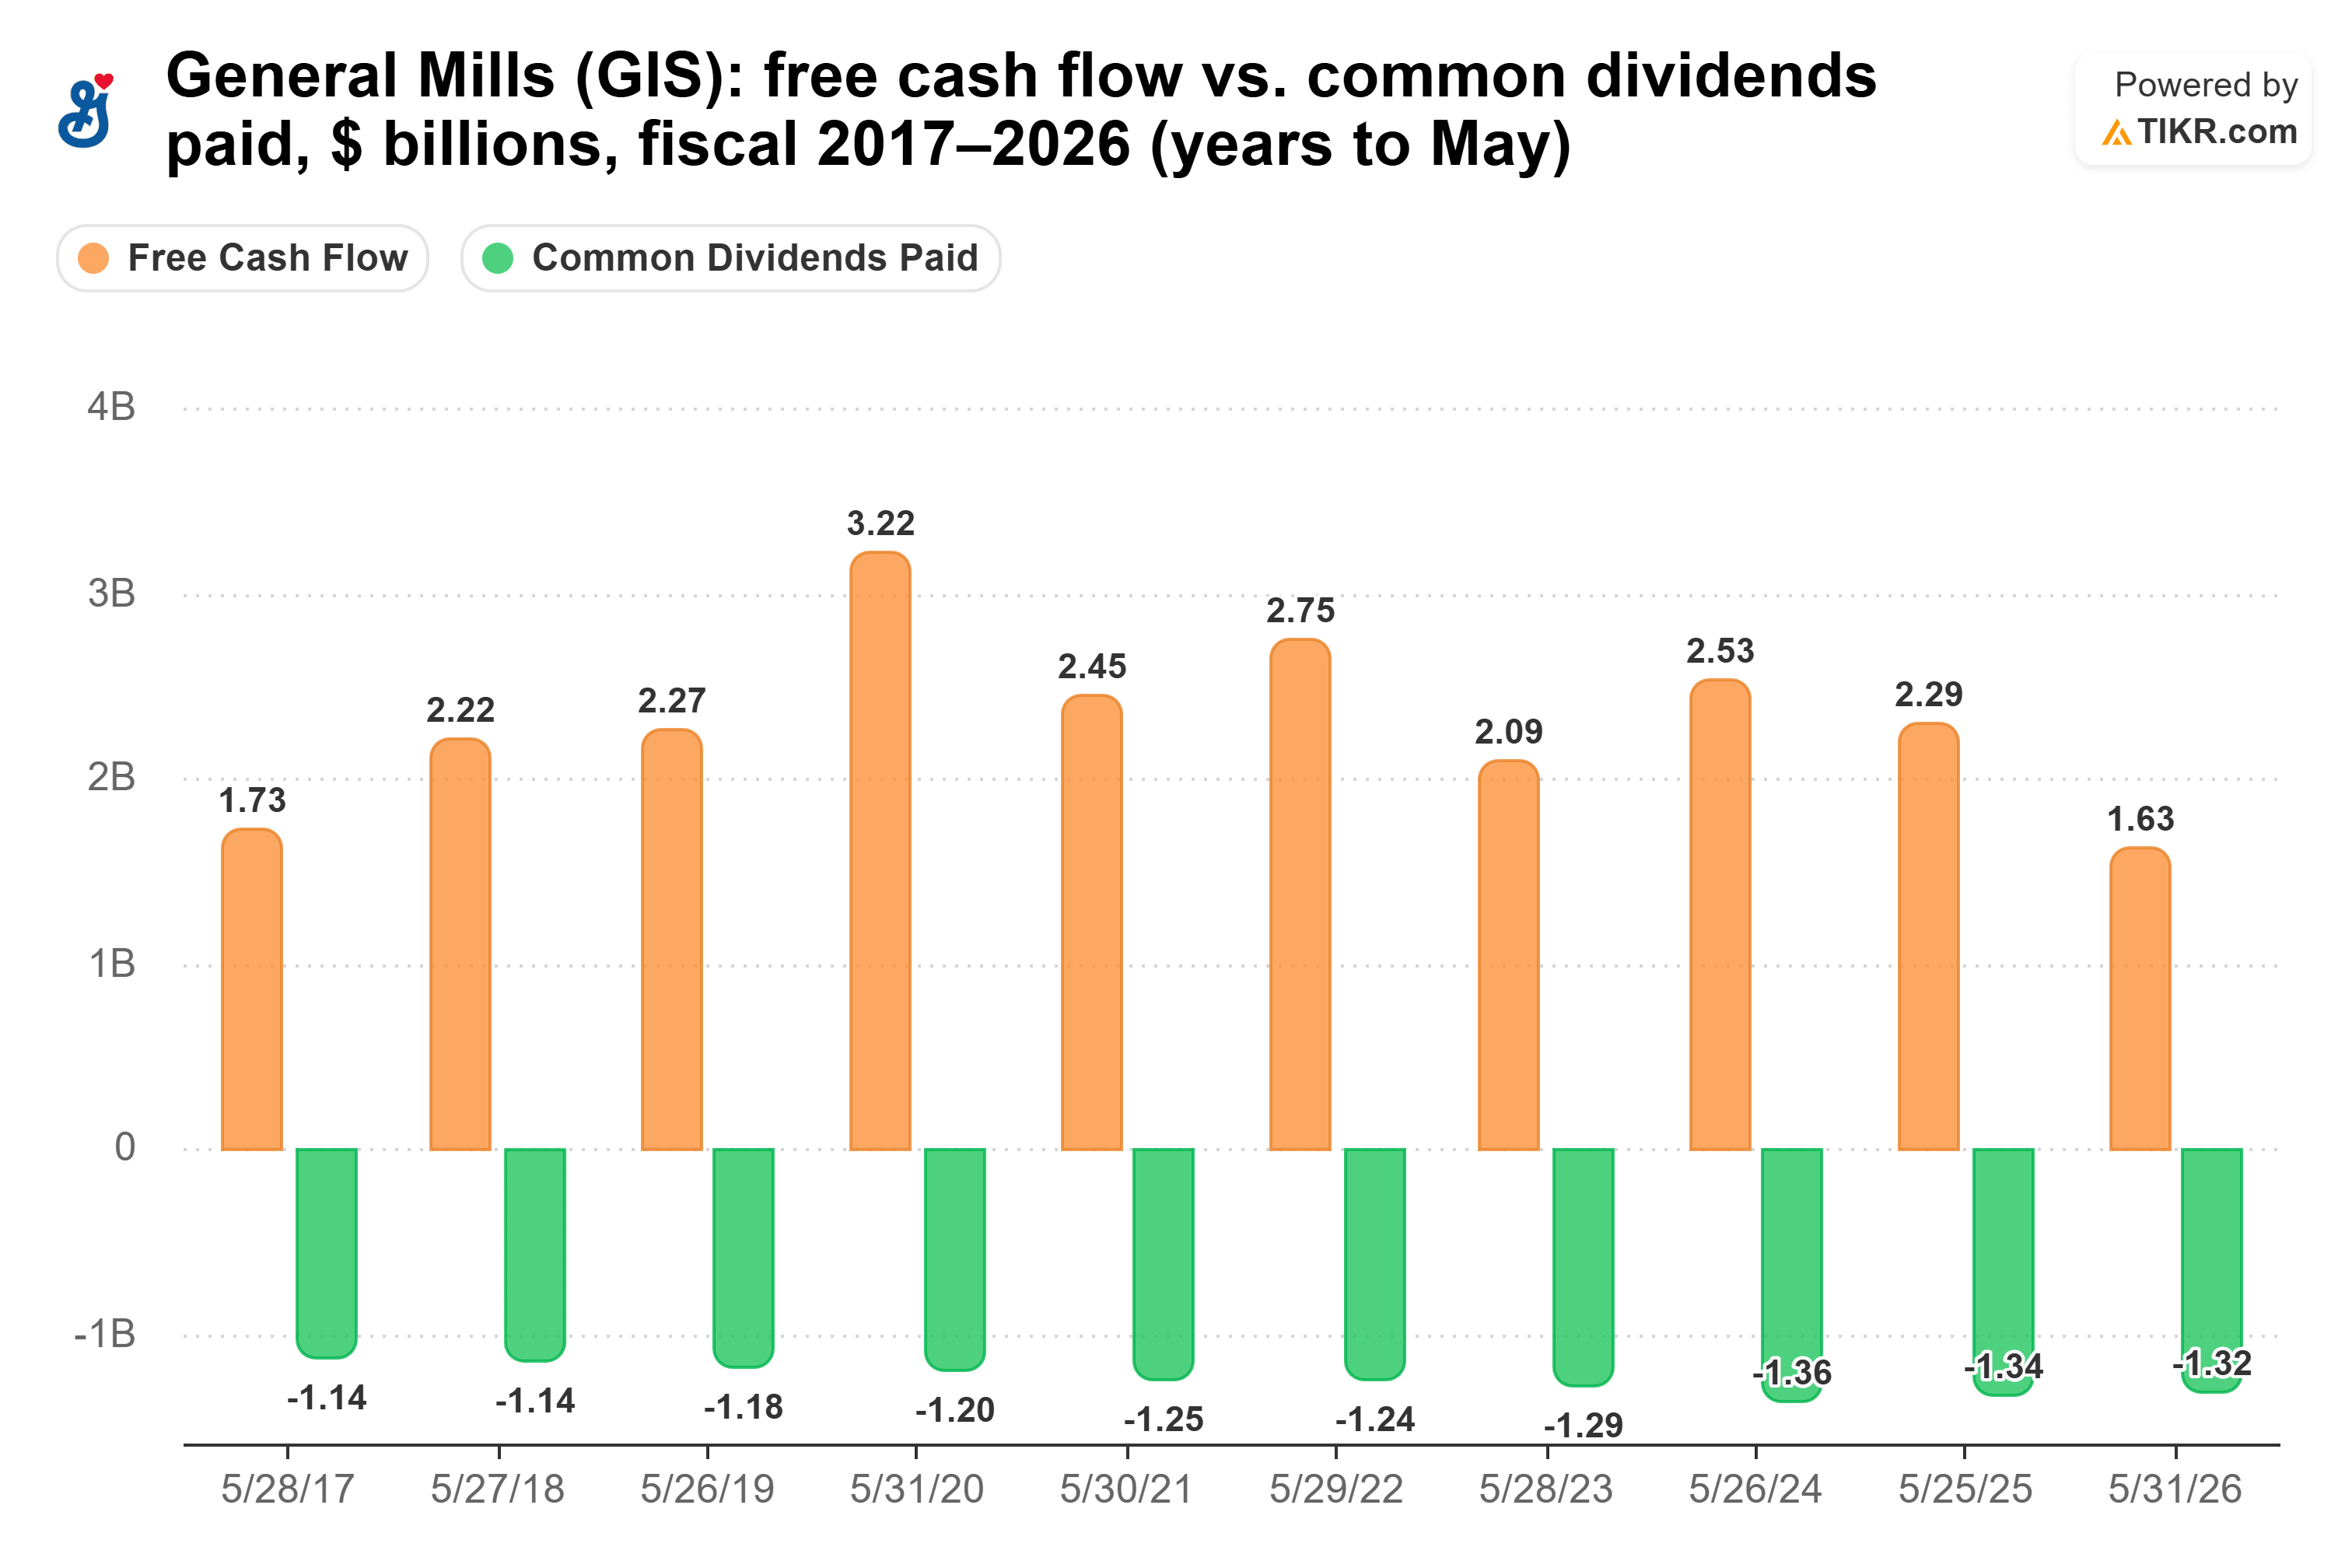
Over the 12 months to Aug. 30, 2026, the dividend took an uncomfortably high 85% of free cash flow. Analysts expect a still-tight 76% in fiscal 2027.
CFO Kofi Bruce said on Sept. 23 that “we remain fully committed to our dividend, and in the near term, we expect to maintain the current rate per share while we prioritize deleverage.” Net debt sits at 3.7x EBITDA, and he expects it to take “at least a couple of years” to get back to the company’s 3x target. With most of its free cash flow already going to the dividend, General Mills has little room if profit falls further.
Comcast is splitting itself in two
Comcast’s dividend has far more room, even with its business in the middle of its own overhaul. In the third quarter of 2026, revenue fell 6.1% from a year earlier to $29.3 billion (up 0.5% pro forma), and free cash flow fell 14.8% to $4.21 billion.
Comcast is moving broadband customers onto new pricing and giving away free wireless lines, and co-CEO Michael Cavanagh said those investments are “creating near-term financial pressure.”
None of that has come near the dividend. Over the 12 months to Sept. 30, 2026, Comcast’s $4.82 billion of dividends took a well-covered 24% of its $19.66 billion of free cash flow. The chart below shows dividends taking no more than 31.3% of free cash flow in any fiscal year from 2021 to 2025:
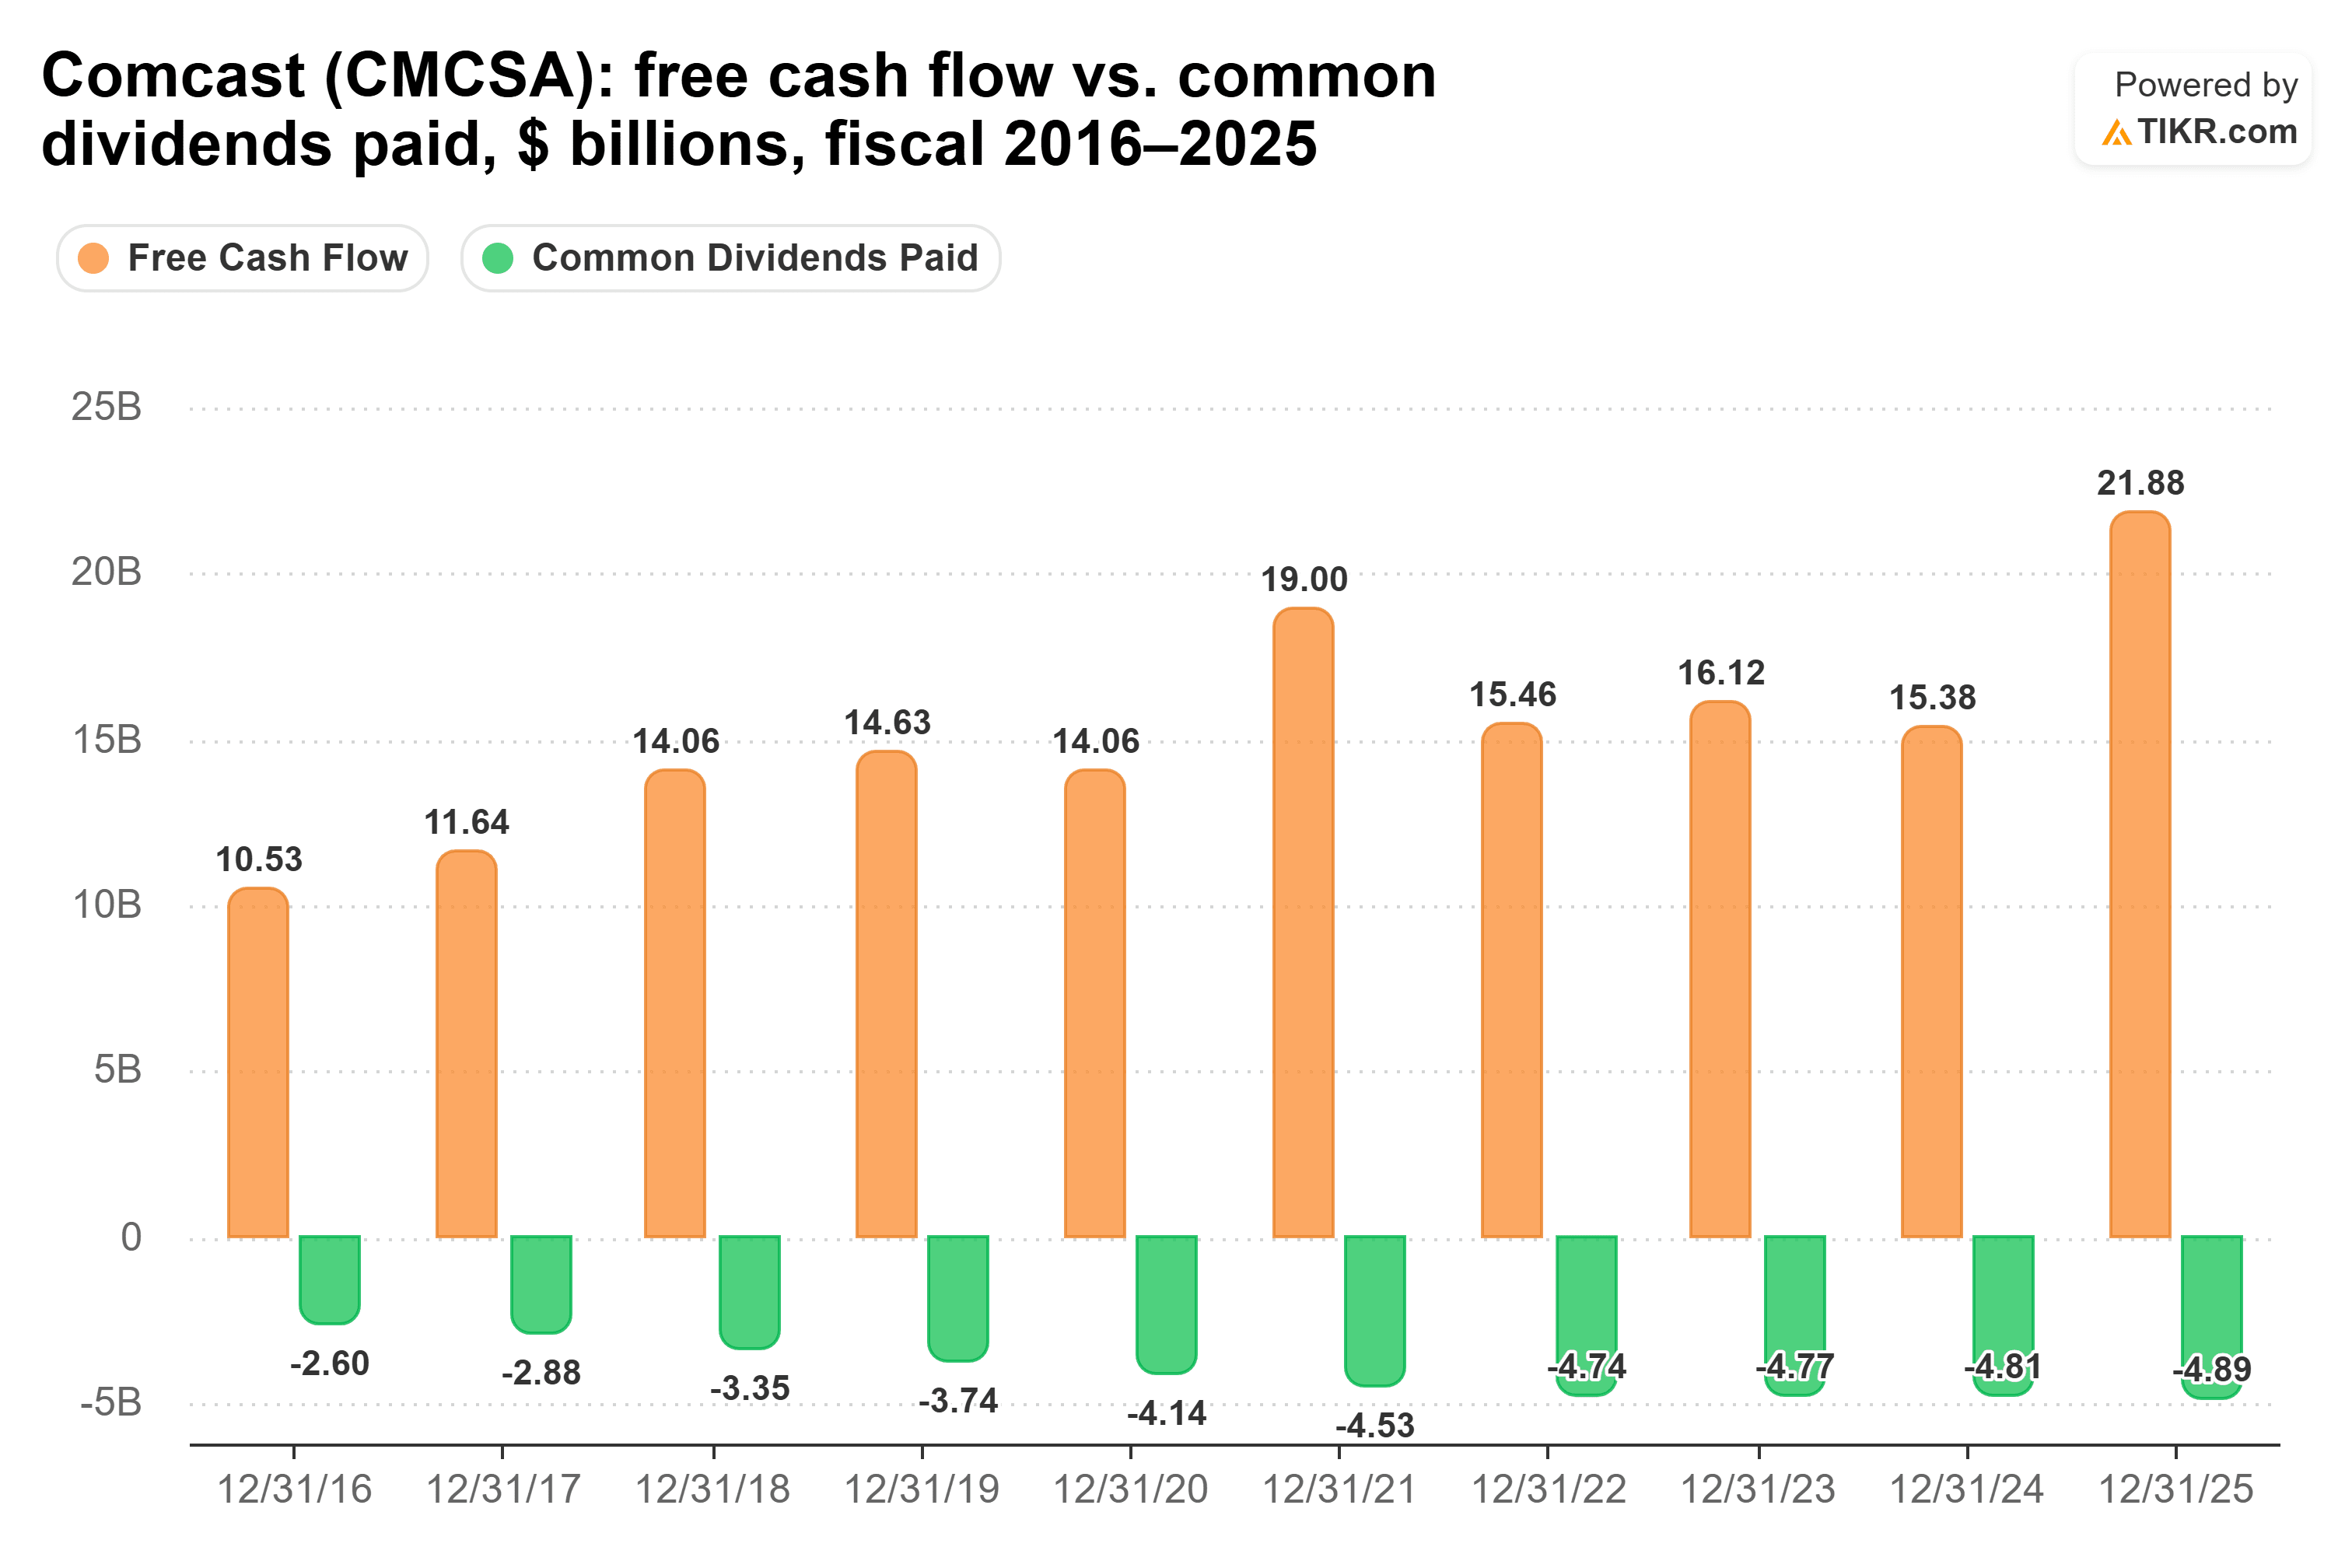
Comcast grew its dividend 7.5% a year from fiscal 2020 to fiscal 2025, from $0.92 a share to $1.32, and its net debt is a manageable 2.3x EBITDA. The main risk is broadband, where Comcast is still losing customers to fiber and fixed wireless.
So which dividend wins?
Comcast is the better high-yield dividend stock. General Mills pays the bigger check, but its dividend takes 85% of its free cash flow against Comcast’s 24%, and it’s frozen while the company works down more debt.
Comcast’s cushion holds up even on analysts’ lower forecast. On their measure, its free cash flow jumped from $12.5 billion in 2024 to $19.2 billion in 2025. They expect $13.6 billion this year, close to 2023’s $13.0 billion, as the chart below shows:
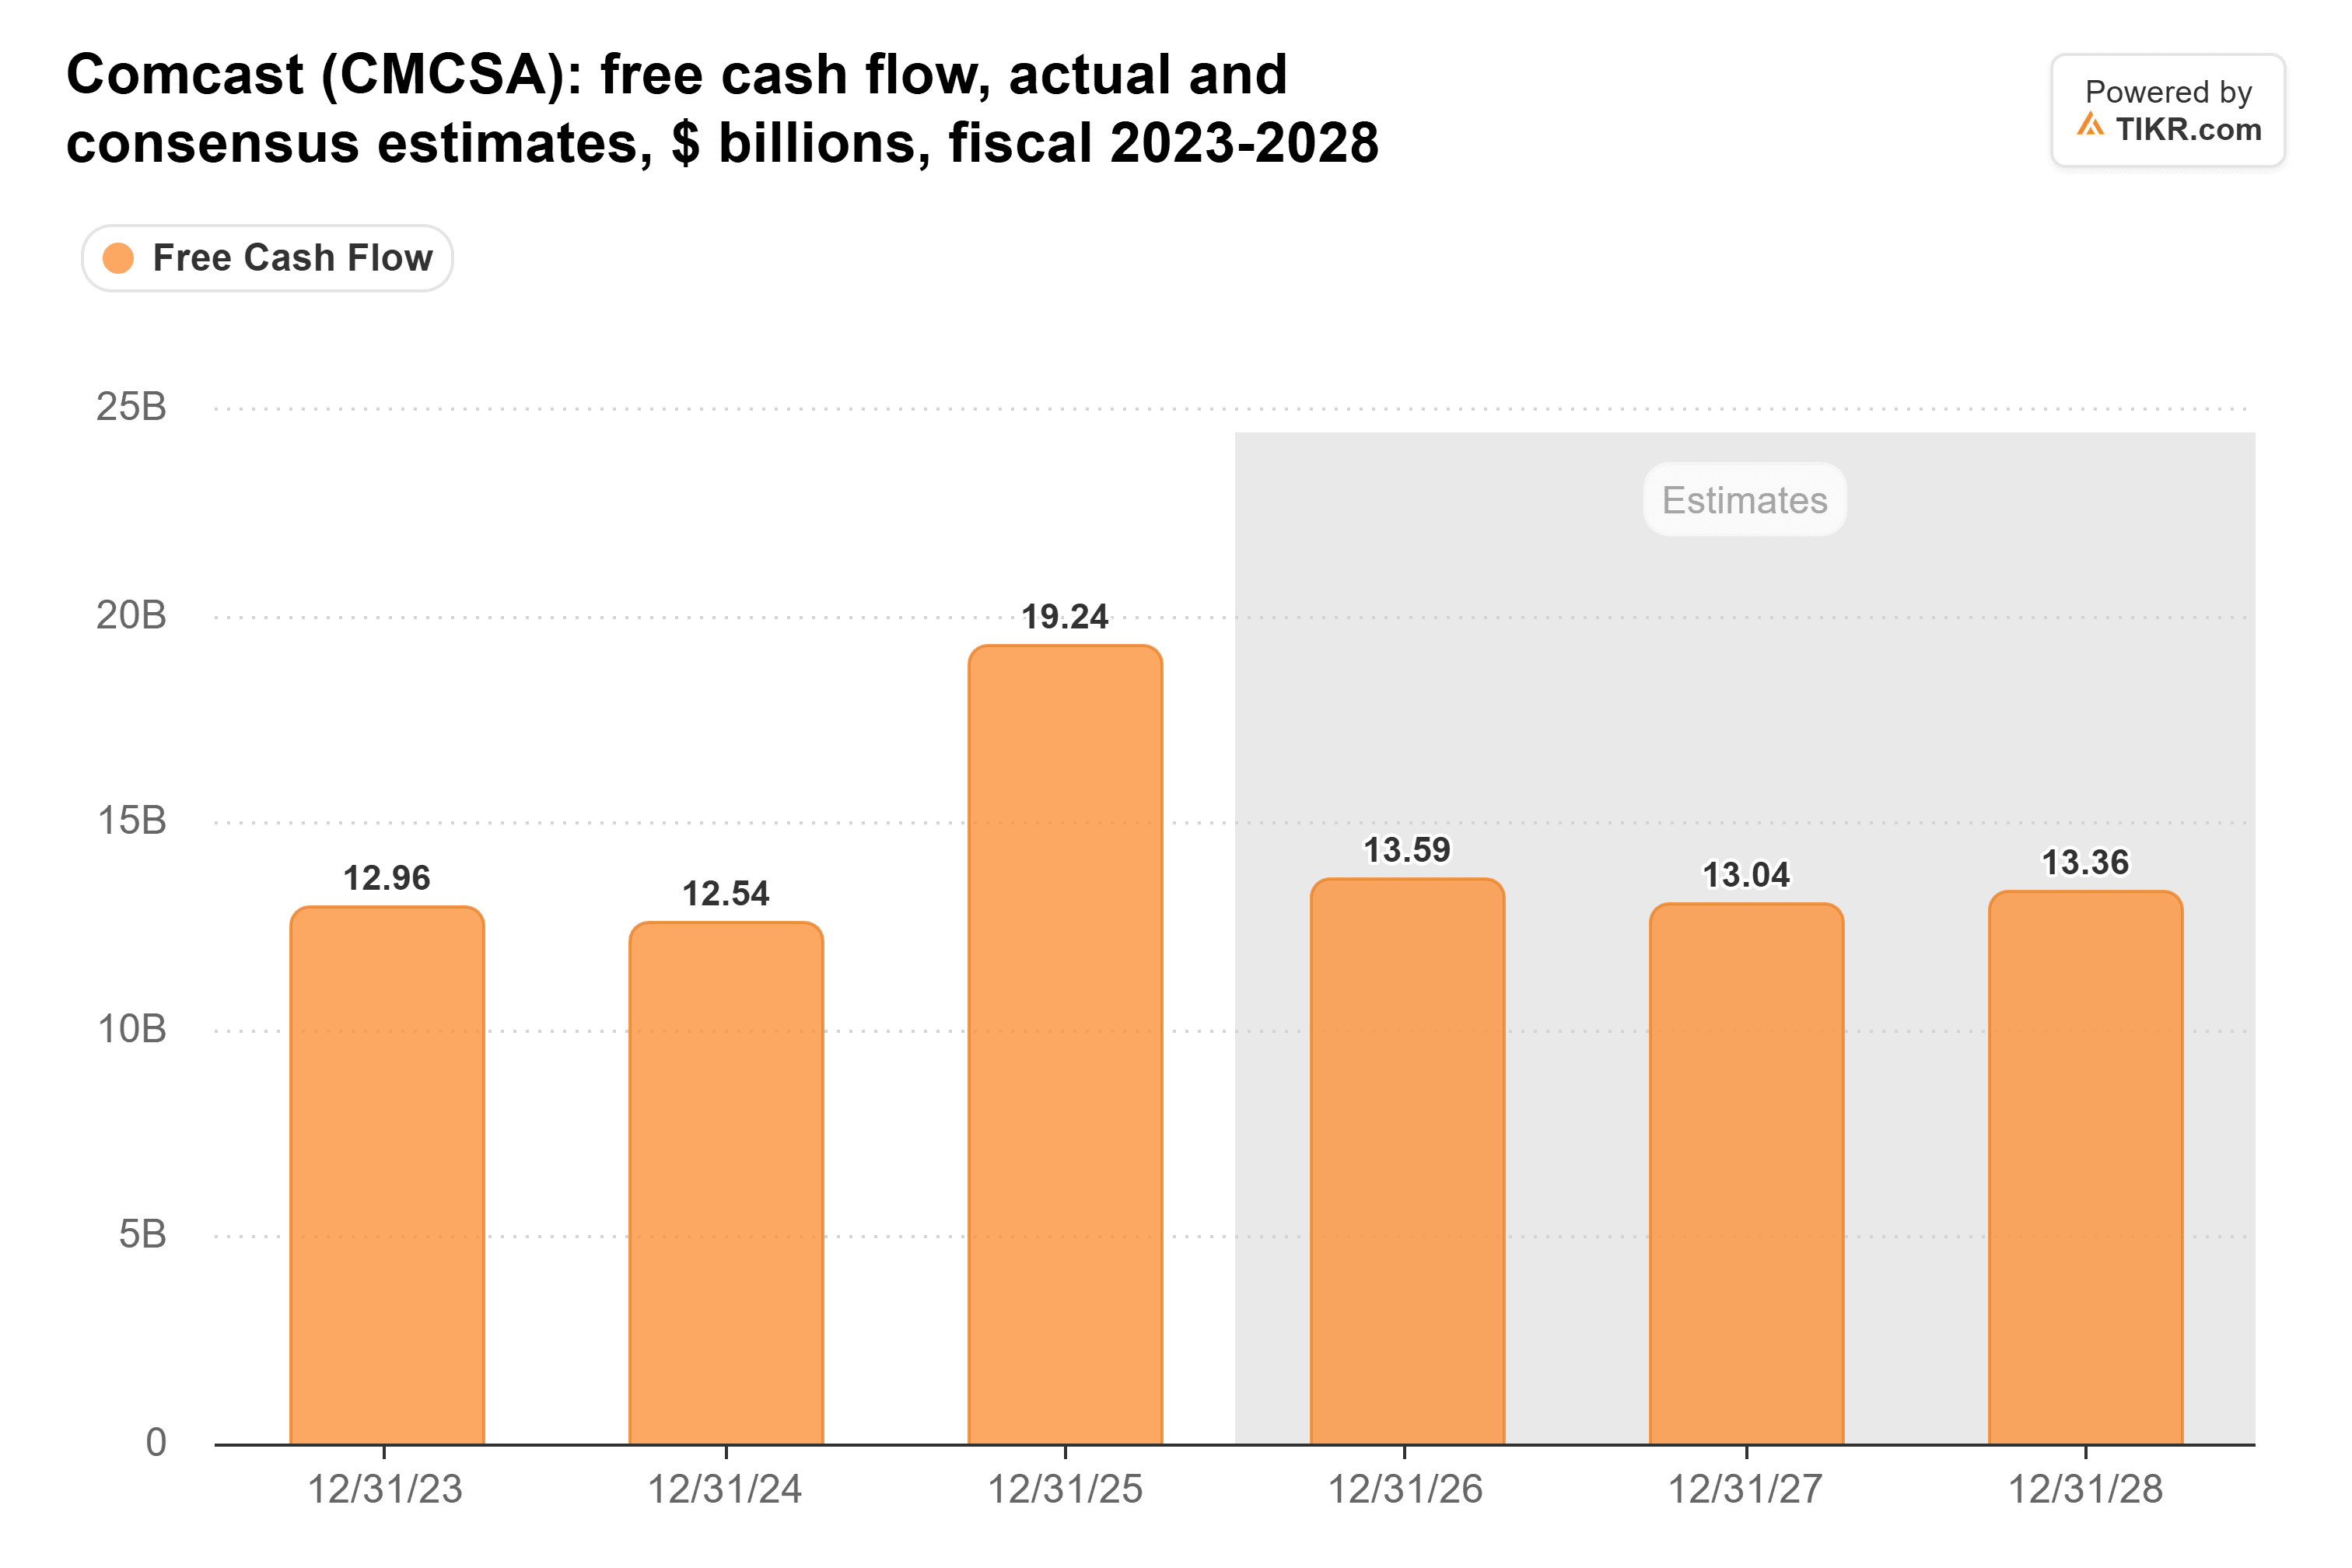
At that level, the dividend would still take only 36% of free cash flow. Sixteen analysts make the estimate, and last year’s final consensus was 12% off the actual.
The faster-growing dividend also closes the income gap:
- In year 10, at five-year rates: $10,000 in Comcast would pay about $1,040, a 10.4% yield on the original $10,000, against about $983, or 9.8%, from General Mills.
- When Comcast pulls ahead: around 2034 at five-year rates, or around 2032 at each dividend’s latest pace (up 1.7% for General Mills in fiscal 2026, 6.5% for Comcast in fiscal 2025).
General Mills’s dividend isn’t in danger. The company says it and its predecessor have paid dividends without interruption for 128 years, and its bigger check is a lot of income to pass up. It’s just that Comcast’s dividend has far more room to keep growing, and that’s worth more to me than the extra income today.
Of course, nobody knows yet what Comcast will pay after the split. In July, Comcast’s management said it would “take the coming months … to work through capital allocation, capital structure policies.” Those policies are the thing to watch.
Forget Comcast: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Comcast isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!