

Key Takeaways
- Baird cut its Qualcomm price target to $320 from $400 after the fiscal fourth-quarter report and kept its Outperform rating.
- Qualcomm’s phone chip sales are shrinking as Apple moves to its own modems, while its data center chips start shipping to Amazon and a second hyperscaler.
- Baird’s target implies 35x forward earnings, well above Qualcomm’s five-year high of 26x, and fiscal 2027 estimates are still falling.
- The fiscal 2029 plan may support Baird’s optimism, but a year is too short for investors to pay for it in full while estimates fall.
Qualcomm (QCOM) fell 9.49% to close at $156.75 on November 5, the day after its fiscal fourth-quarter report, as the PHLX Semiconductor Index dropped more than 10%. That left the stock 38% below its May 29 closing high. Baird cut its price target to $320 from $400 the same morning, and still sees 104% upside.
Phones are shrinking, and costs are rising
Two problems hit Qualcomm’s phone chips this year. The memory shortage cut Android phone builds, costing more than $1.50 of fiscal 2026 EPS, management said in July. And Apple (AAPL) is moving its iPhones to its own modems.
Wednesday’s report showed both. Handset chip revenue fell 26% year over year to $5.1 billion in the September quarter, and Qualcomm expects another dip in December as Apple revenue shrinks.
Higher costs for wafers, packaging and memory are hitting margins too. Qualcomm is raising chip prices, with the full benefit due only in the second half of fiscal 2027. It guided its chip unit’s pre-tax margin to 20%-22% for December, down from 24% in September, though about 3 points of that comes from moving data center into the unit.
Baird is betting on what comes after phones
Baird analyst Tristan Gerra kept his Outperform rating, so the firm still expects the stock to beat the market even after the cut.
The report backed up part of that call. Automotive revenue hit a record $1.99 billion, up 89% year over year. Data center sales start this quarter, as custom chips ship to Amazon (AMZN) and a second hyperscaler, and management kept its $5 billion data center target for fiscal 2027.
TIKR tracks 37 analysts on Qualcomm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Qualcomm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Qualcomm’s Analyst Ratings
Qualcomm hasn’t traded at Baird’s multiple in years
The rest of the Street is far less excited. The Street’s mean target has stayed between $150 and $223 over the past year:
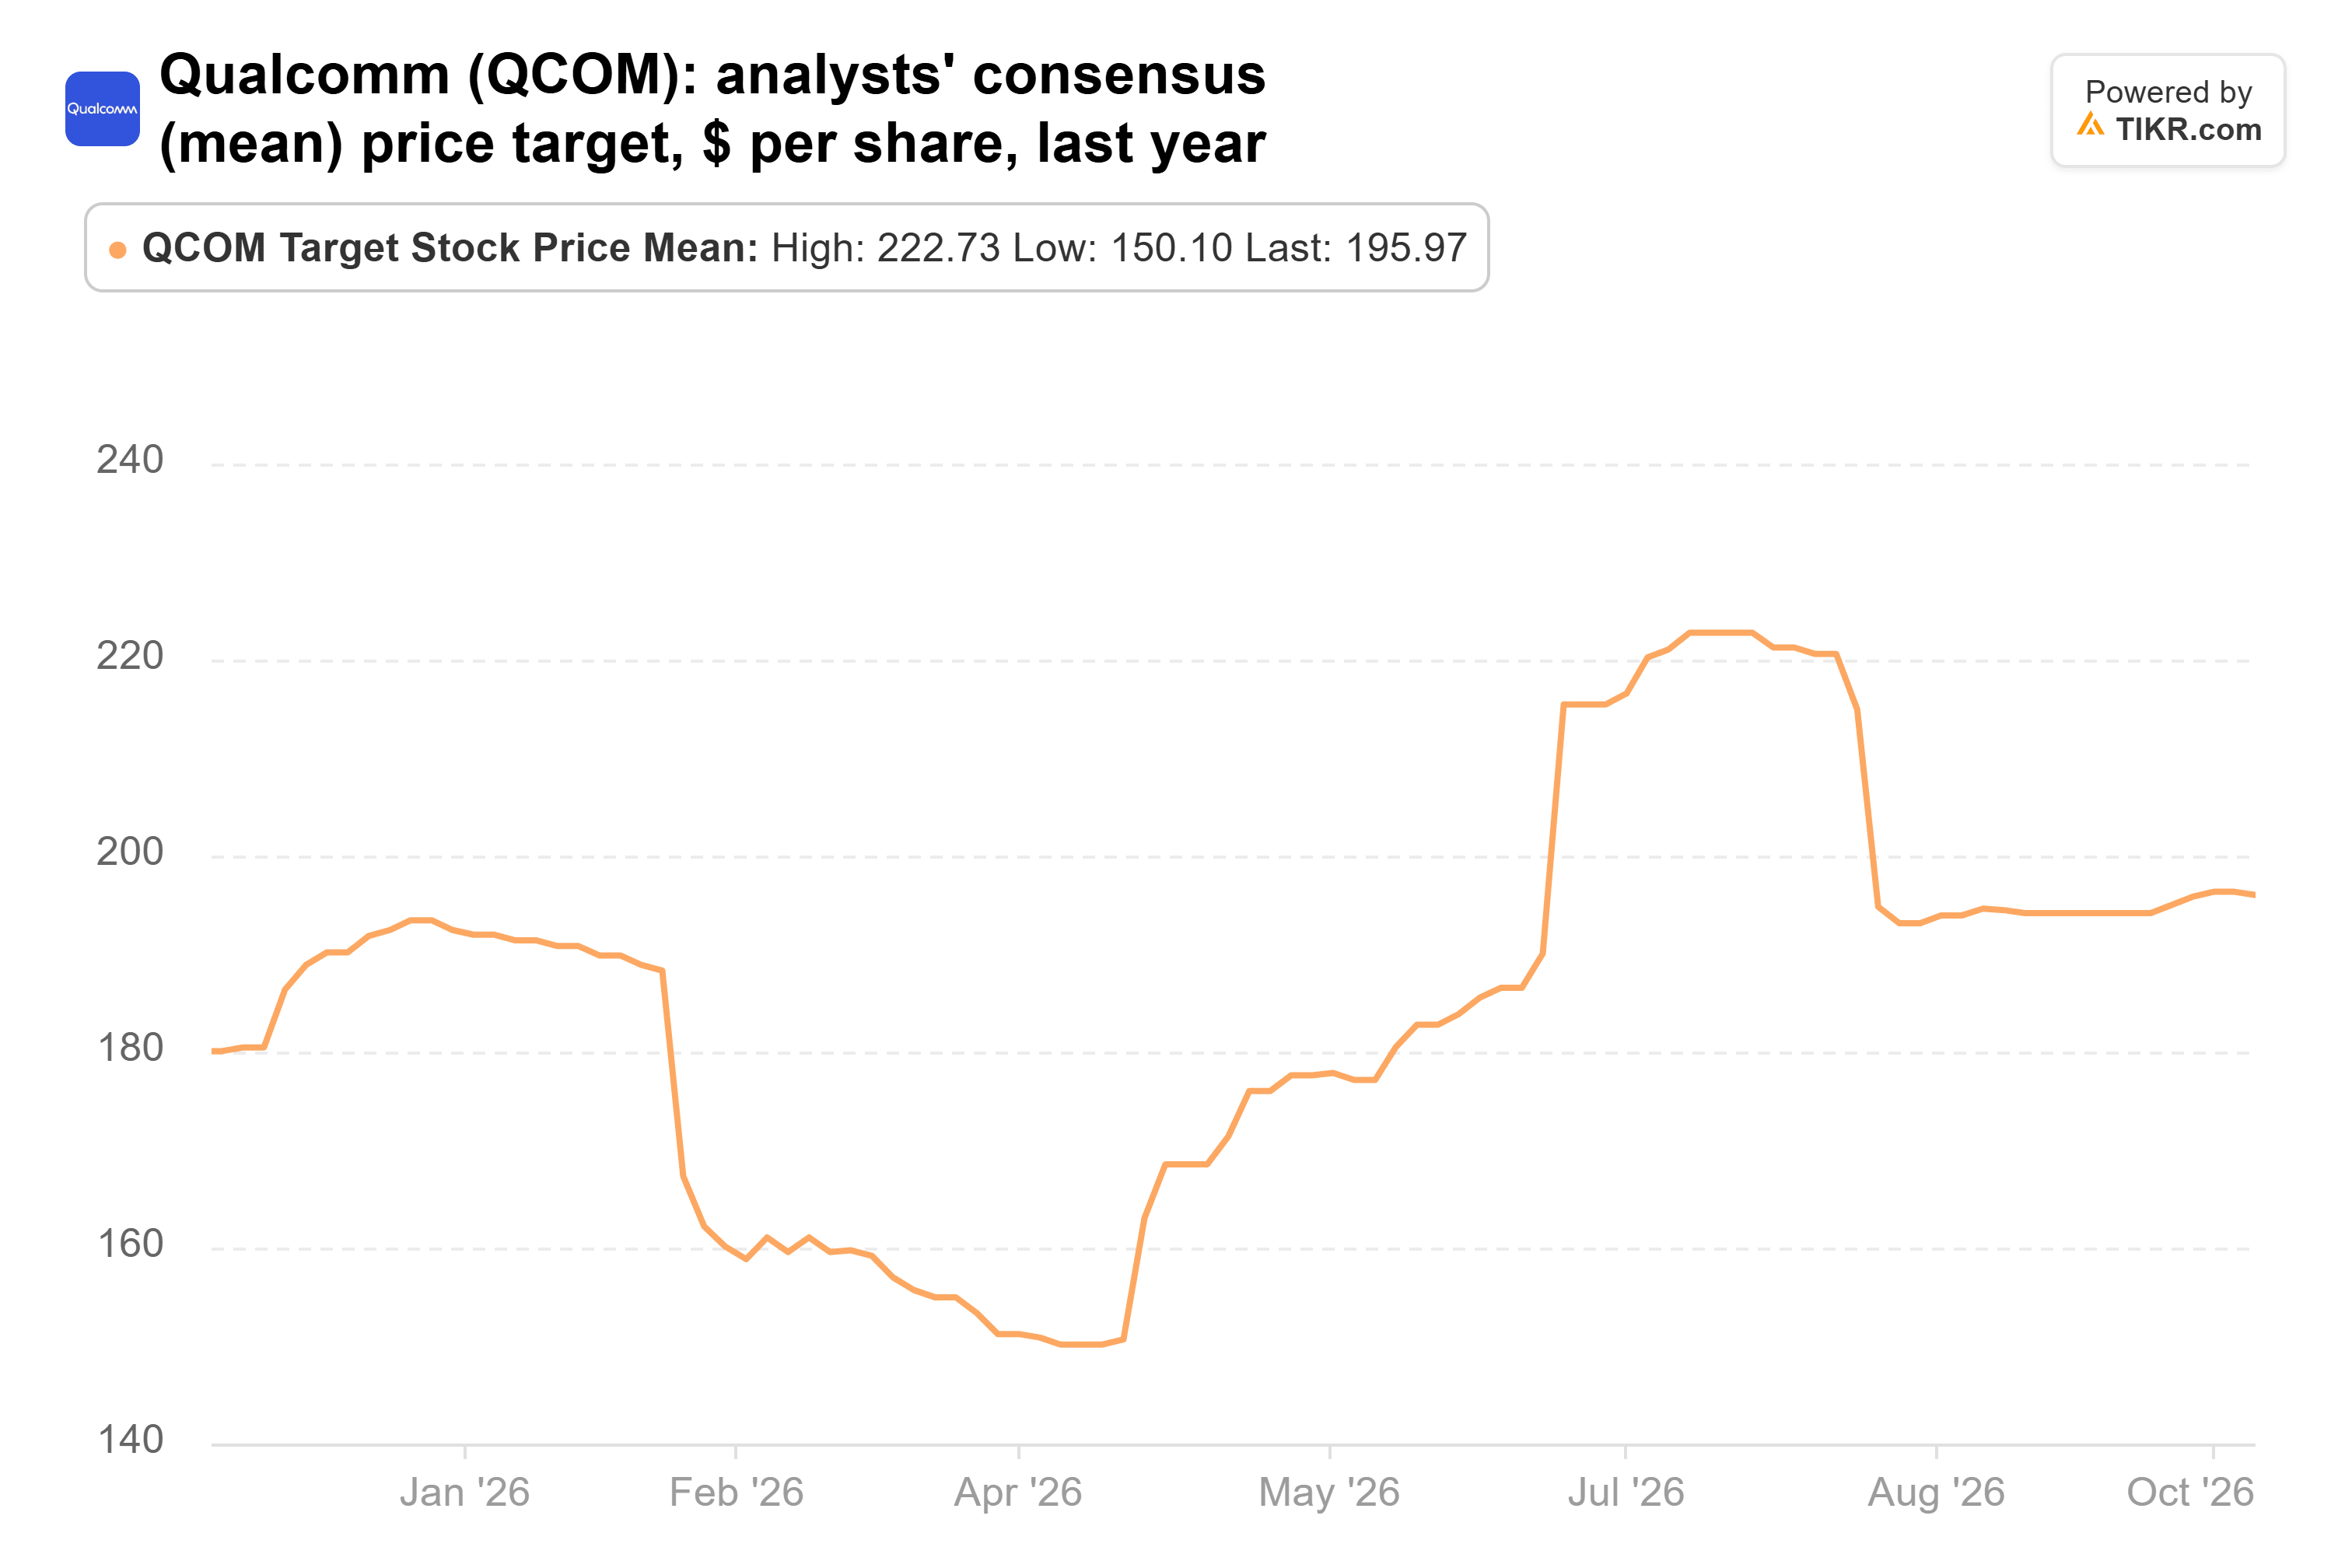
At $196 as of Monday, the mean target is 25% above the November 5 close, and Baird’s $320 is 63% above that mean.
Analysts expect normalized EPS to slip to $10.17 in fiscal 2027, from the $10.54 of non-GAAP EPS Qualcomm just reported for fiscal 2026, before climbing to $12.89 in fiscal 2028:

That fiscal 2027 estimate is down 17% since September 2025, and the December-quarter EPS guide of $2.15 to $2.35 gives no sign of a quick turn.
Qualcomm traded at 17x forward earnings at Monday’s close, above its five-year average of 14x:

On the $9.27 a share analysts expect over the next twelve months, Baird’s $320 implies 35x, well past Qualcomm’s 26x peak in May.
A year is too soon for $320
Qualcomm is also counting on very few buyers for data centers. CEO Cristiano Amon said on the call that most of the $5 billion fiscal 2027 target comes from the two hyperscaler customers, one of them Amazon.
Baird may be right about where Qualcomm is headed. Management targets more than $18 of non-GAAP EPS in fiscal 2029. Investors are unlikely to pay for that plan in full within a year while estimates keep falling. A margin turn in the December quarter would be the first sign the Street’s targets could move toward Baird’s.
If the December-quarter report, due in early 2027, shows data center sales on pace for $5 billion and chip margins rising, that would be the turn to watch.
So what is Qualcomm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


