Key Takeaways
- Apple closed at a record on Nov. 4, worth about $5.08 trillion, the day Bloomberg reported it cut some engineers’ daily AI budgets to $200 from $300.
- Investors are rewarding Apple for staying out of the AI capex race, and the budget cuts show management protecting that discipline.
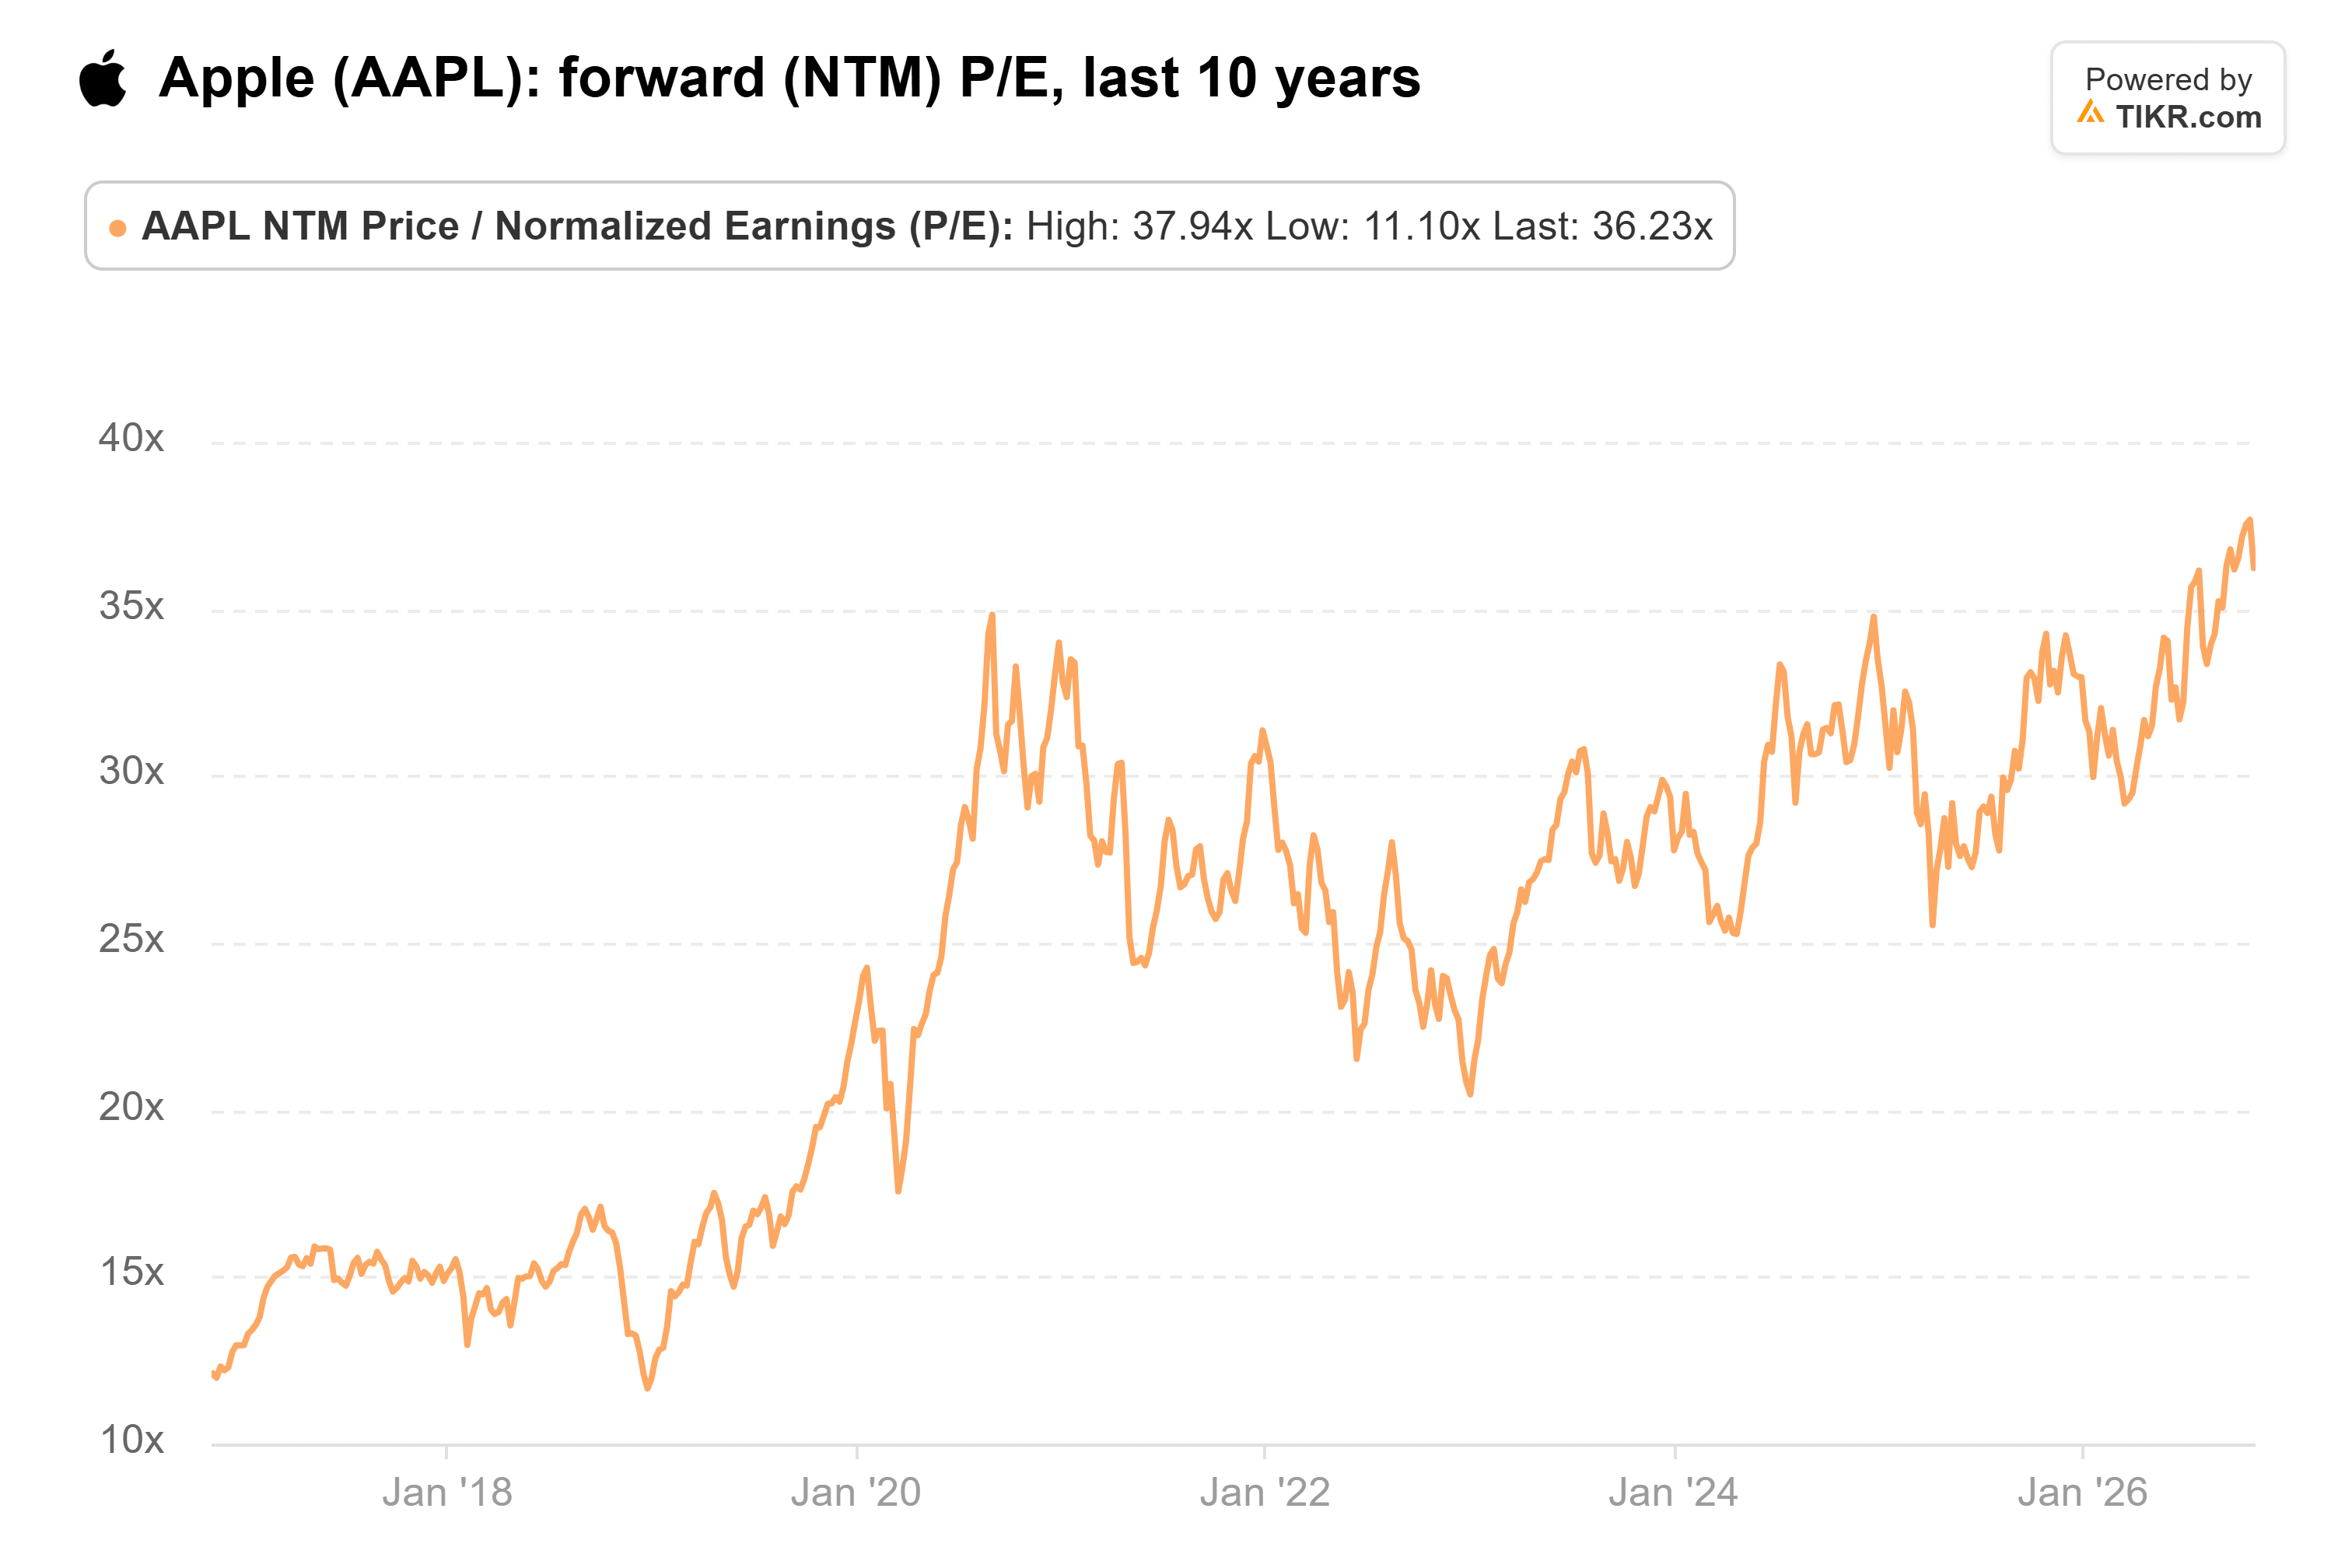
- At 36x forward earnings, against a 10-year average of 24x, Apple is priced well above the roughly 6% EPS growth analysts expect in fiscal 2027.
- The premium could shrink fast if Microsoft’s and Alphabet’s AI spending starts paying off, which makes the stock hard to buy at 36x.
Apple (AAPL) closed at a record $349.51 on Wednesday, Nov. 4, up 5.3% in the post-election rally, for a market value of about $5.08 trillion. The next day, as an AI sell-off knocked the Nasdaq down more than 5%, Apple slipped just 1.5%.
Josh Brown thinks he knows why. On The Compound and Friends, the Ritholtz Wealth Management CEO showed a chart: this year, on days the Philadelphia Semiconductor Index fell 2% or more, Apple rose 65% of the time.
His read: “Apple is like the anti-AI large cap tech trade.”
Then Bloomberg’s Mark Gurman reported that Apple lowered the daily AI spending cap for some engineers to $200 from $300 last month, with more cuts planned that could take some teams to $100. Many groups outside engineering already have a $100 cap, and Apple has considered cutting that to $25.
For the anti-AI trade, that’s about as on-brand as it gets.
Small Savings, but the Right Signal
The caps cover employees’ AI tools, not Apple’s AI budget. Some employees say few workers used their full $300 anyway, and Apple’s R&D rose 32% to $45.8 billion in fiscal 2026 on higher infrastructure and AI costs.
What sets Apple apart is how little it spends on building. Microsoft (MSFT) has reportedly tightened its own internal AI allowances too, but Apple’s capital spending fell 29% to $9.0 billion in fiscal 2026. Apple’s latest foundation models were custom-built with Alphabet (GOOG) using Google’s Gemini technology, and its most capable server model runs on Nvidia GPUs in Google Cloud.
The caps also fit the push by John Ternus, CEO since Sept. 1, for a faster, leaner Apple with fewer management layers.
TIKR Tracks 43 Analysts on Apple. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Apple, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Apple’s Analyst Ratings
Apple’s Growth Won’t Justify 36x
Analysts expect Apple’s normalized EPS to rise about 6% in fiscal 2027, to $9.50, after a 20% jump in fiscal 2026.
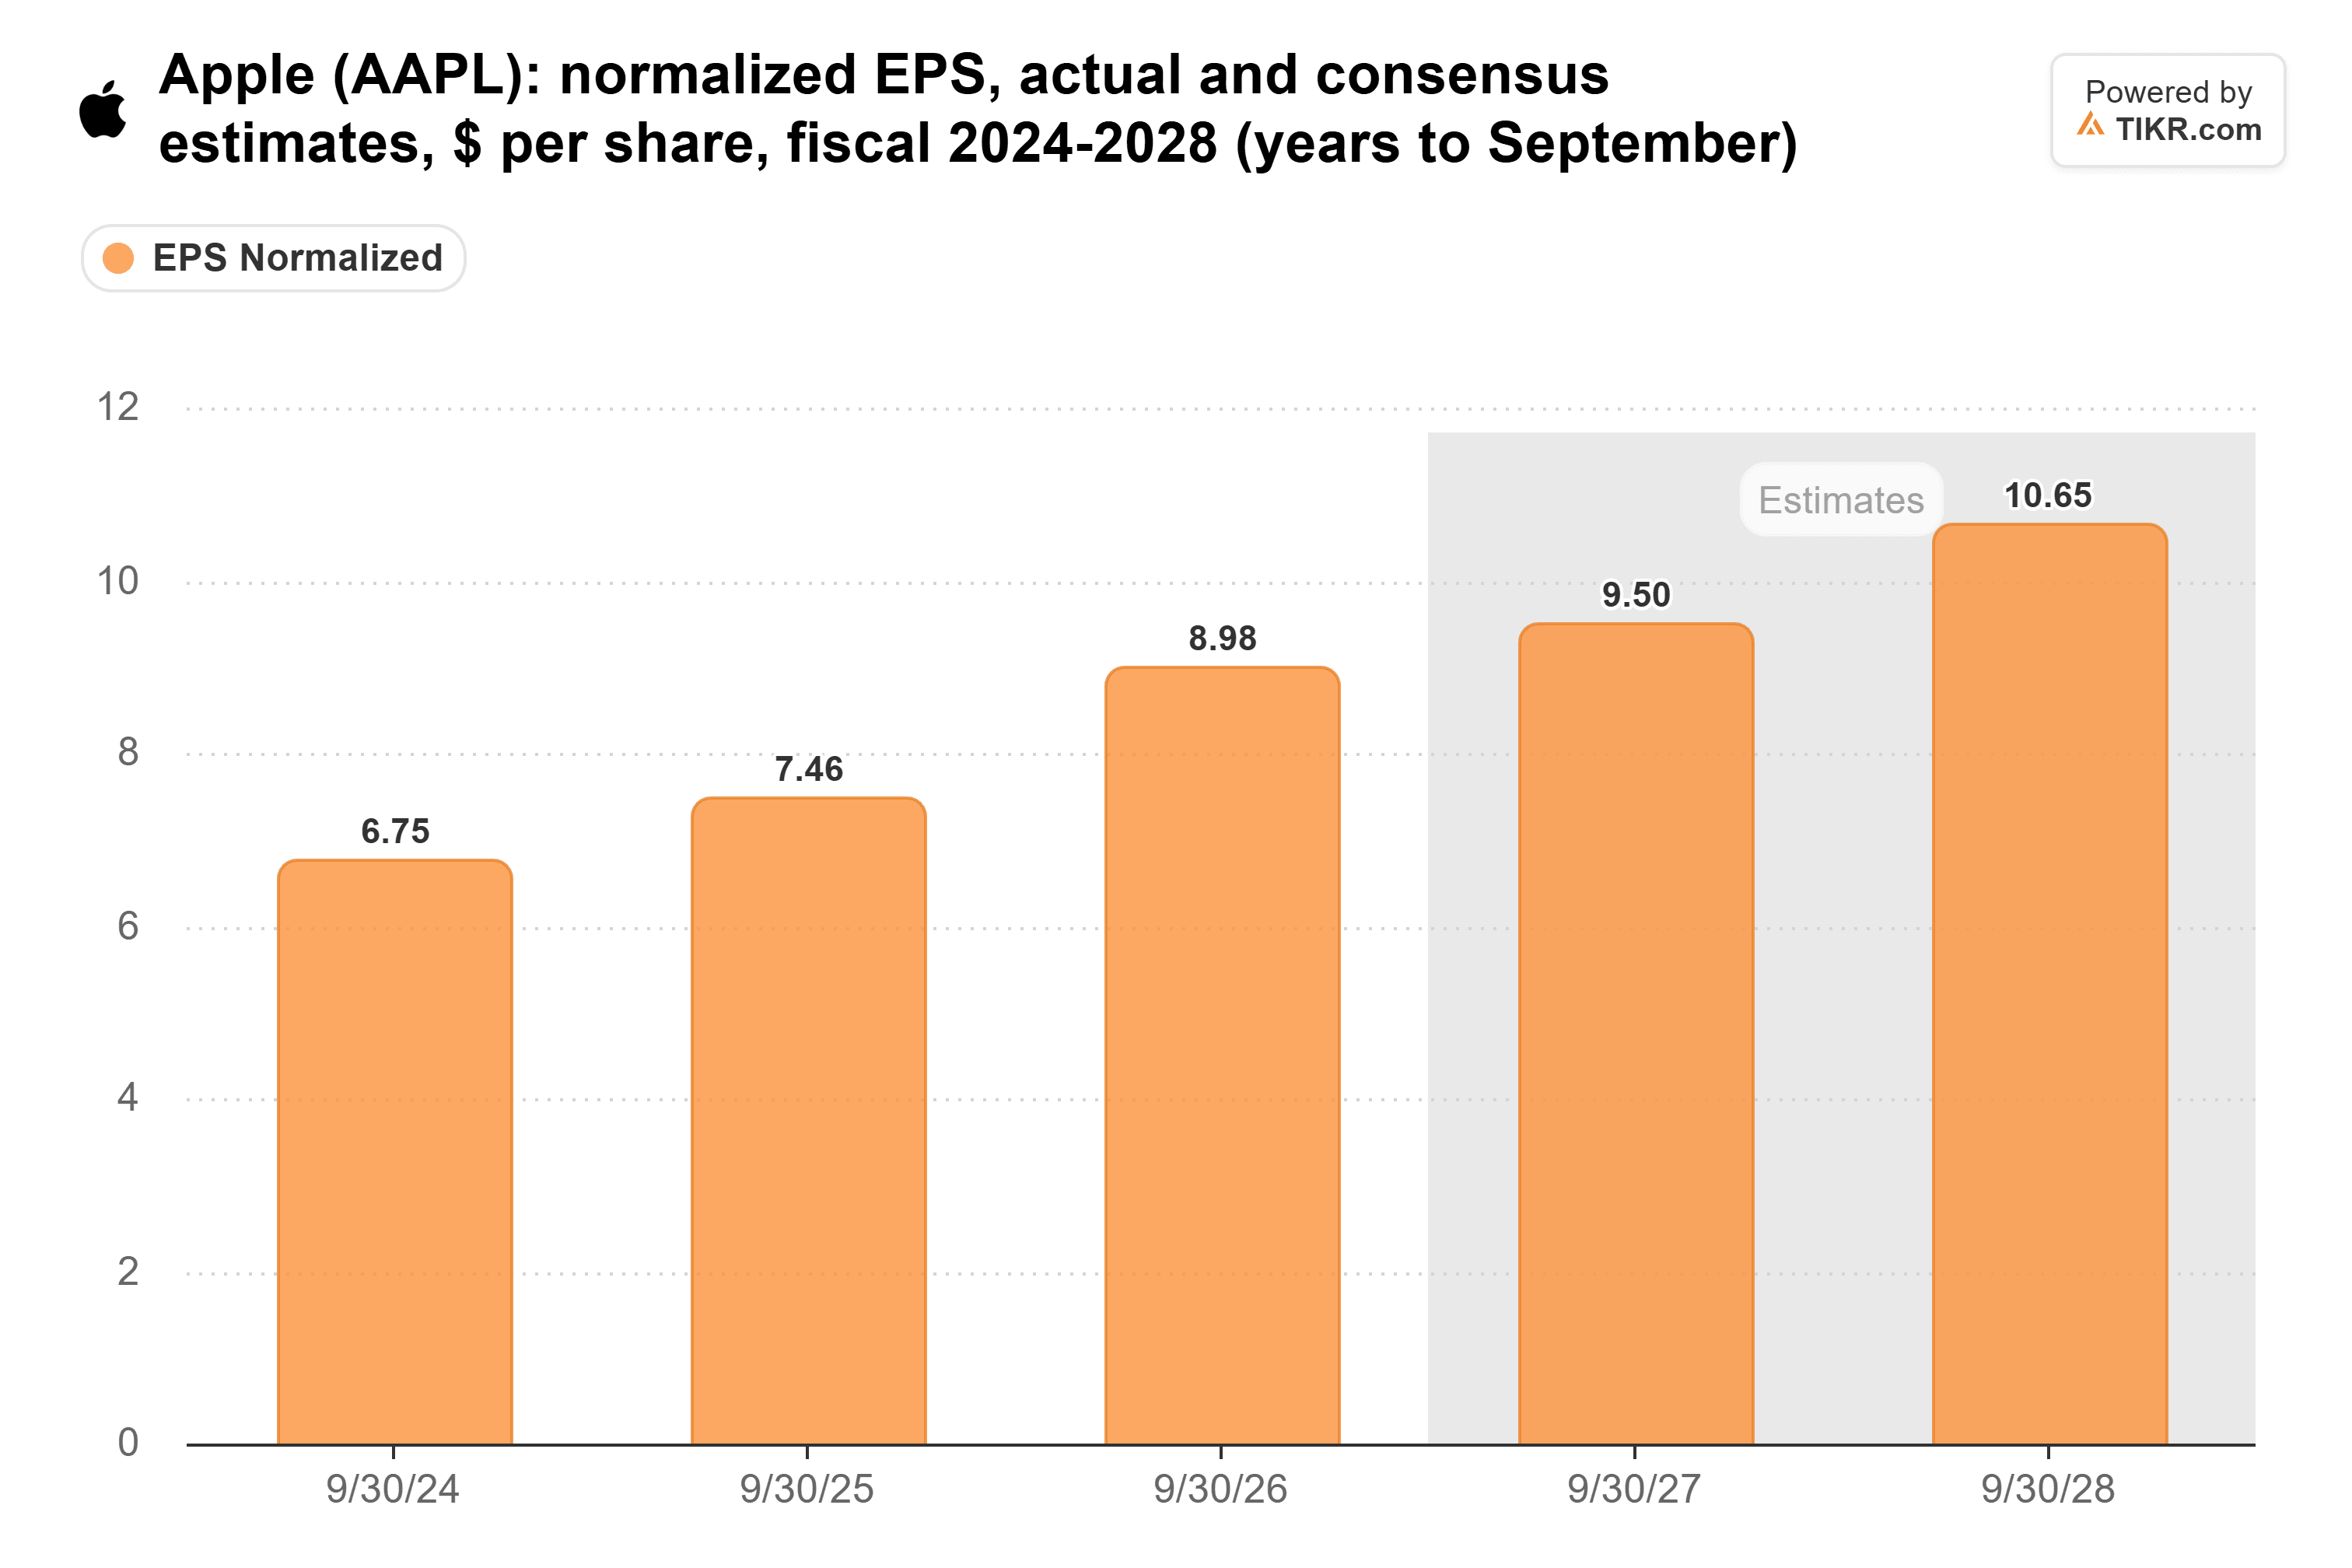
Apple guided December-quarter gross margin to 45% to 46%, down from 47.9% in September (about 46.9% without tariff refunds), as memory prices keep climbing. I wouldn’t count on those estimates moving up soon.
At 36x forward earnings on Nov. 5, Apple trades nearly 50% above its 10-year average of 24x, just under its 38x peak on Oct. 22.
The Cash Is What Investors Are Buying
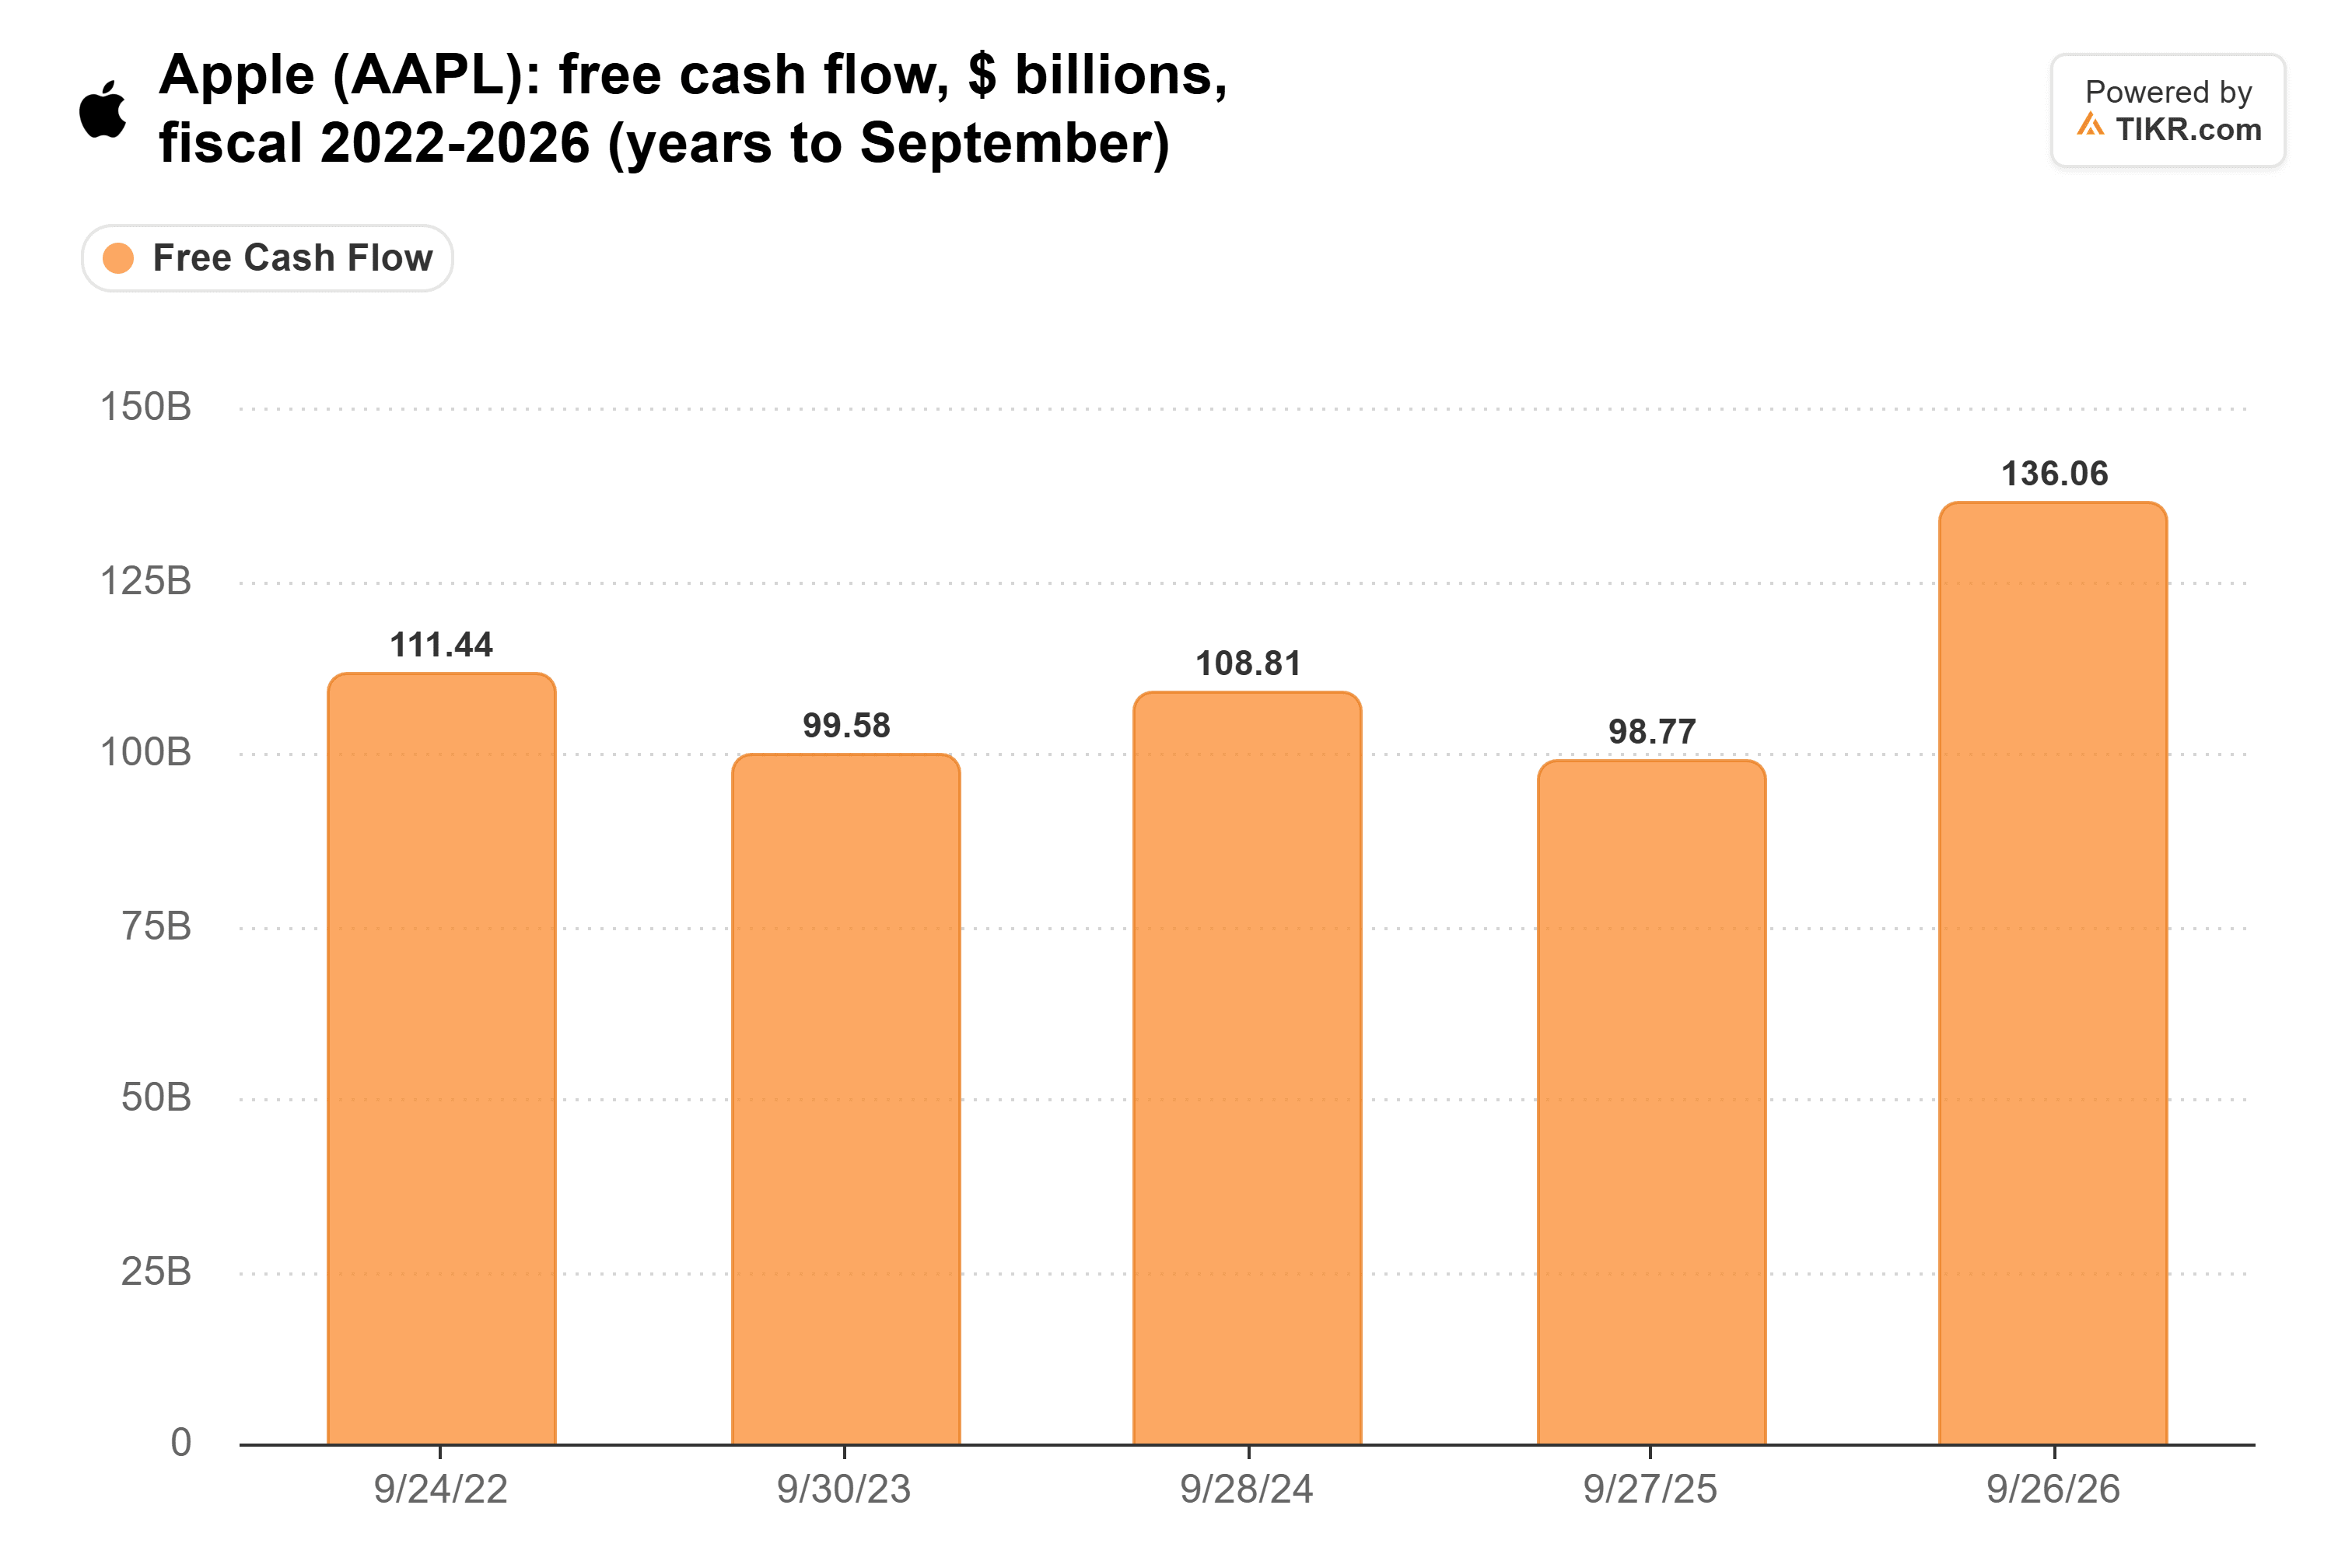
Free cash flow reached $136.1 billion in fiscal 2026, up 38% from $98.8 billion, helped by low capex and, in part, lower cash taxes.
Apple Needs the AI Trade to Stay Scary
That premium depends on big tech’s AI spending looking like a mistake. If Microsoft’s and Alphabet’s data centers start producing the cash investors are waiting for, the reason to hide in Apple fades, and a 36x multiple can shrink a lot faster than 6% earnings growth can make up.
Apple also depends on Alphabet in a second way. Google pays Apple to be Safari’s default search engine, and Gurman expects that revenue share to come down as AI eats into those searches. Apple guided Services growth to 8% to 9% for the December quarter, down from 10%.
Apple’s discipline is real, and the token caps show management means it. But at 36x, with earnings growth slowing to single digits and memory squeezing margins, I’d wait for a better price.
The December-quarter report, due in late January, will show whether gross margin holds at 45% to 46% and whether Services growth stops slowing.
So What Is Apple Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Apple could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!