Key Takeaways
- Apple is the best-performing Magnificent Seven stock this year, and Josh Brown calls it “literally the trade of the year” as investors sell NVIDIA and memory stocks.
- Apple’s capital spending fell to $9.0 billion in fiscal 2026, under 2% of revenue, while its big tech peers pour cash into AI data centers.
- Investors are paying 38x forward earnings for that safety, a hair below Apple’s 10-year high, while analysts expect EPS to grow about 5% in fiscal 2027.
- The business looks as dependable as ever, but at this multiple the stock leans on a rotation that could reverse if AI hardware stocks bounce.
Whenever the AI trade has stumbled this year, investors have kept buying the same stock: Apple (AAPL).
It’s the best-performing Magnificent Seven stock of 2026, and it kept climbing as investors dumped NVIDIA (NVDA) and the memory stocks.
Ritholtz Wealth Management CEO Josh Brown summed it up on the Nov. 12 Halftime Report:
“This is the anti-AI large cap tech trade and it’s literally the trade of the year.”
His reasoning: investors who want to stay in tech without the swings of the hyperscaler trade are betting Apple’s phones will sell and the company will execute. Then he named the catch himself: “Maybe it doesn’t deserve the multiple it’s now trading at.”
A Near-Record Multiple for Slower Growth
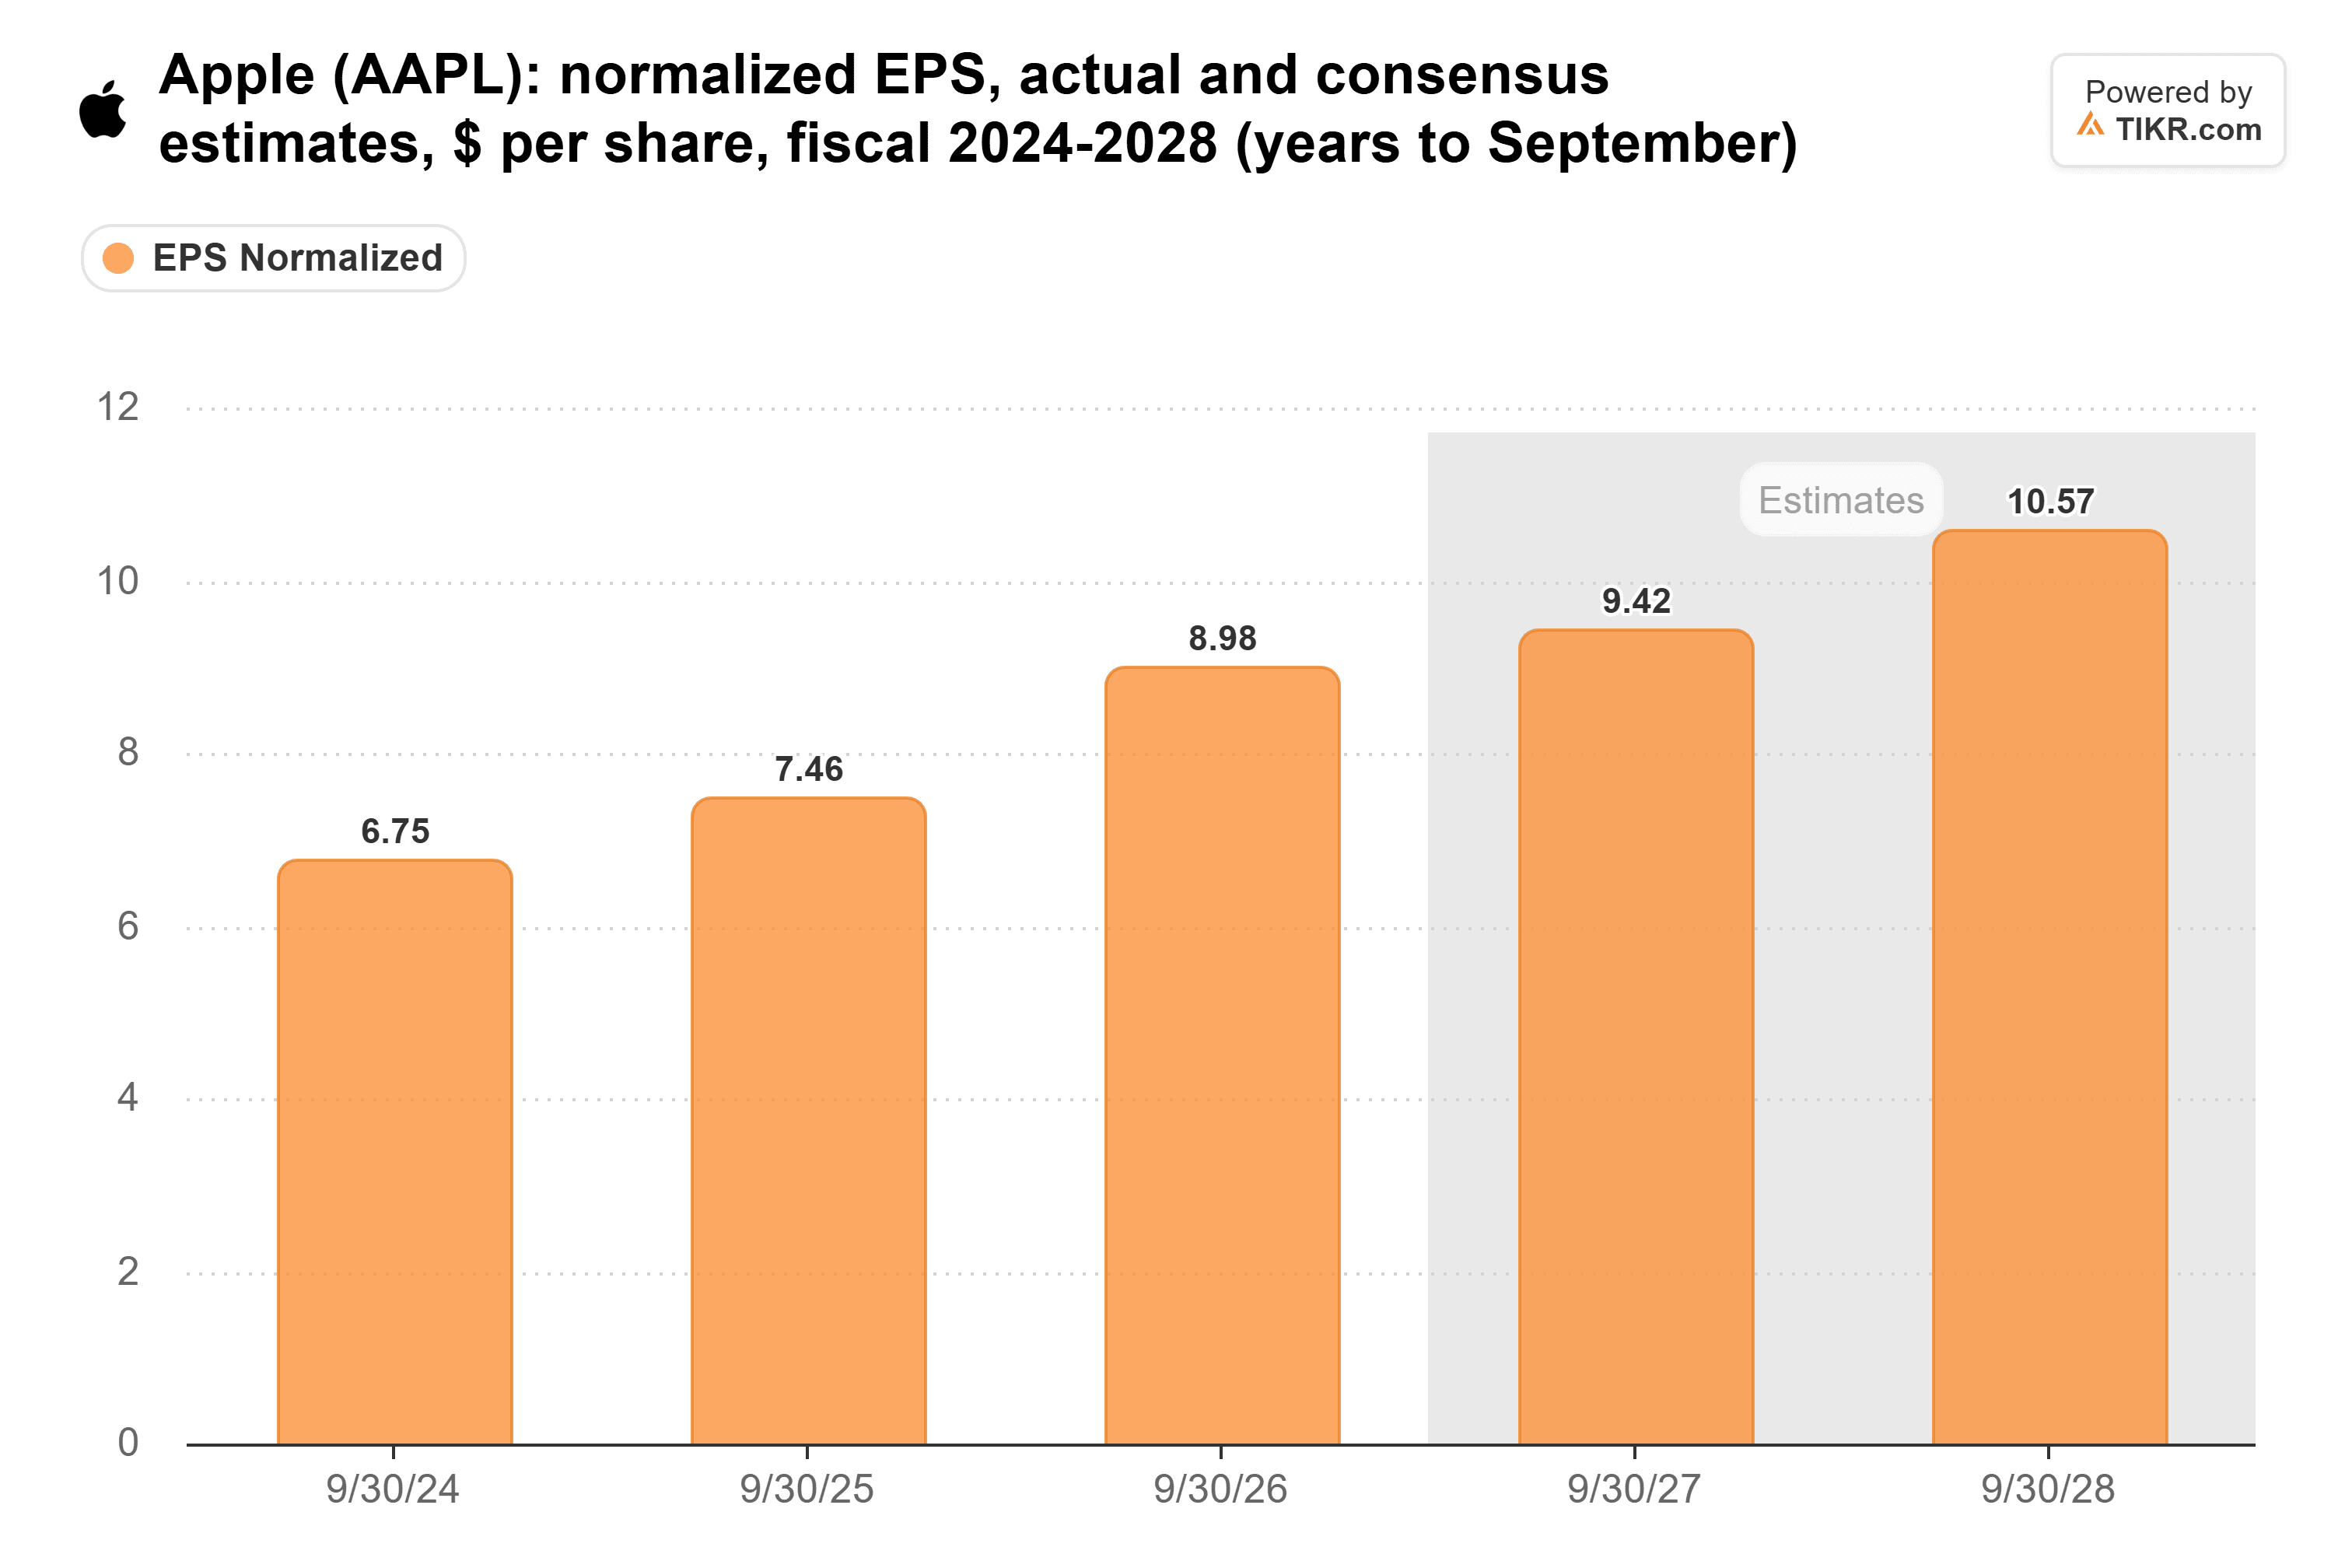
Apple’s earnings are still growing, just more slowly. Normalized EPS jumped 20% to $8.98 in fiscal 2026 (the year ended in September). Analysts expect about 5% growth to $9.42 in fiscal 2027, then about 12% to $10.57 in fiscal 2028.
Memory costs are part of the reason. Tim Cook, on his final earnings call as CEO in July, called it “a 100-year flood on the memory pricing.”
The multiple has gone the other way. Apple trades at 38x forward earnings, a hair below the 10-year high it set on Oct. 22 and well above its 25x average over that stretch.
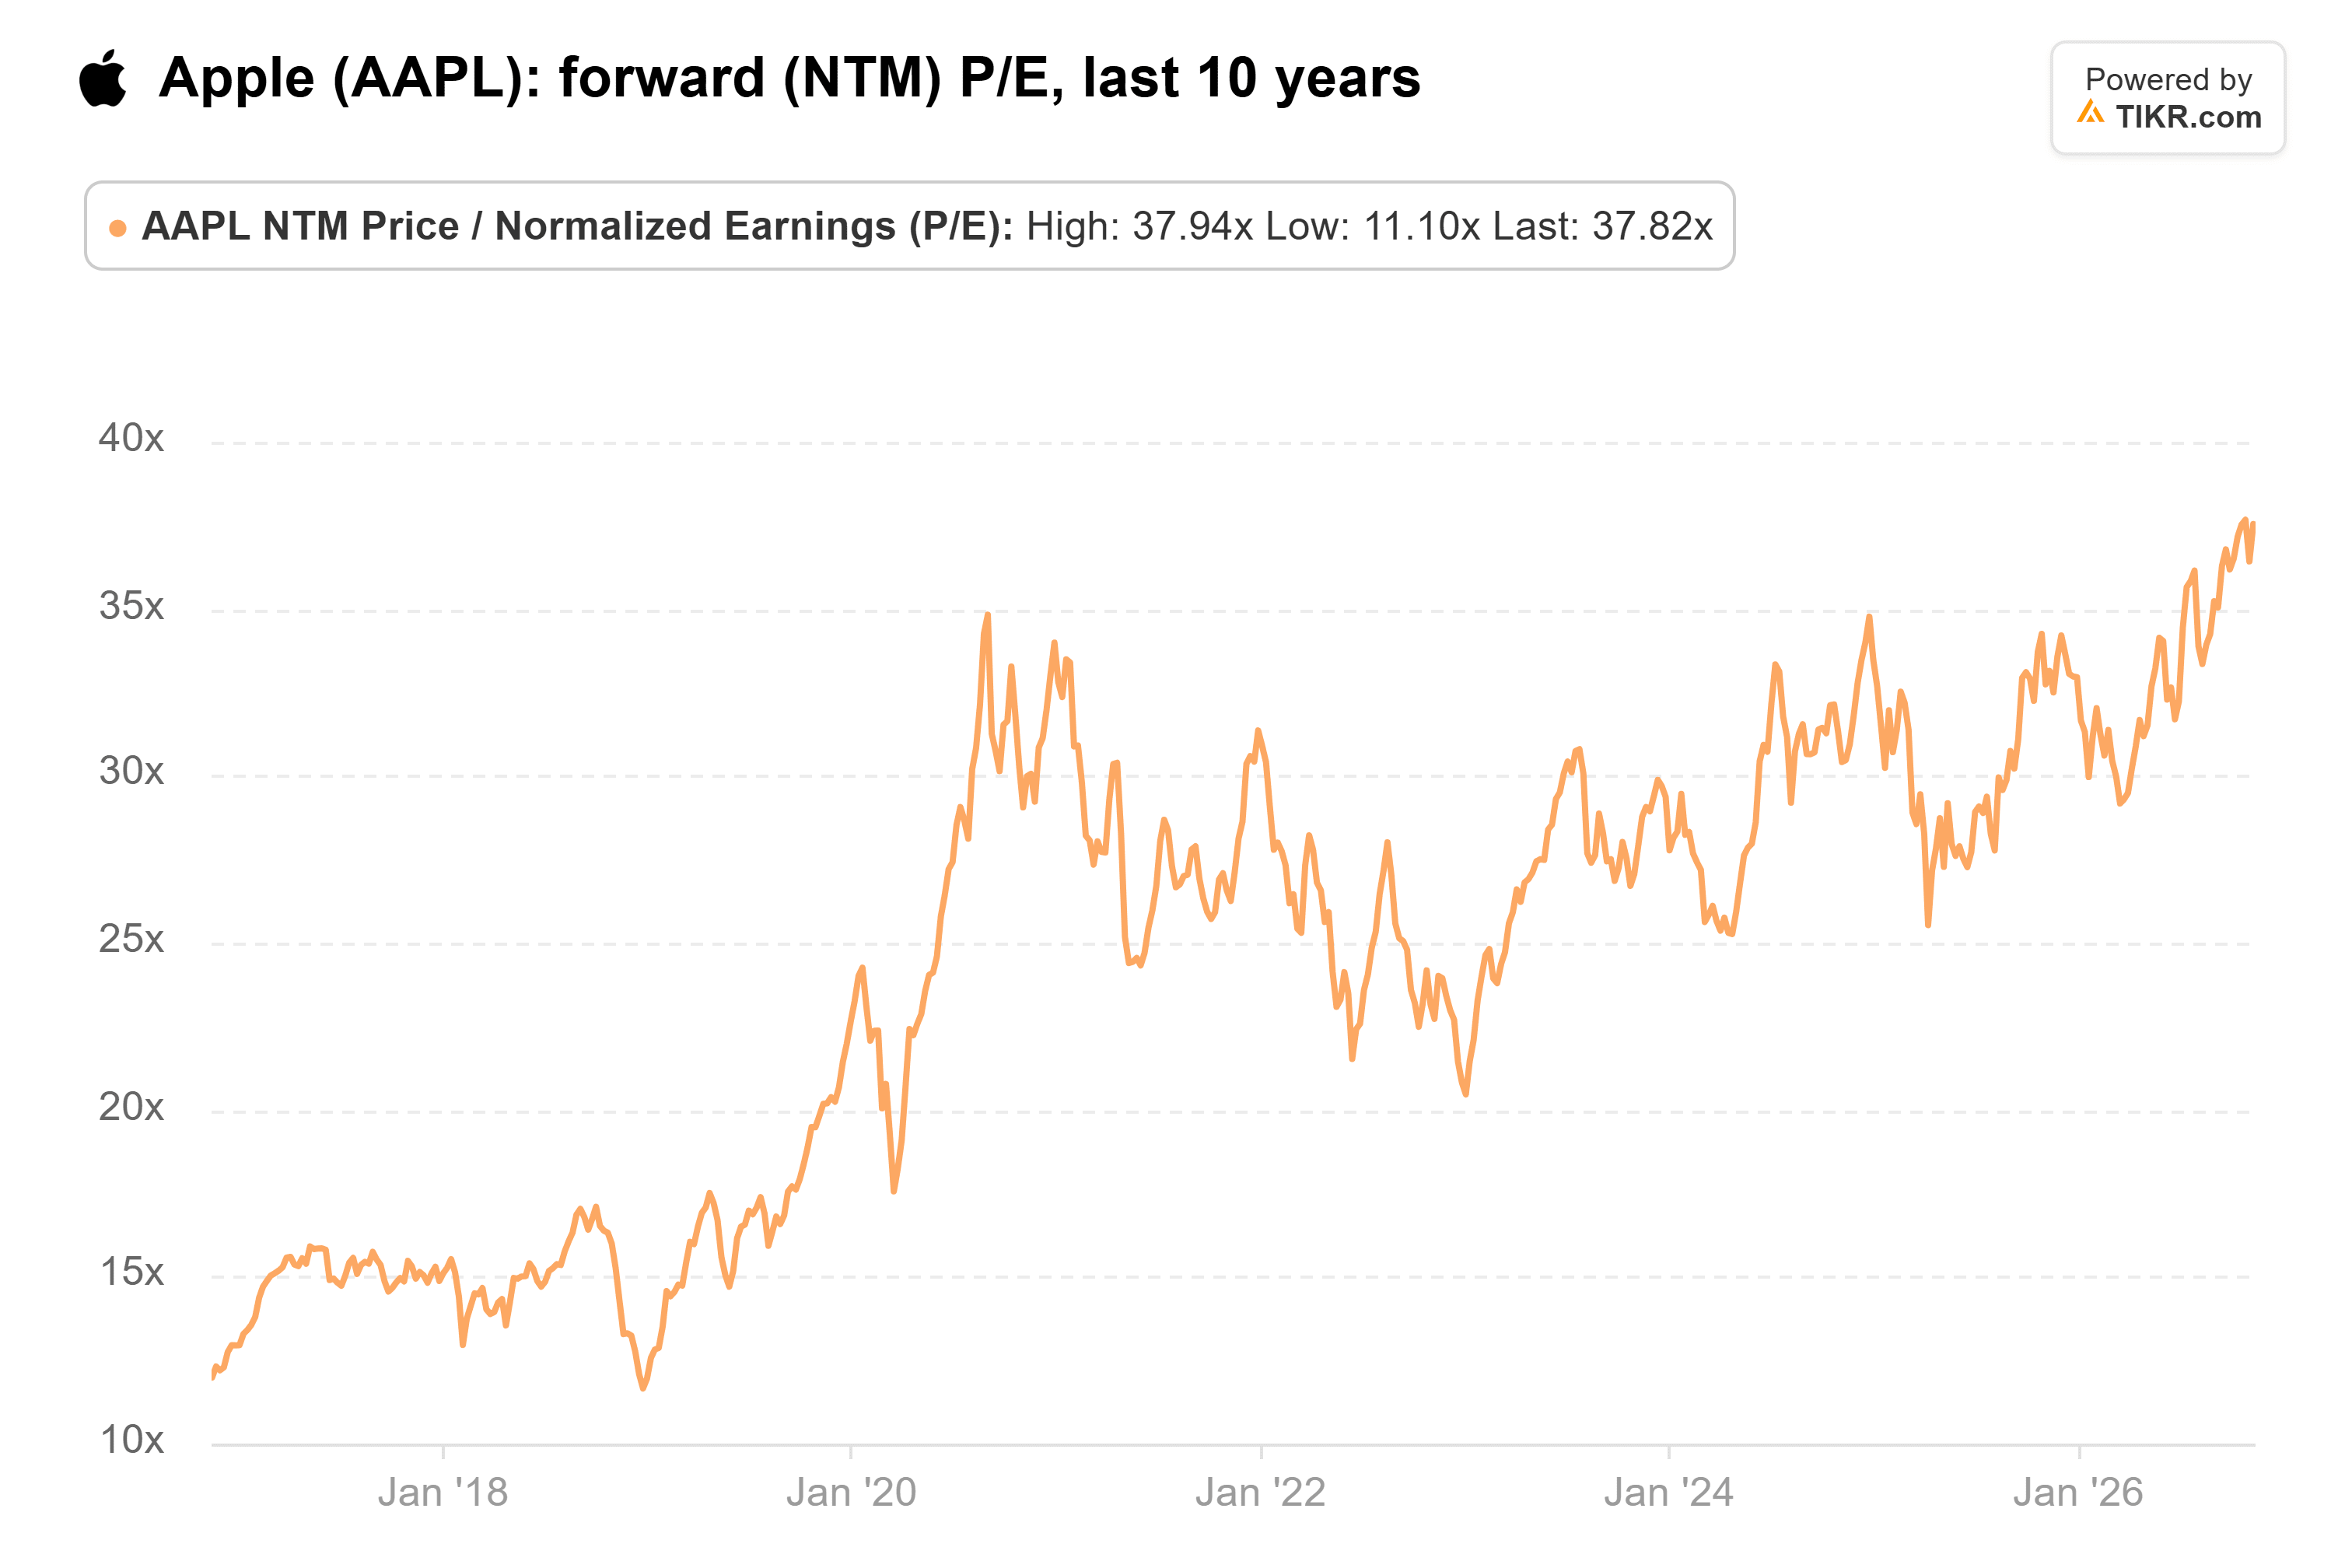
That’s a near-record price for EPS growth of about 8.5% a year through fiscal 2028, slower than the roughly 12% a year Apple delivered over the 10 fiscal years through 2025.
Apple’s Capex Went the Other Way
What the premium buys is a company spending more on AI while spending less on buildings and equipment. Apple’s capital spending fell 29% to $9.0 billion in fiscal 2026, the lowest in five years and under 2% of revenue.
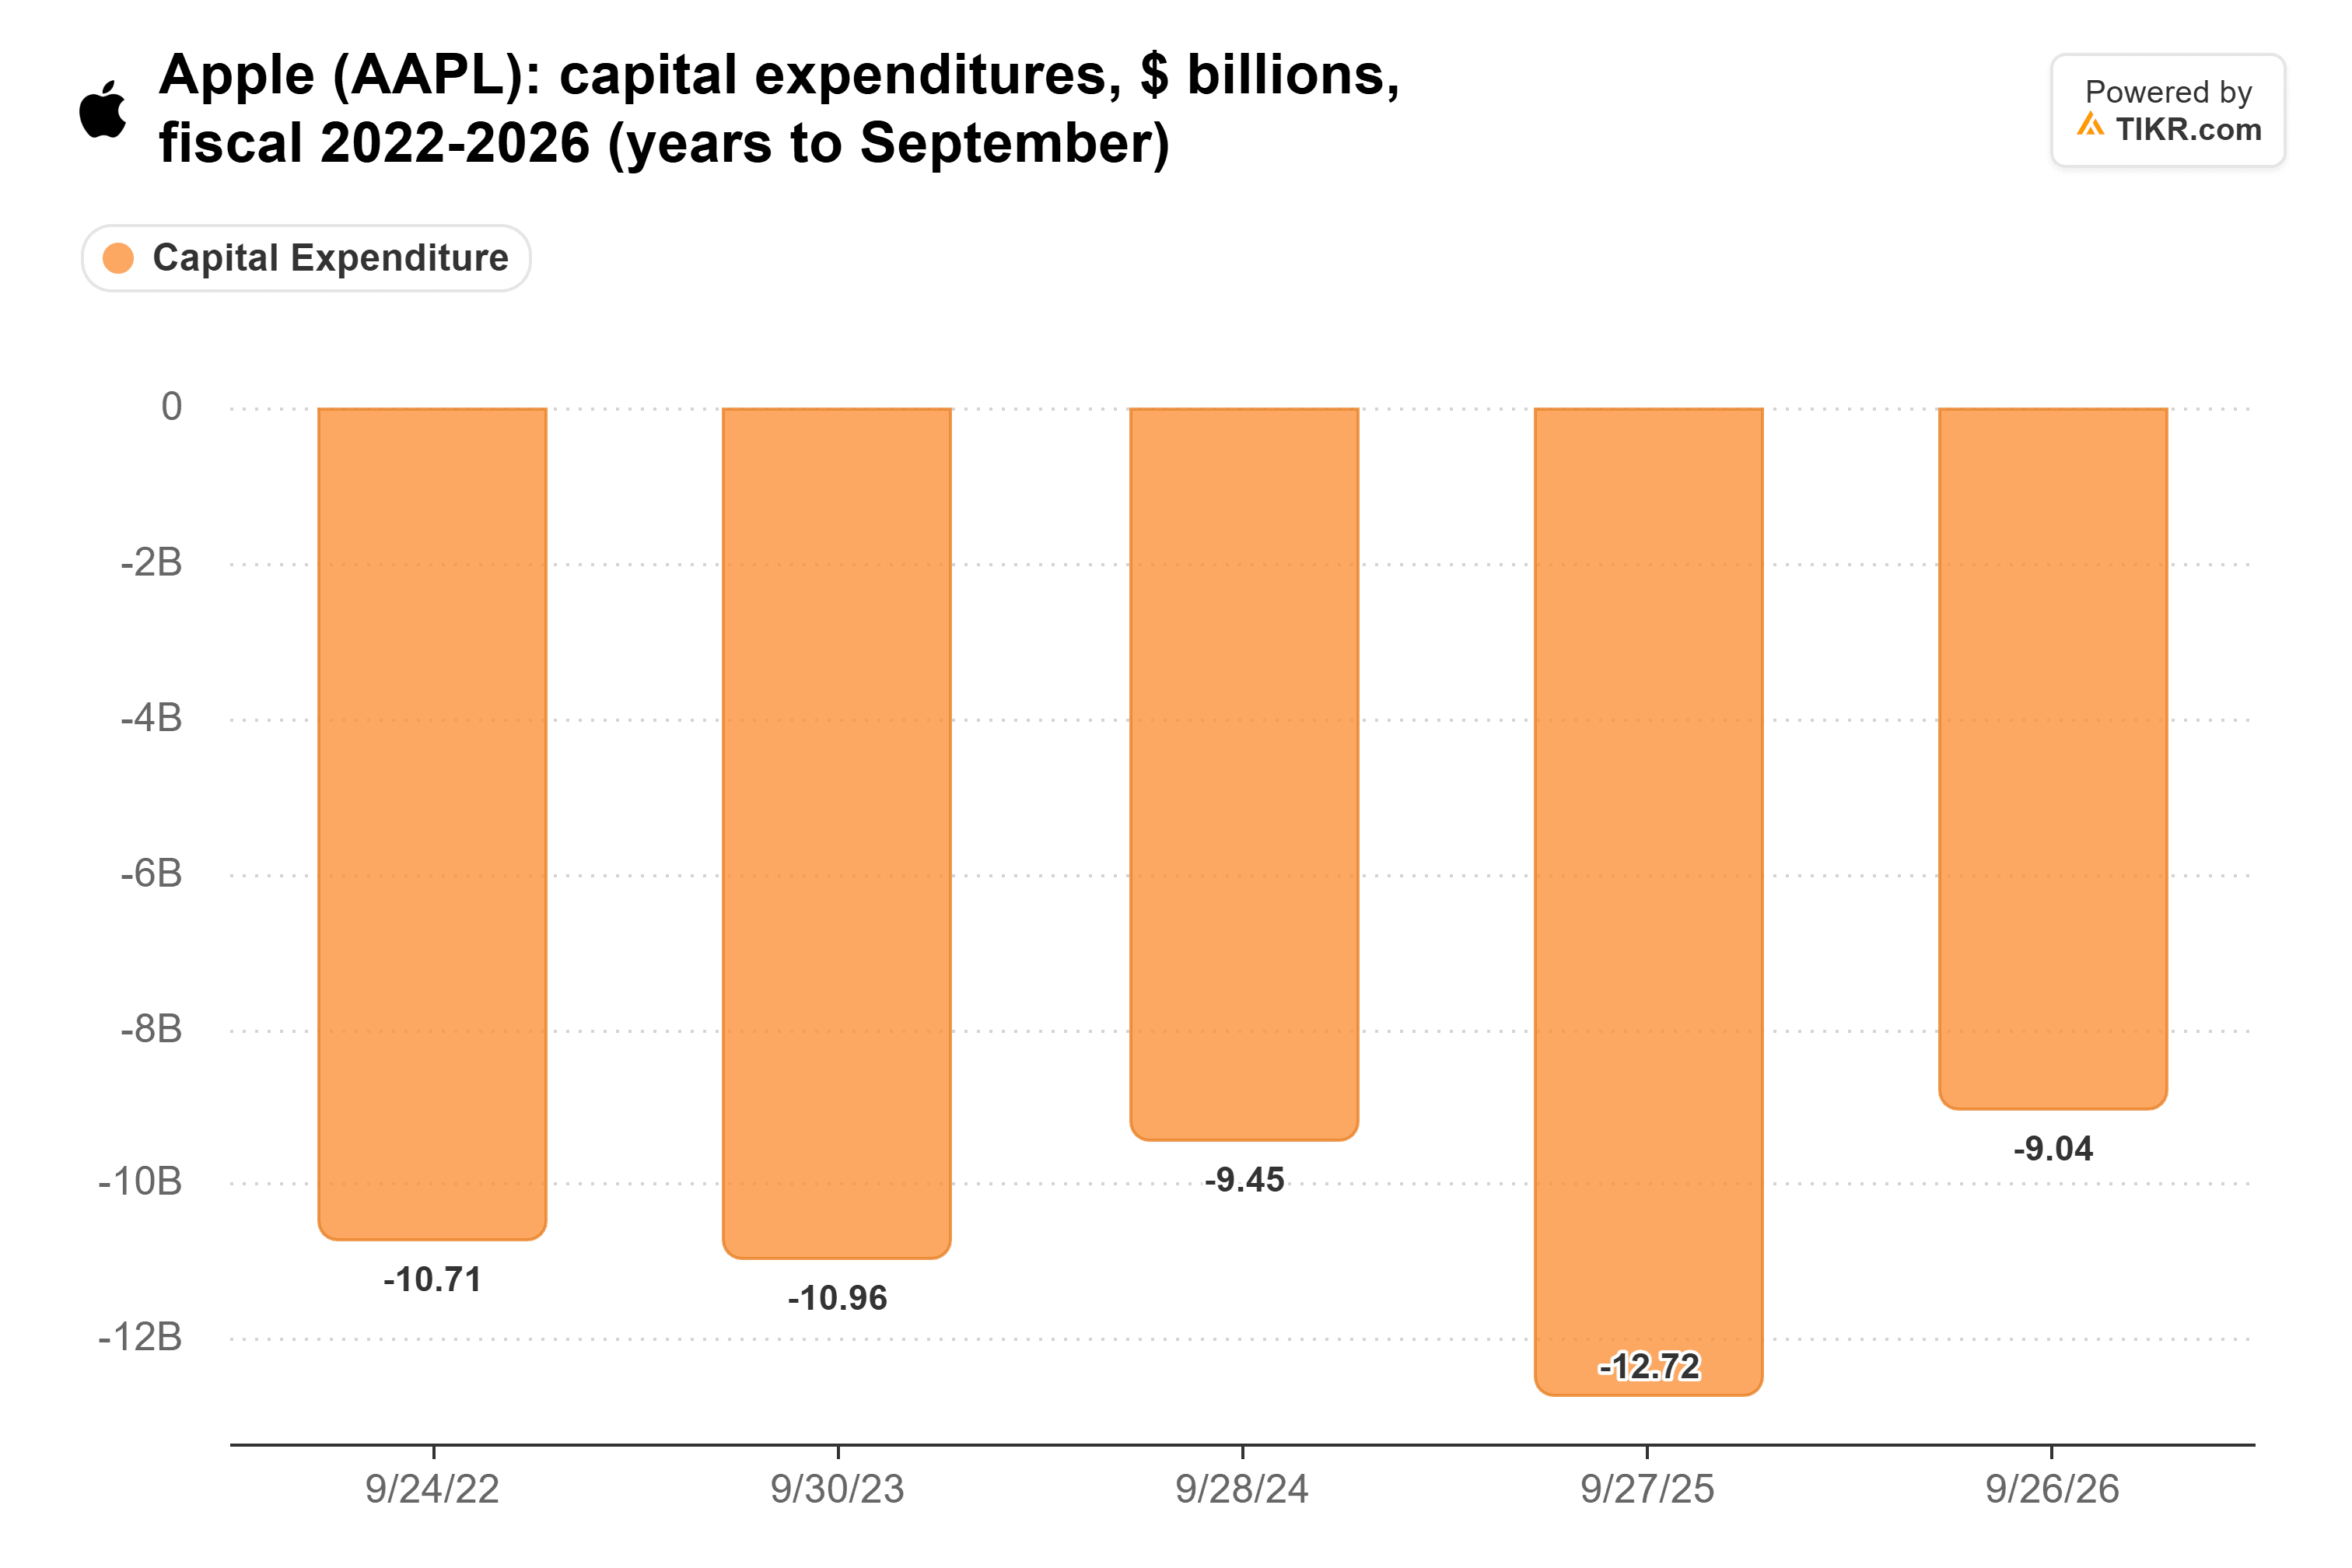
Apple still spends on AI. R&D rose 32% to $45.8 billion, mainly on higher infrastructure costs including AI, according to its 10-K, and its next foundation models are built with Google’s Gemini. Even so, free cash flow (operating cash flow minus capital spending) rose 38% to $136.1 billion. With capex falling, Apple is adding far less owned infrastructure that could sour if the build-out proves overdone.
TIKR Tracks 45 Analysts on Apple. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Apple, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Apple’s Analyst Ratings
Why I Wouldn’t Chase Apple at 38x
Much of that premium comes from investors running away from something else. Brown has also argued that NVIDIA has been cheap for three years. Once the AI trade steadies, it won’t take much for that money to go back.
Apple’s business is about as dependable as big tech gets, but 38x leaves little room for a 5% earnings year. I’d want the multiple to drift back toward its average, or growth to pick up, before buying.
A strong holiday quarter would help. UBS expects December-quarter iPhone revenue to rise nearly 12% to a record $95 billion, even with units down 3%. Apple is expected to report in late January.
So What Is Apple Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Apple could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!