


Key Takeaways
- Amazon CEO Andy Jassy said Nvidia’s business “will be very strong” for as long as he can foresee, the same day Nvidia reported 103% revenue growth.
- Amazon’s own chips are growing triple digits, but Jassy expects plenty of AWS customers to keep asking for Nvidia.
- Amazon’s capital spending rose to $132 billion in 2025, and management expects about $220 billion of cash capex this year.
- Nvidia’s gross margin was 74.9% over the first nine months of this fiscal year, and Amazon’s 2027 spending outlook in early February is the next test.
It’s been a rough week for Nvidia (NVDA). Jensen Huang resigned as CEO on Nov. 12, and on Tuesday the company reported its first quarter without him.
That same day, Amazon (AMZN) CEO Andy Jassy went on CNBC’s Halftime Report. He was asked whether a “wounded” Nvidia helps Amazon, which buys Nvidia’s chips and also makes its own.
“We just don’t think of it that way,” Jassy said, before adding:
“I believe NVIDIA’s business will be very strong for as long as I can foresee and we’ll be partners with them.”
That’s a generous take from a company whose own chips business is “wildly successful now and growing triple digits year over year,” in Jassy’s words. A few hours later, Nvidia reported third-quarter revenue of $115.8 billion, up 103% from a year ago.
TIKR tracks 63 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
Customers keep asking for Nvidia
For Nvidia shareholders, the more important line came when Jassy was asked whether Amazon’s role as an Nvidia customer is changing:
“We have a lot of customers who are going to ask to run on top of NVIDIA chips in our infrastructure for a very long time, as long as I can foresee.”
AWS customers pick the chips they run on, so Trainium has to win them over one at a time.
Amazon’s chips are also still small next to Nvidia’s. Jassy said Trainium and Graviton were running at over $25 billion a year combined as of Amazon’s second-quarter call. Nvidia’s data center business brought in $107.6 billion in its third quarter alone.
Analysts expect Nvidia’s revenue to keep climbing for years:
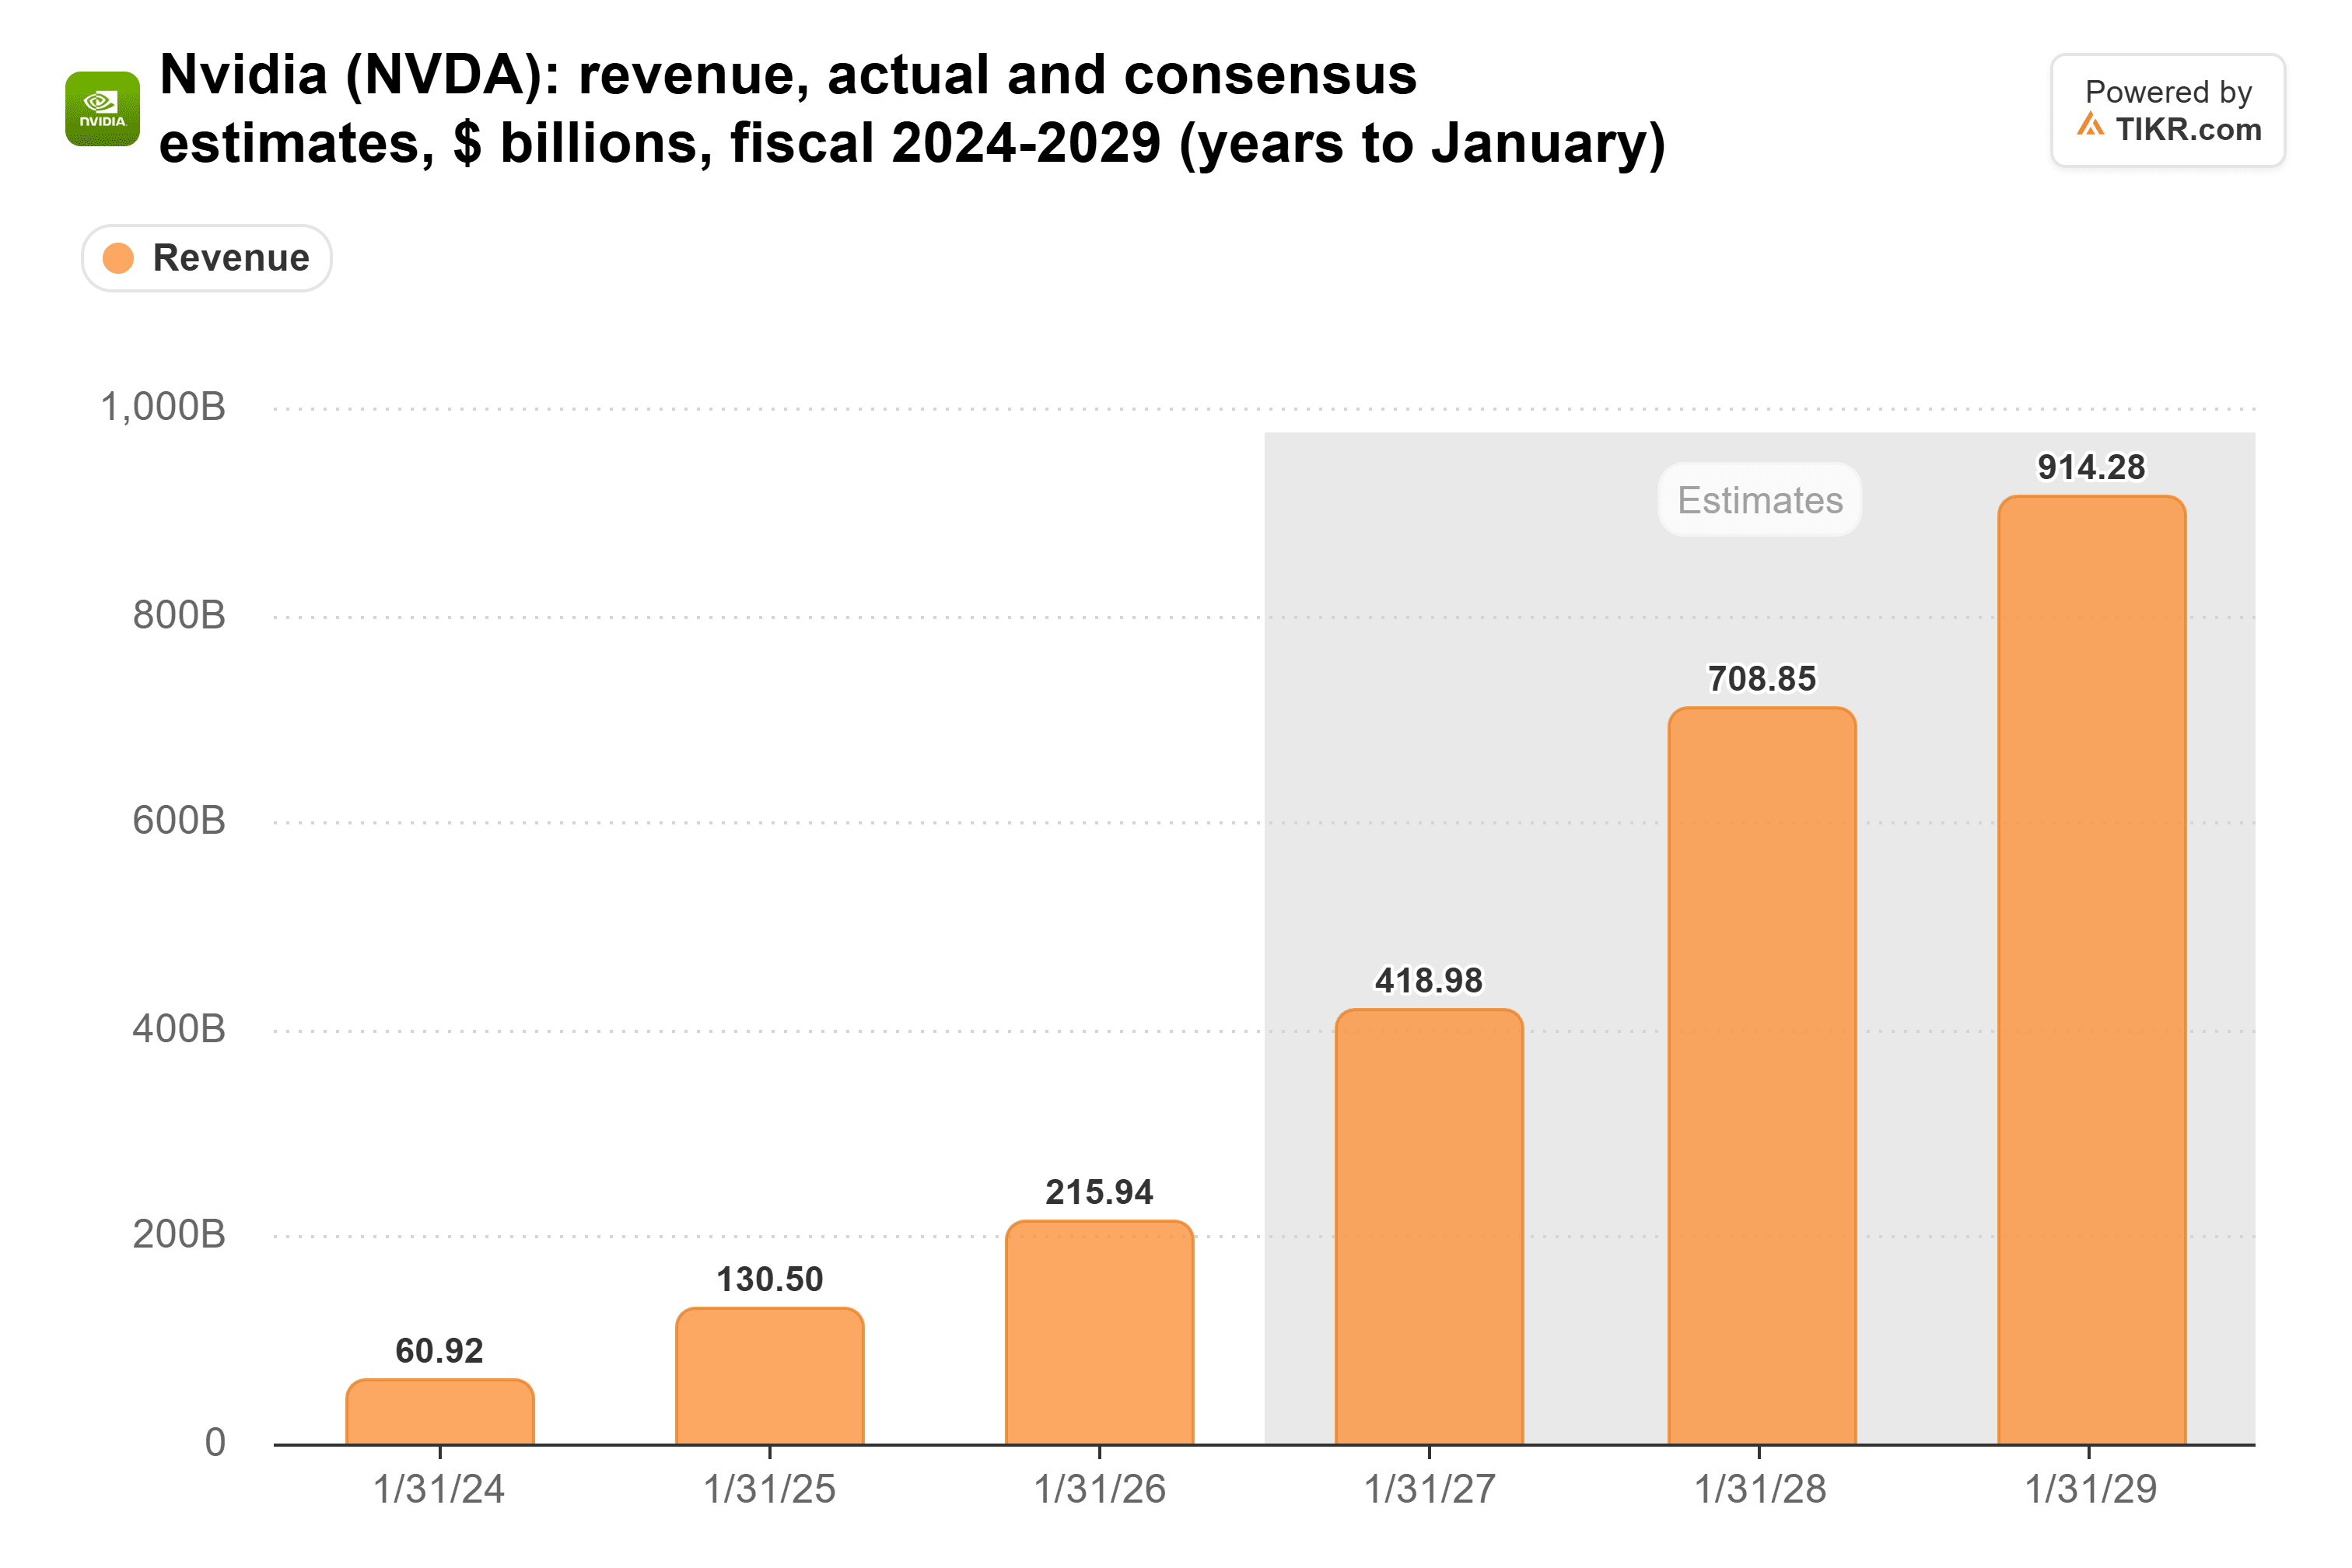
Nvidia’s fourth-quarter guide of $130 billion would bring this fiscal year to about $424 billion, a bit above the $419 billion analysts expect. Consensus has revenue reaching about $1.1 trillion three years later, though only nine analysts estimate that far out.
Trainium still takes a slice
Of course, every Trainium chip AWS installs fills a slot an Nvidia chip could have taken. Amazon’s second-quarter 10-Q shows that Anthropic’s latest AWS commitment, more than $100 billion over 10 years, includes obligations tied to Amazon’s own chips.
But that only costs Nvidia if the build stops growing, and Amazon’s capital spending has surged:
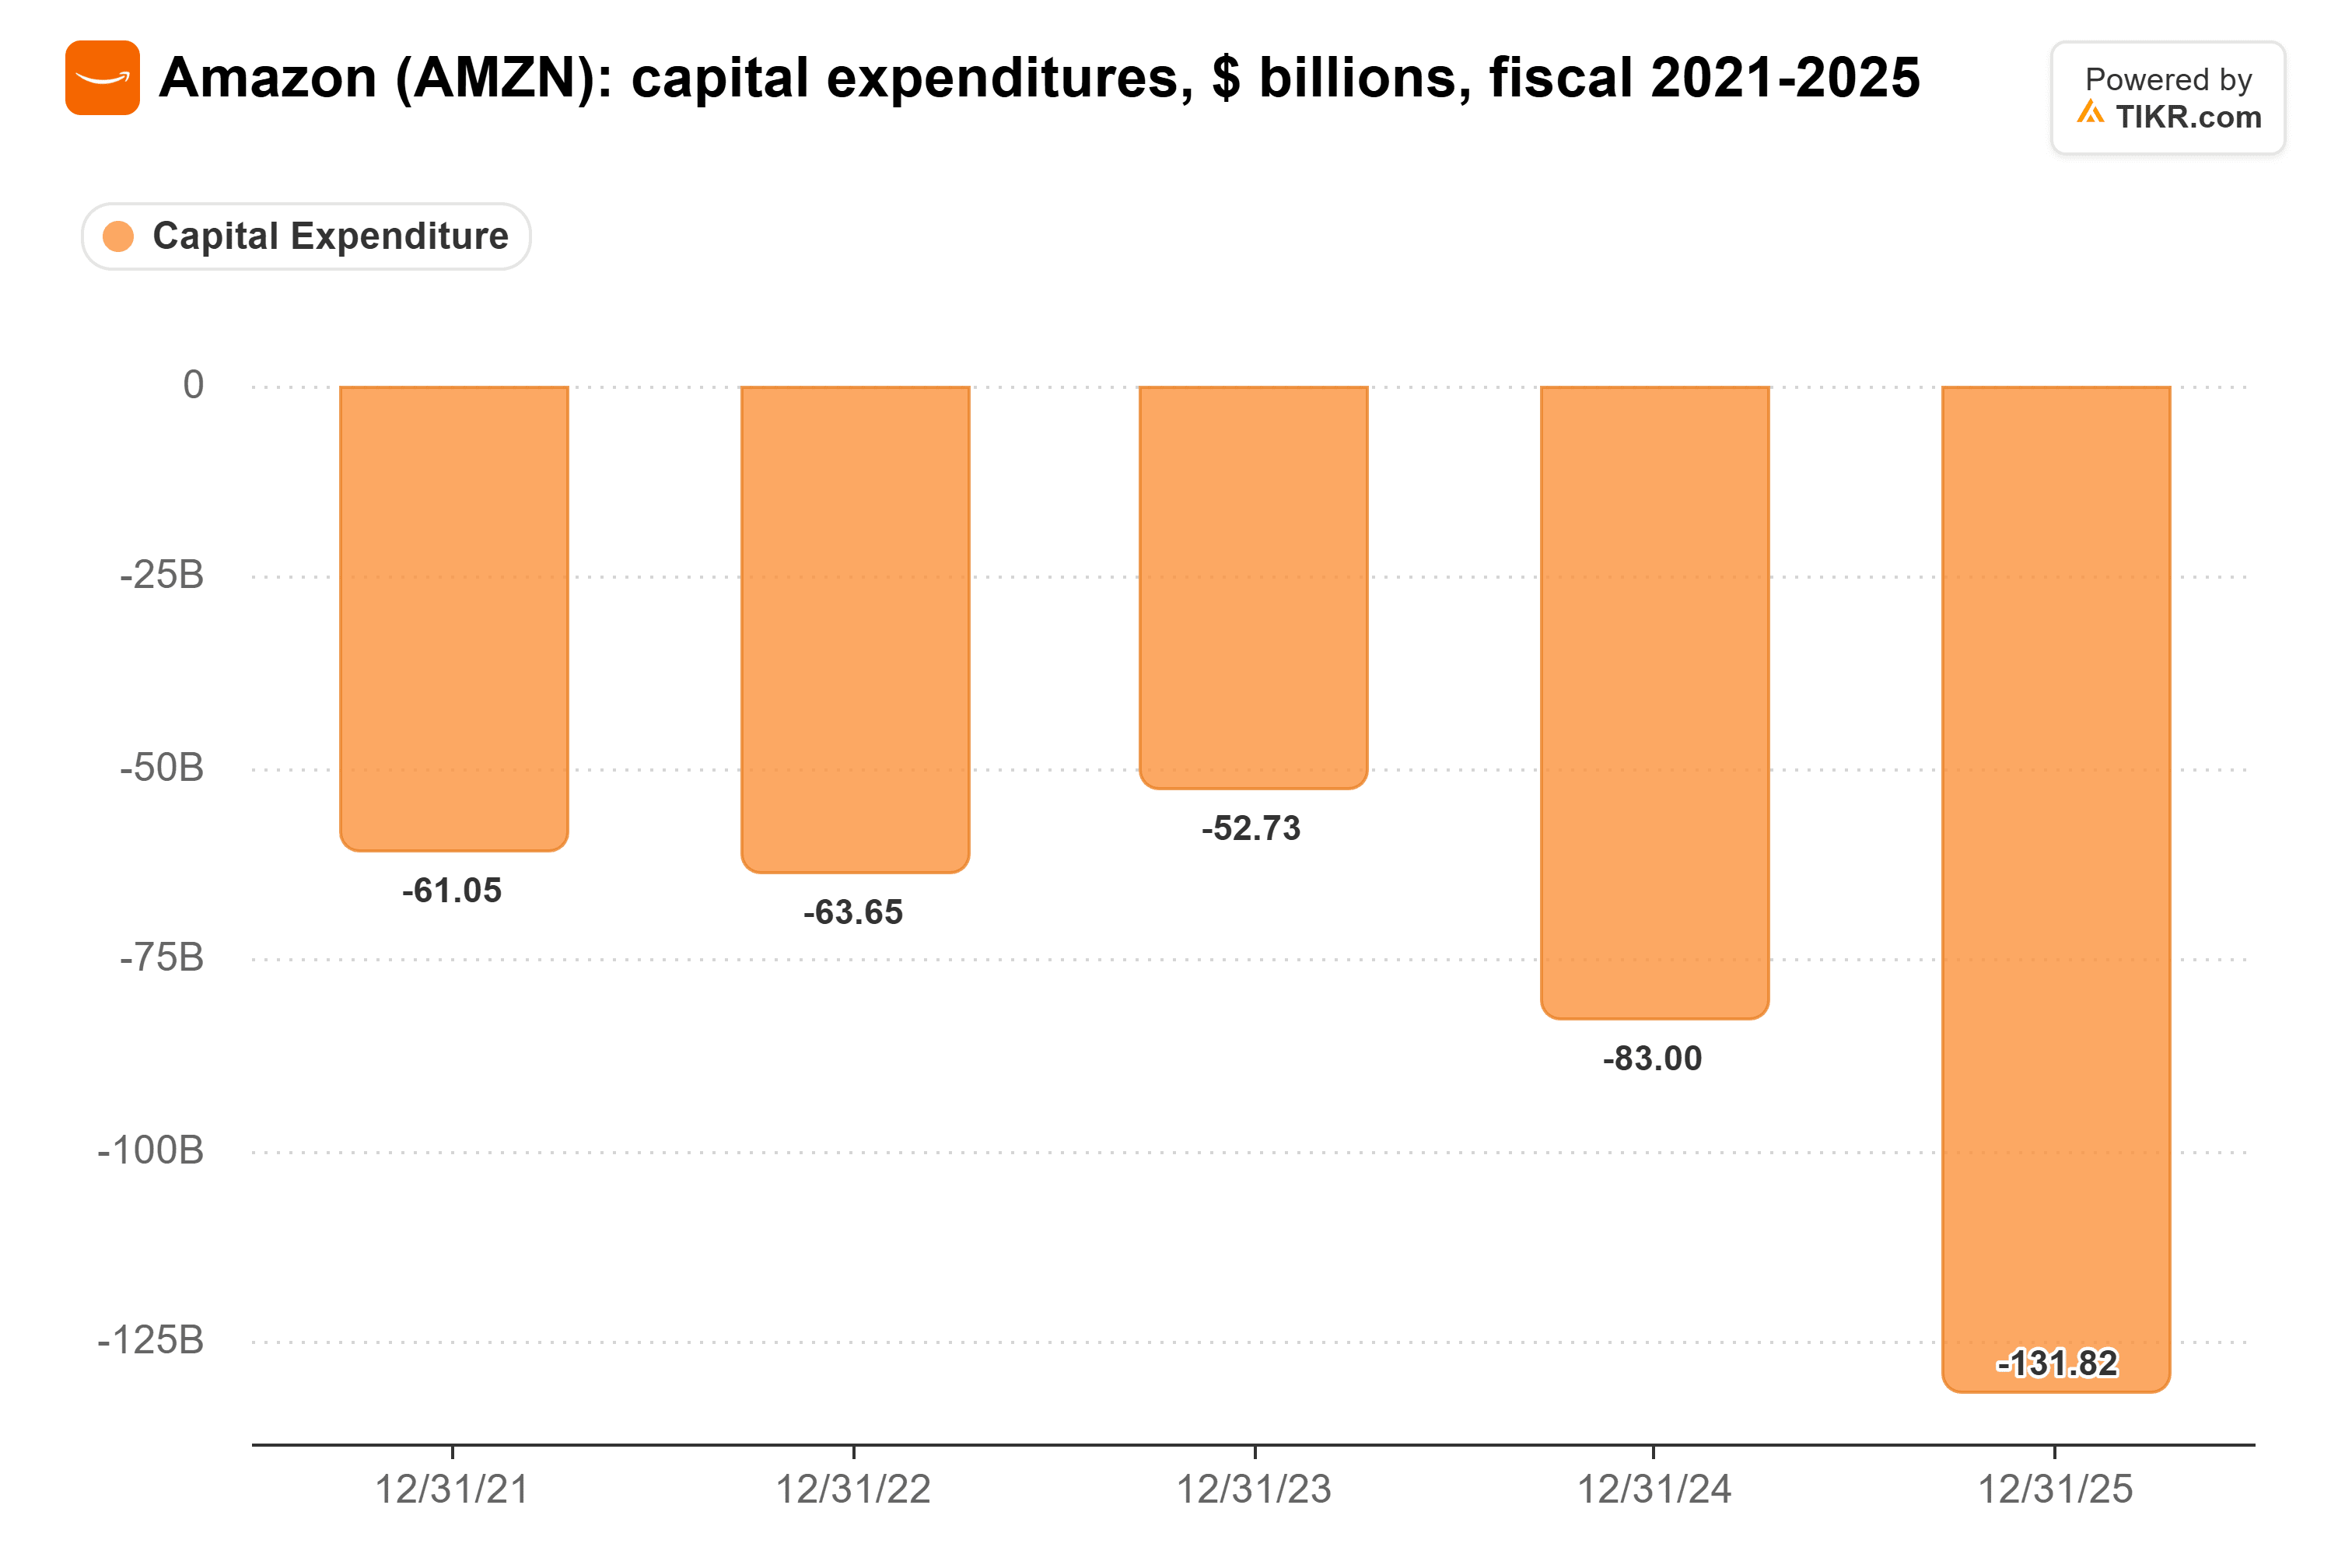
This year, management expects about $220 billion of cash capex. Even that may not be enough: AWS CEO Matt Garman expects capacity shortages for the next couple of years.
If custom chips were eating into Nvidia’s business, I’d expect to see it in Nvidia’s gross margin first. Instead, that margin has stayed above 70% in each of the last three fiscal years:
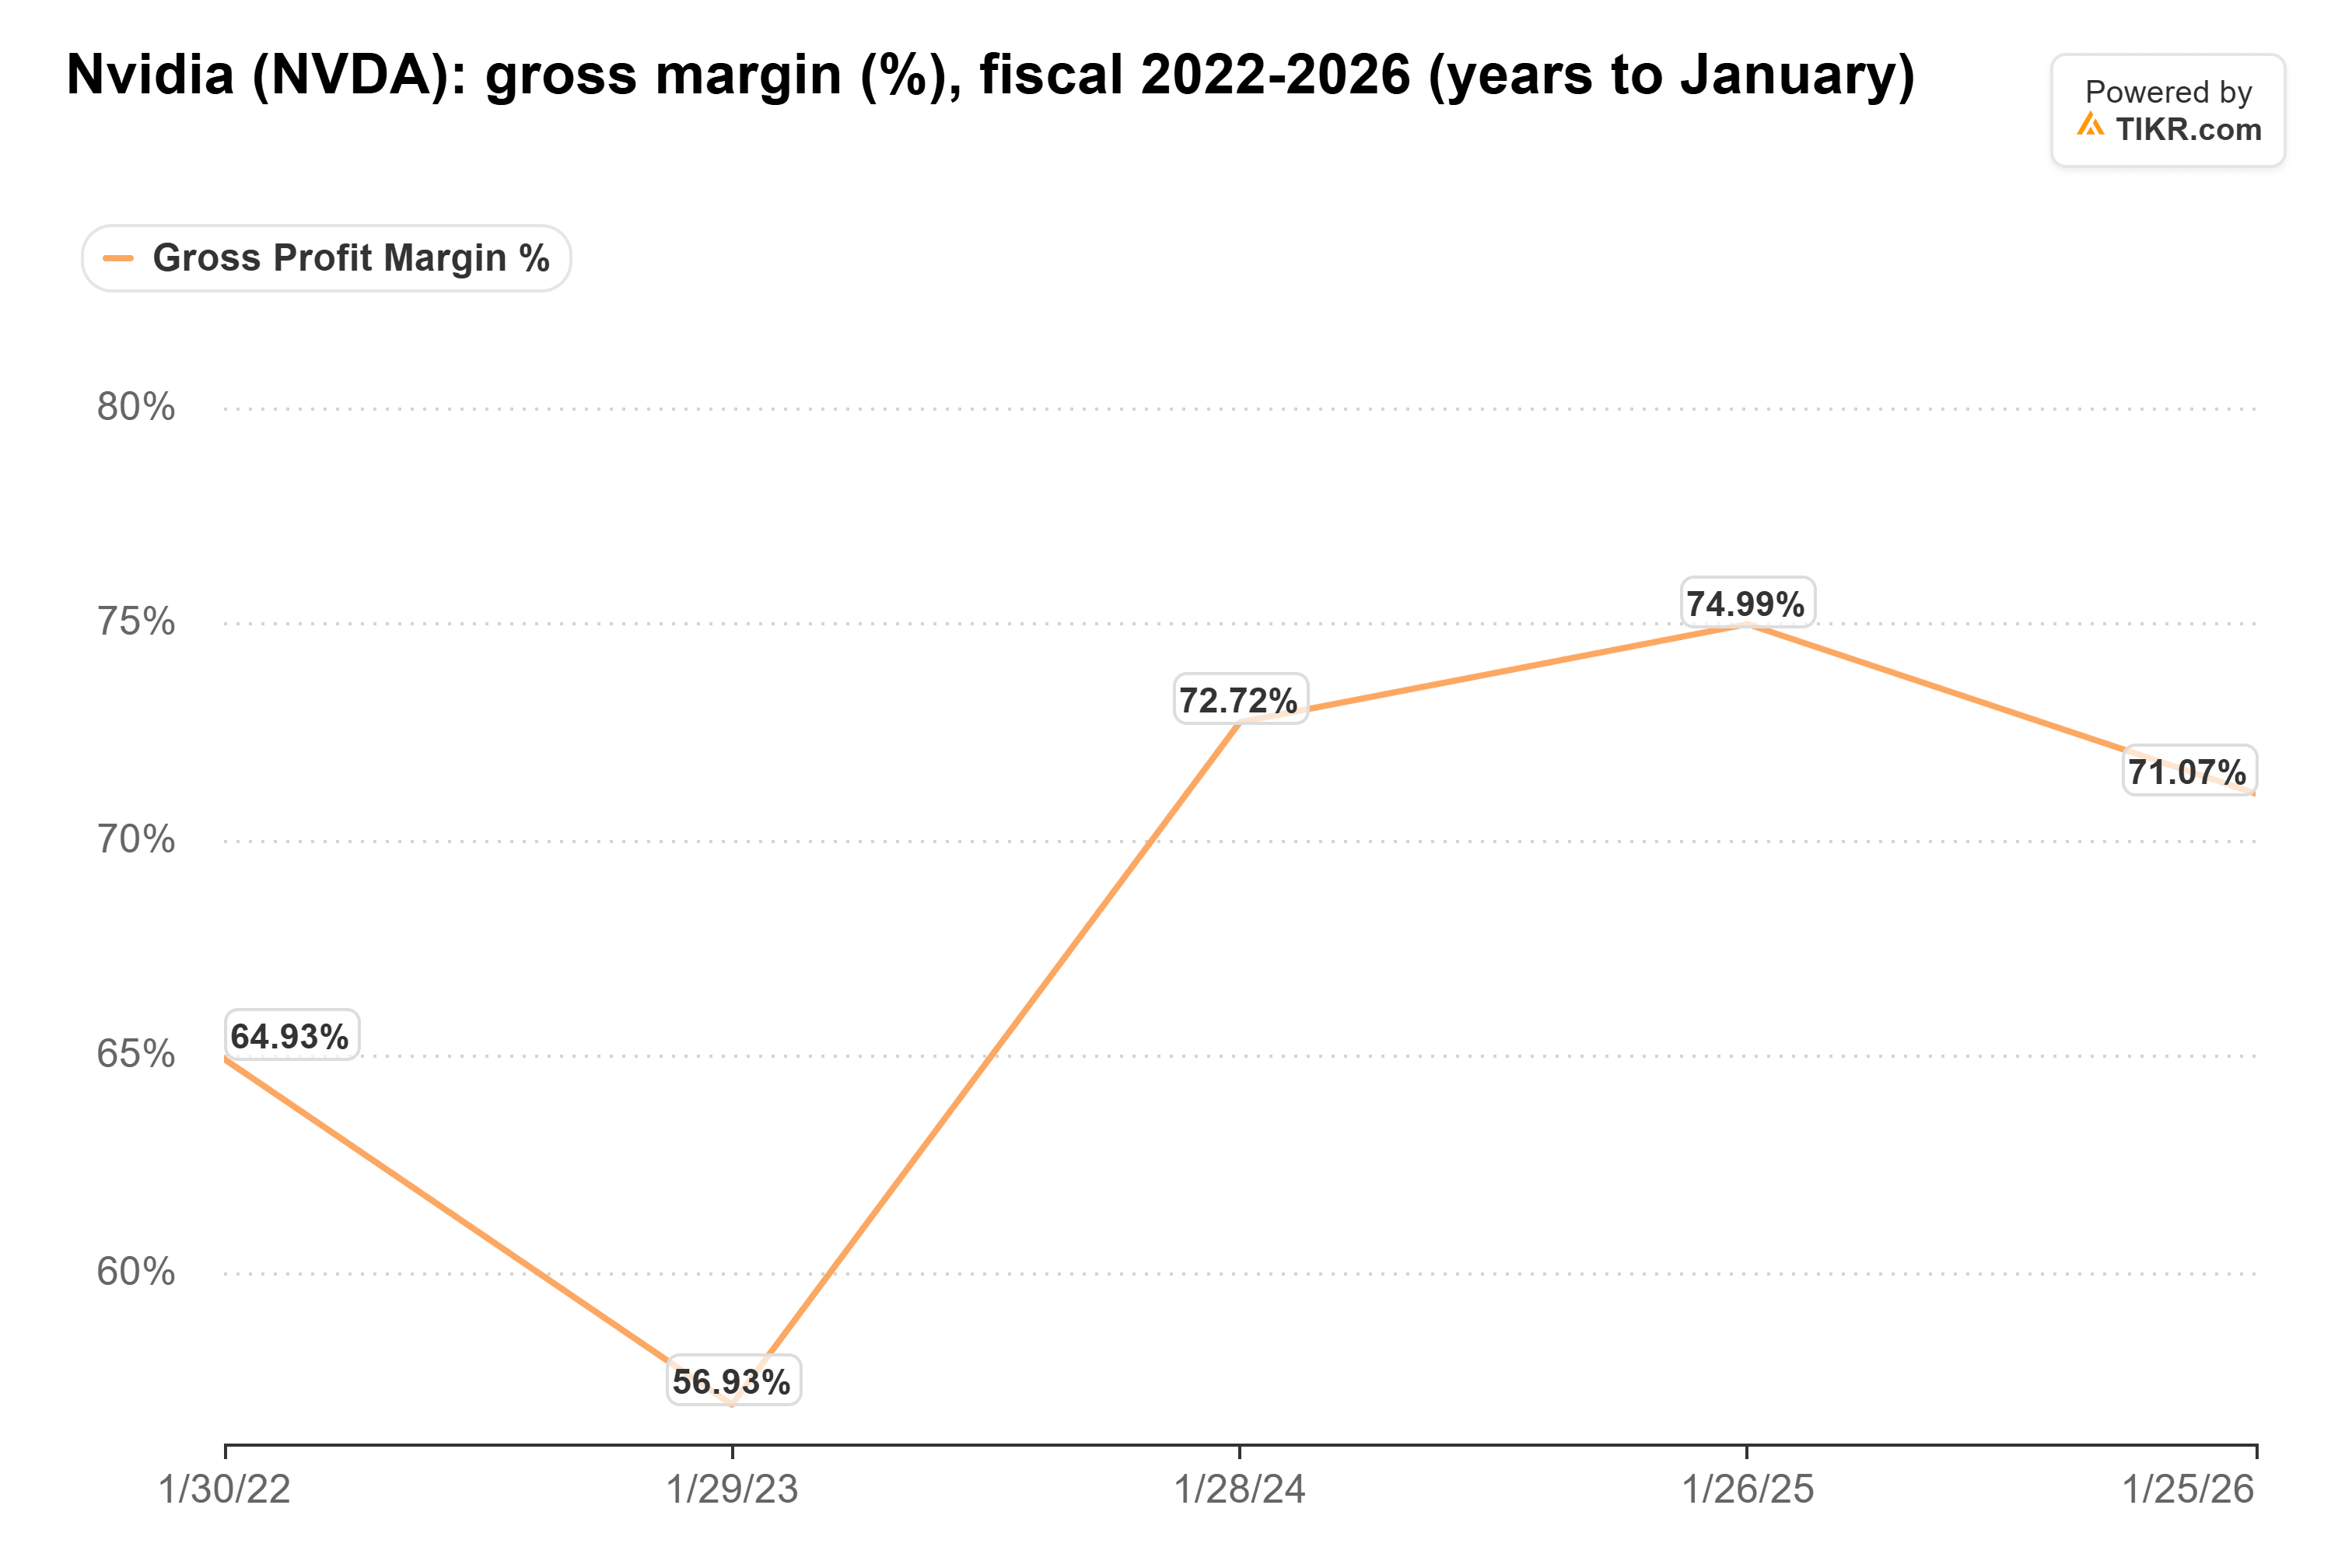
This year it’s even higher: 74.9% over the first nine months, up from 69.3% a year earlier. The one catch is the fourth-quarter guide of 71%-72%, down from the third quarter’s 74.8%.
Room for both, for now
I think Jassy is right. With AWS that short on capacity, Amazon can grow Trainium triple digits and keep buying Nvidia’s chips, and Nvidia is still earning near-record margins on what it sells.
The real test comes when the build slows. Analysts expect Amazon’s capex to reach $278.2 billion in 2027, and Amazon gives its 2027 outlook with fourth-quarter results in early February. If it guides near that, there’s room for both. If spending flattens out, more of Trainium’s growth would come straight out of Nvidia’s share at AWS.
So what is Nvidia stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nvidia could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


