Key Takeaways
- AMD stock is up 130% in the past year after record quarters. Third-quarter Data Center revenue rose 97% to $8.5 billion, and AMD guided fourth-quarter revenue to about $17 billion.
- Analysts have more than doubled their 2027 earnings estimate, so AMD trades just under its 5-year average forward multiple despite the run.
- The pullback from October’s high came from scares across the chip sector, such as Intel’s PC warning, while customers like Meta keep spending on AMD’s Helios racks.
- AMD looks like a buy for patient investors. Warrants for up to 320 million shares are the cost, and the early-February report is the next test.
Advanced Micro Devices (AMD) stock is up 130% in the past year, and its own record quarters did most of the lifting.
AMD keeps taking server-chip share from Intel (INTC), and Meta Platforms (META) is among the customers already running its Helios racks.
TIKR tracks 54 analysts on AMD. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AMD, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AMD’s Analyst Ratings
Record quarters built the run
The run rests on two reports:
- Second quarter (Aug. 4): revenue rose 50% to $11.5 billion, and Data Center revenue more than doubled to $6.7 billion. AMD also announced a partnership with Anthropic to deploy up to 2 gigawatts of MI450 GPUs.
- Third quarter (Nov. 3): revenue rose 45% to $13.4 billion, Data Center rose 97% to $8.5 billion, and non-GAAP EPS rose 74% to $2.09.
- Fourth-quarter guide: about $17 billion of revenue, up about 66%, at a non-GAAP gross margin of about 55%.
Chair and CEO Lisa Su said in the third-quarter release that “we expect growth to accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production.” (Venice is AMD’s new server CPU.)
Meta is a big part of that ramp. On Oct. 27, AMD said it would put $1 billion into Meta’s stock offering and that Helios is running at Meta. Meta guides 2026 capital spending to $135 billion to $145 billion. But its third-quarter free cash flow was negative $2.1 billion. So part of AMD’s ramp depends on a customer that is selling stock to pay for its build.
TIKR’s consensus has AMD’s normalized EPS more than doubling, from $8.08 in 2026 to $17.64 in 2027:
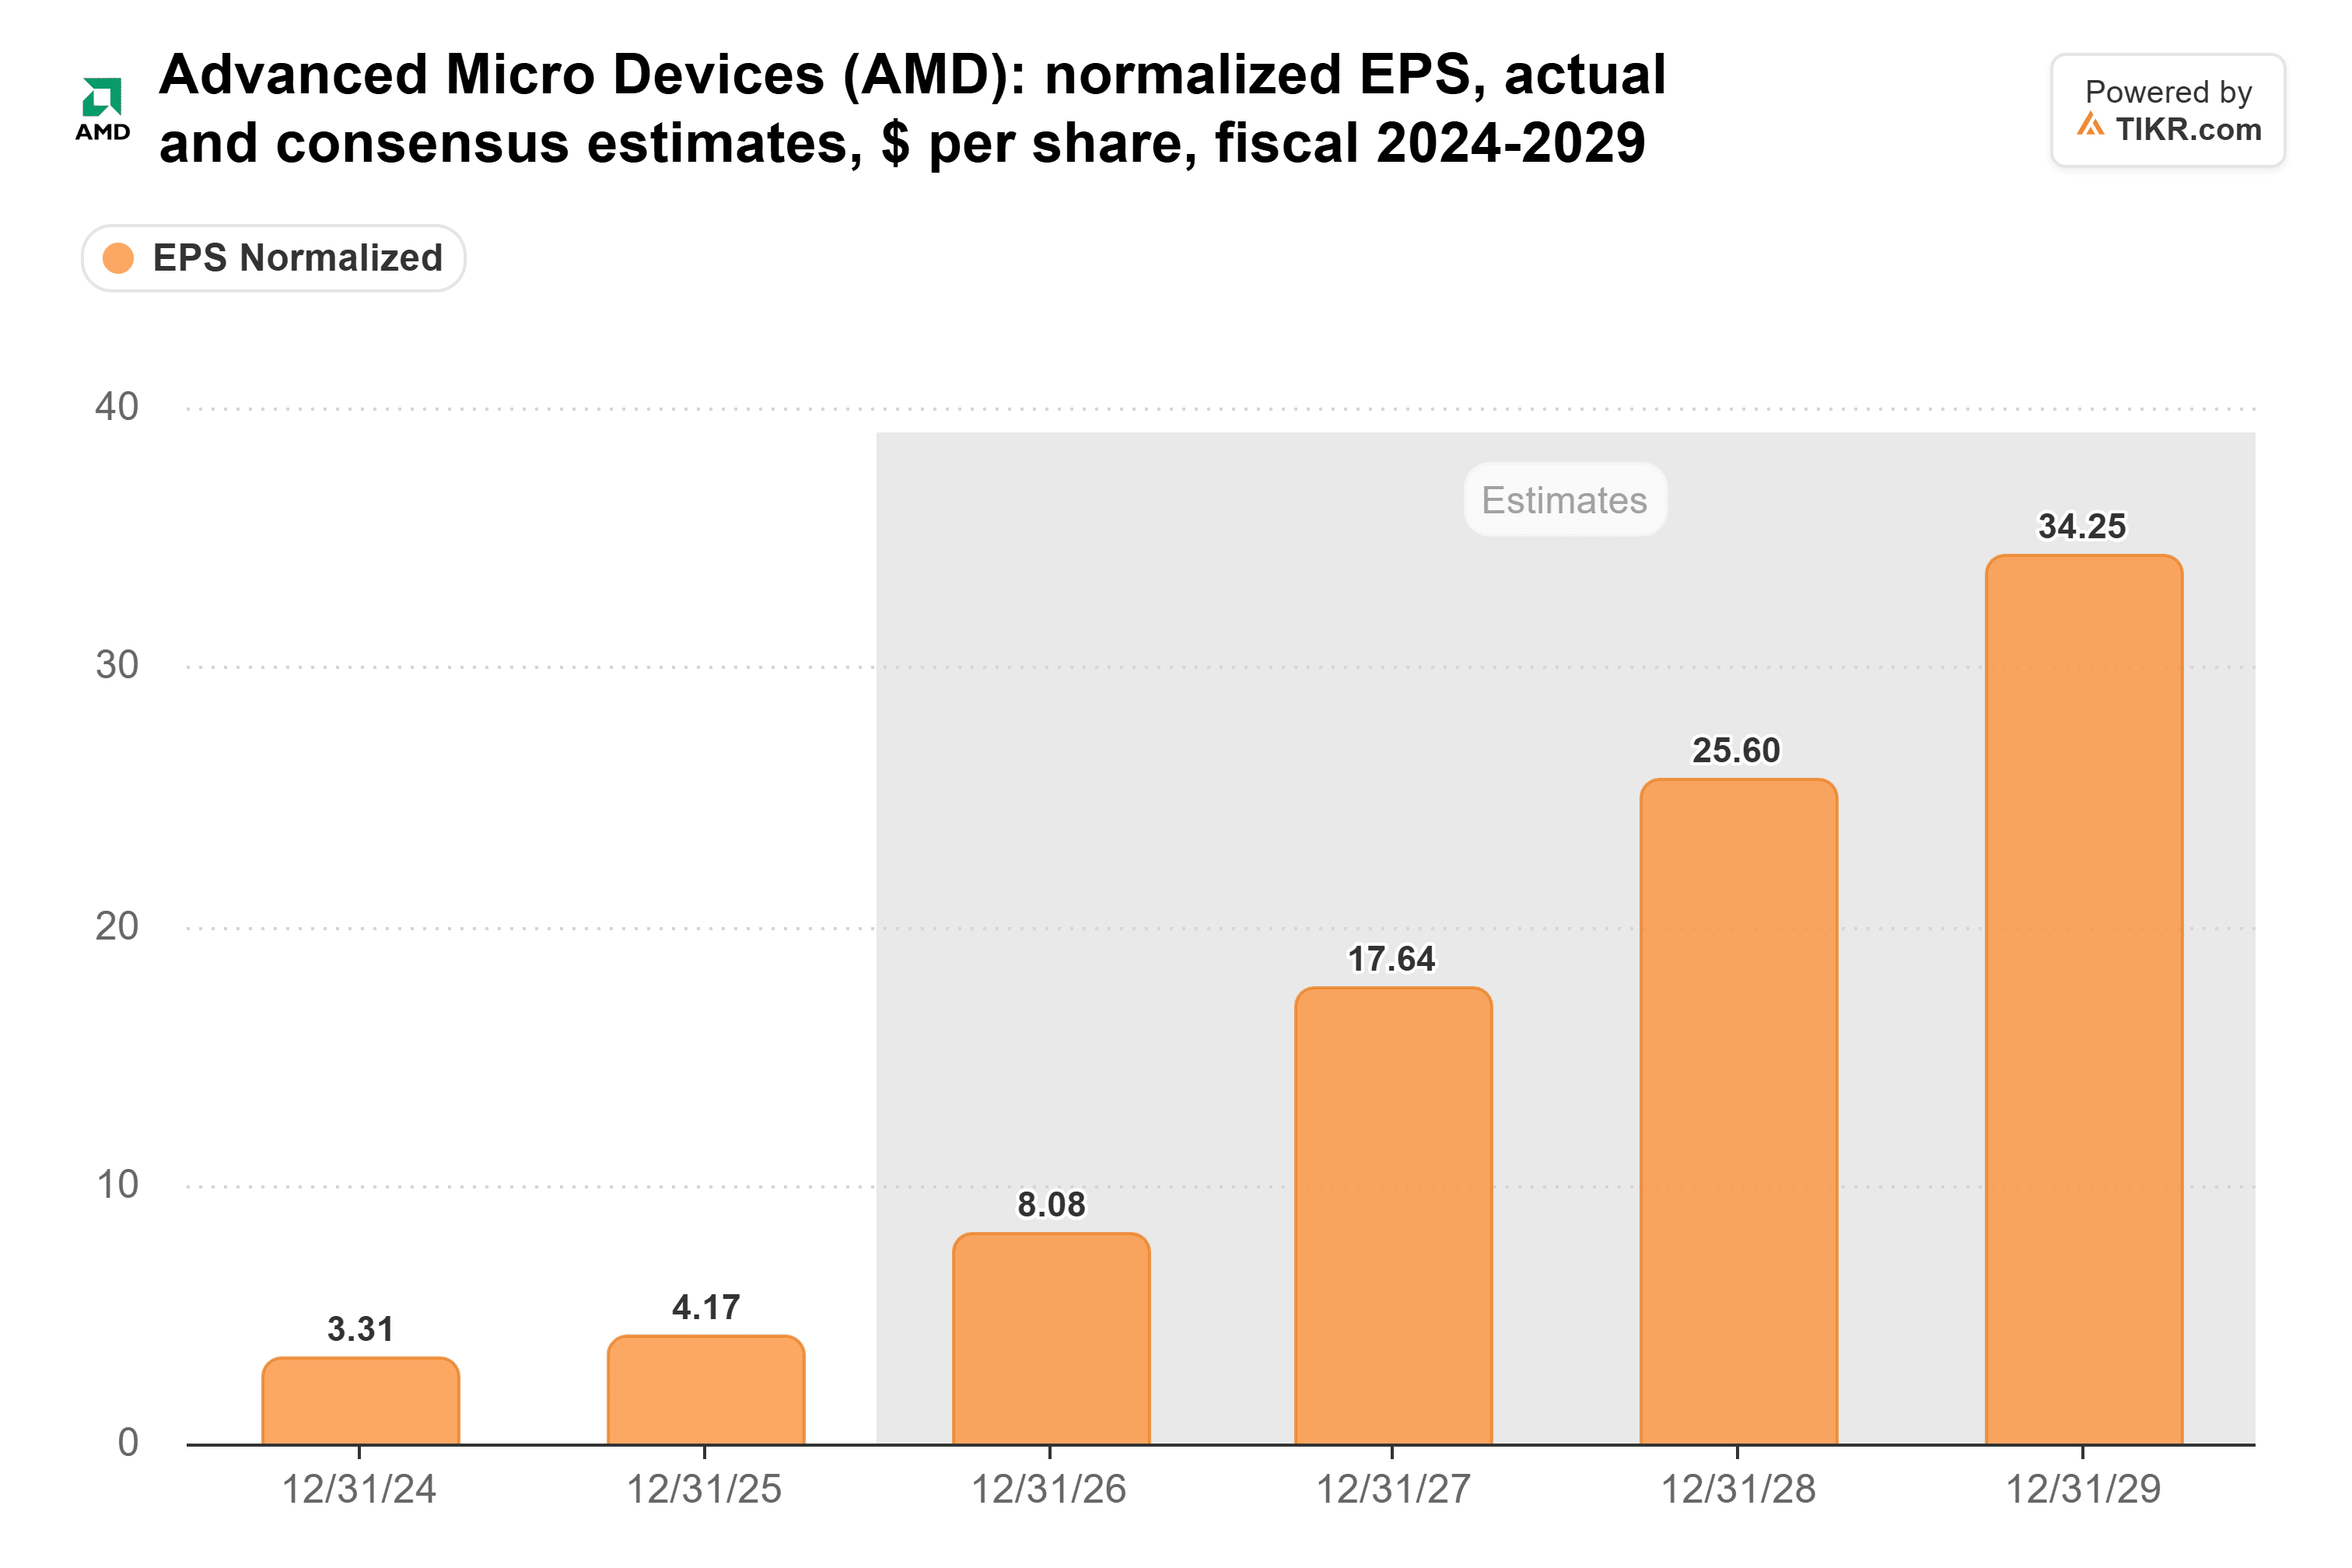
At the end of September 2025, analysts expected just $7.43 for 2027.
The selloffs started elsewhere
AMD is now 20% below its October high, and its own business had little to do with it. Intel warned of a PC slowdown on Oct. 29. On Nov. 5, two days after AMD’s record quarter, chip stocks sold off on fears that the midterm results would slow the AI data-center build-out. Then Nvidia’s CEO quit. On Nov. 16, a new Commerce Department rule began requiring licenses for advanced chips shipped to five countries.
AMD does share one of Intel’s problems. Its PC chip sales grew just 7% to $2.9 billion in the third quarter. Meanwhile, Intel expects industry PC shipments to fall about 12% this year and roughly 10% more in 2027. In servers, though, Intel can’t make enough chips. JPMorgan estimates that Intel’s share of server x86 CPU revenue has fallen from 77% to 53% since November 2022. Intel’s stock is up 58% over the past year anyway.
Not too late, if the estimates hold
AMD isn’t priced like a stock that has run too far. It trades at 33x forward earnings, just under its 5-year average of 35x and about half its June peak of 67x:
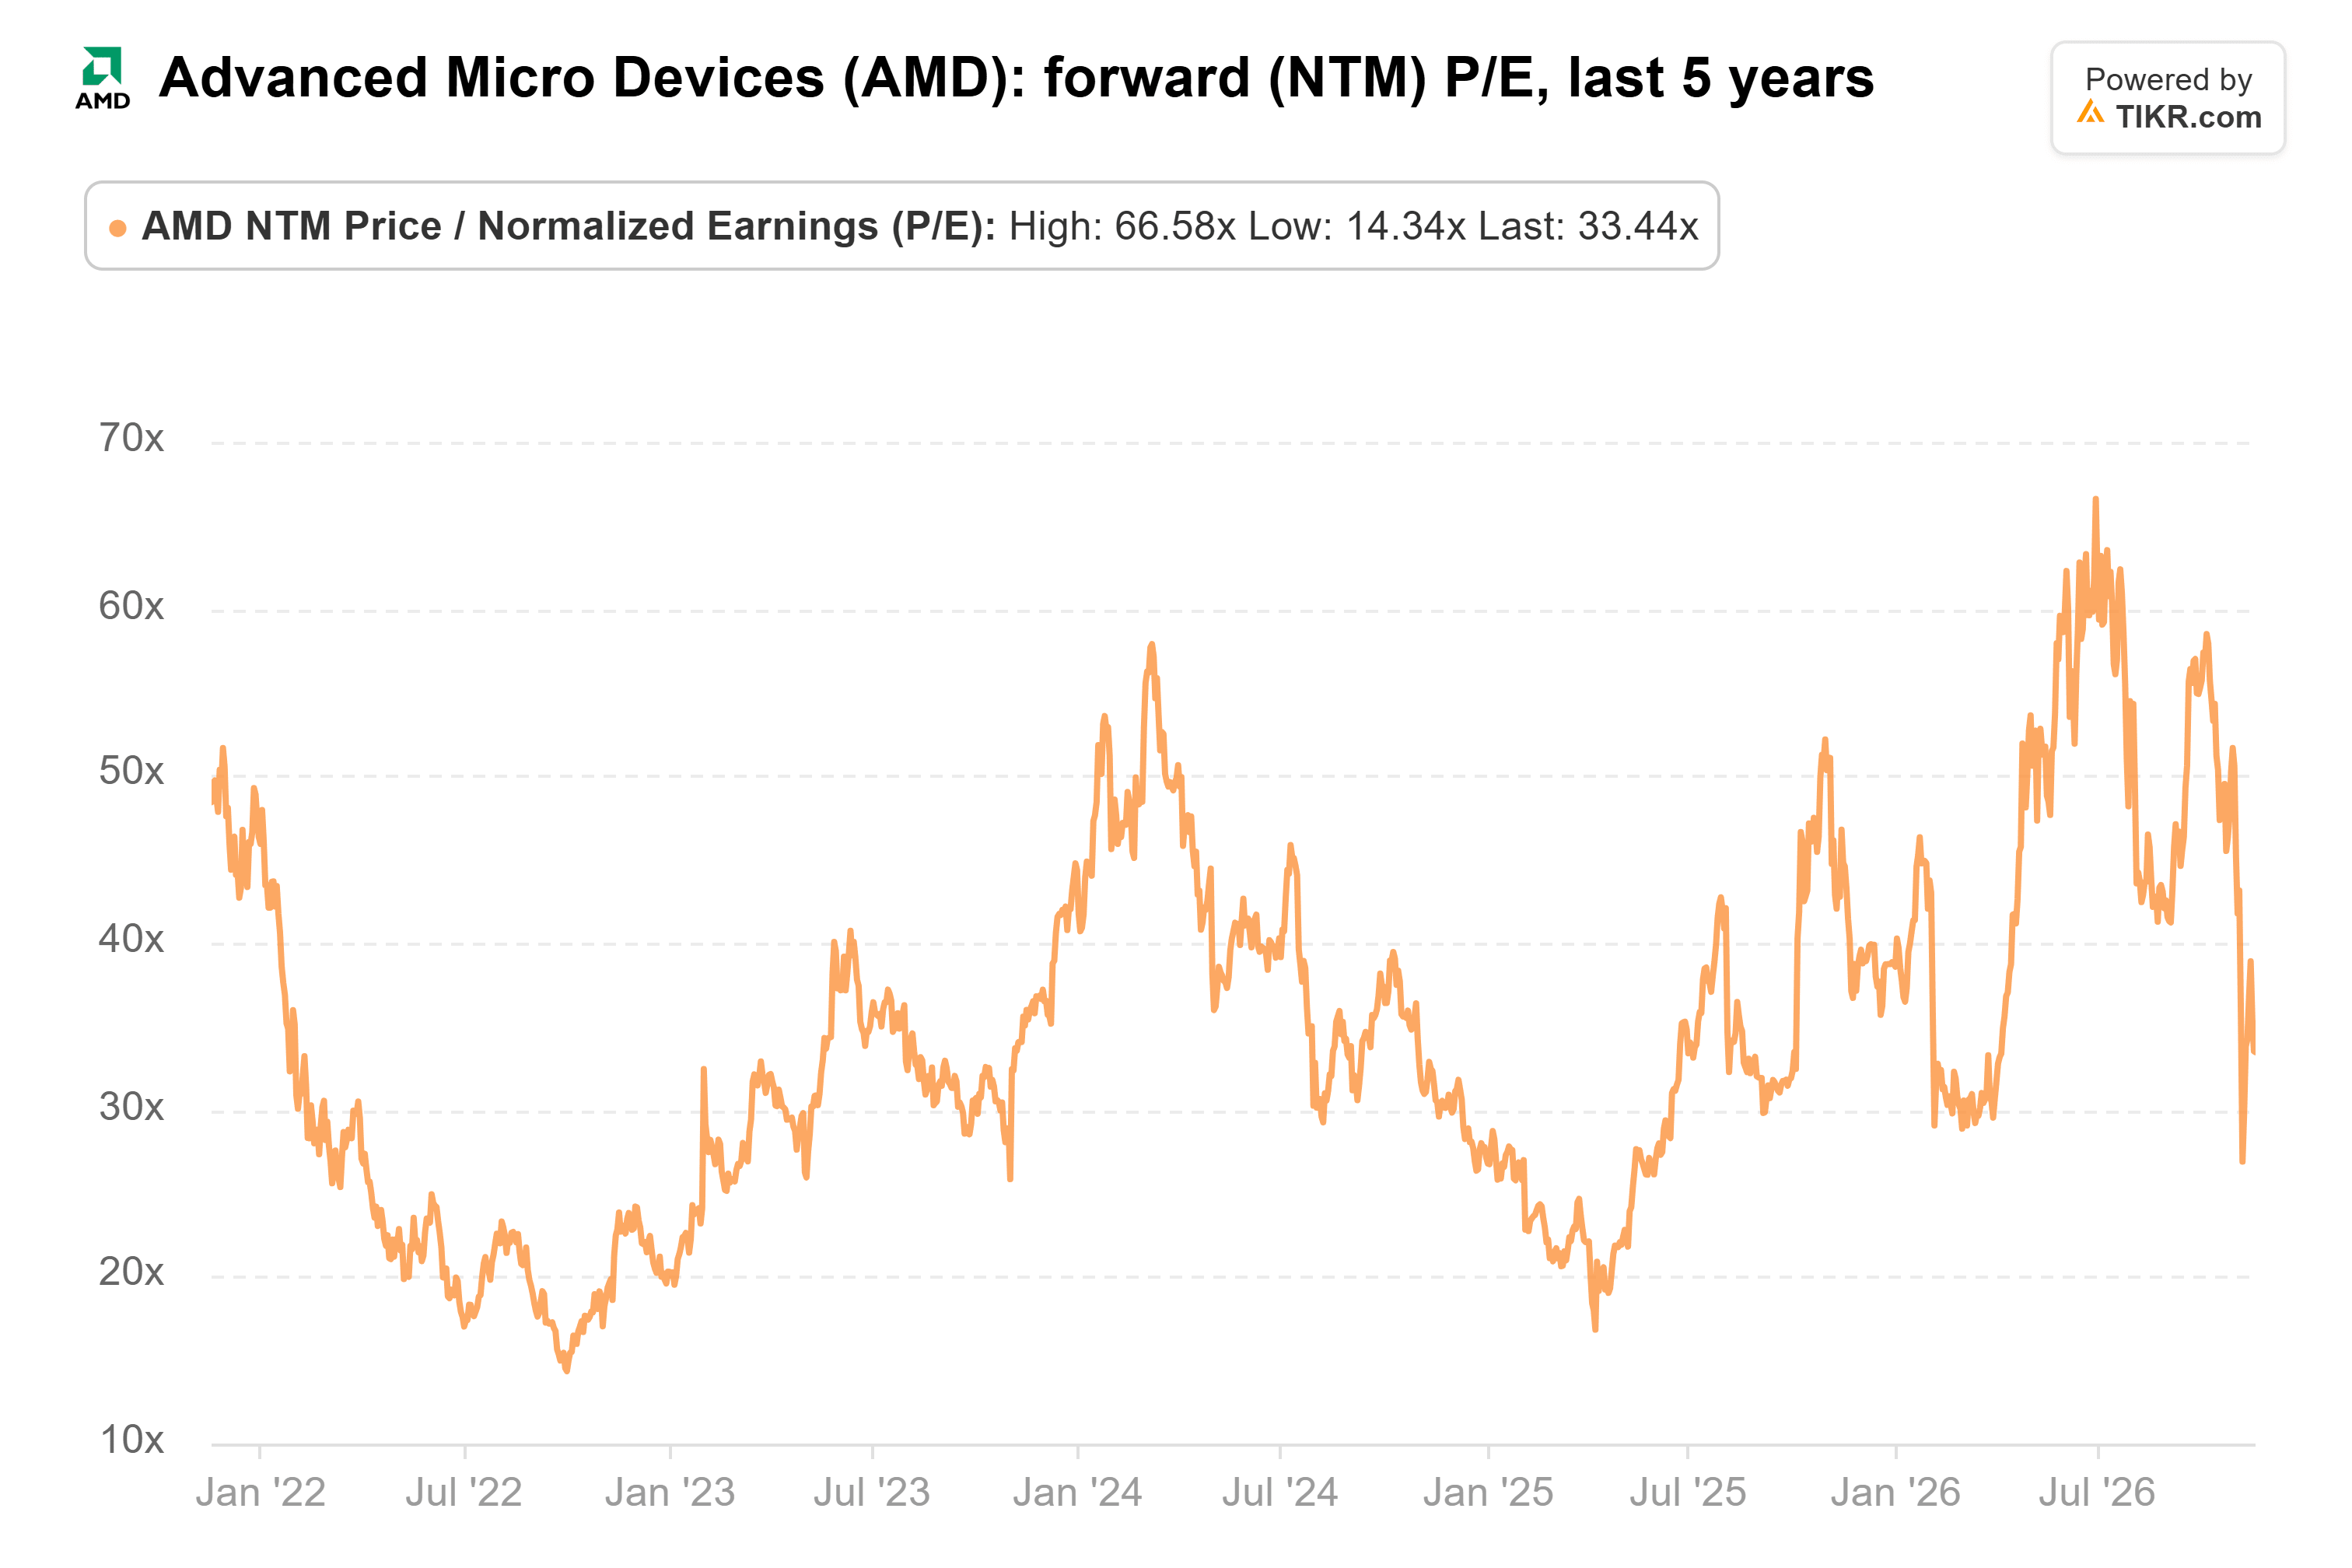
At the latest close, AMD trades at about 30x its 2027 consensus earnings.
The cost is dilution. OpenAI and Meta hold warrants for up to 320 million AMD shares at a penny apiece, about a fifth of its share count. Free cash flow also fell to $554 million in the third quarter from $1.56 billion in the second. Inventory rose about $3 billion ahead of the Helios and Venice ramp.
Even so, I think AMD is a buy for patient investors. Analysts’ 2027 estimate has more than doubled in about a year. At its usual multiple, AMD only needs those numbers to show up.
The next test is the fourth-quarter report, expected in early February. Revenue near the $17 billion guide with a non-GAAP gross margin of 55% or better would confirm Helios is ramping on plan. A miss on either would put 2027’s estimates in doubt.
So what is AMD stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AMD could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!