Key Takeaways
- Altria yields 5.9% and Hormel yields 5.4%, and over each company’s latest twelve months they paid out 78% and 82% of their free cash flow in dividends.
- Altria’s cash dividend payout ratio stayed between 75% and 82% in each of fiscal 2021 to 2025, while Hormel’s dividends topped its free cash flow in fiscal 2025.
- Hormel carries less debt today, but it’s paying for a deal for Brakebush worth about $1.06 billion partly with new borrowing.
- Altria raised its 2026 earnings guidance on Oct. 29, and Hormel’s new CEO, John Ghingo, took over on Oct. 26.
Hormel Foods (HRL) agreed on Sept. 30 to buy Brakebush Brothers, a chicken company, for about $1.06 billion. It’s paying with cash on hand and new debt, which is a big check for a company whose dividends ran past its free cash flow in fiscal 2025.
Altria Group (MO) has had the opposite kind of fall. It raised its 2026 earnings guidance on Oct. 29, and its board added $1 billion to its buyback in October.
Both yield over 5%, and income investors lean on both for a check they can count on. So which dividend is safer now?
| Metric | Altria Group | Hormel Foods |
|---|---|---|
| Dividend yield | 5.9% | 5.4% |
| Annual dividend | $4.44 | $1.17 |
| Dividend growth, fiscal 2020-2025 | 4.1% a year | 4.5% a year |
| Cash dividend payout ratio (TTM) | 78% (to Sept. 30, 2026) | 82% (to July 26, 2026) |
| Net debt/EBITDA (LTM) | 1.7x | 1.2x |
| Interest coverage (LTM) | 10.9x | 12.6x |
Source: TIKR and StockAnalysis, Nov. 9, 2026.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Altria’s payout barely budges
In August, Altria raised its quarterly dividend 4.7% to $1.11 a share, “our 61st increase in 57 years,” as the company put it. Altria plans more raises: “We maintain our progressive dividend goal that targets mid-single digits dividend per share growth annually through 2028.”
Its cash flow can pay for that goal. Altria’s free cash flow ran between $8.05 billion and $9.09 billion in each fiscal year from 2021 to 2025. Its cash dividend payout ratio stayed between 75% and 82% over the same stretch:
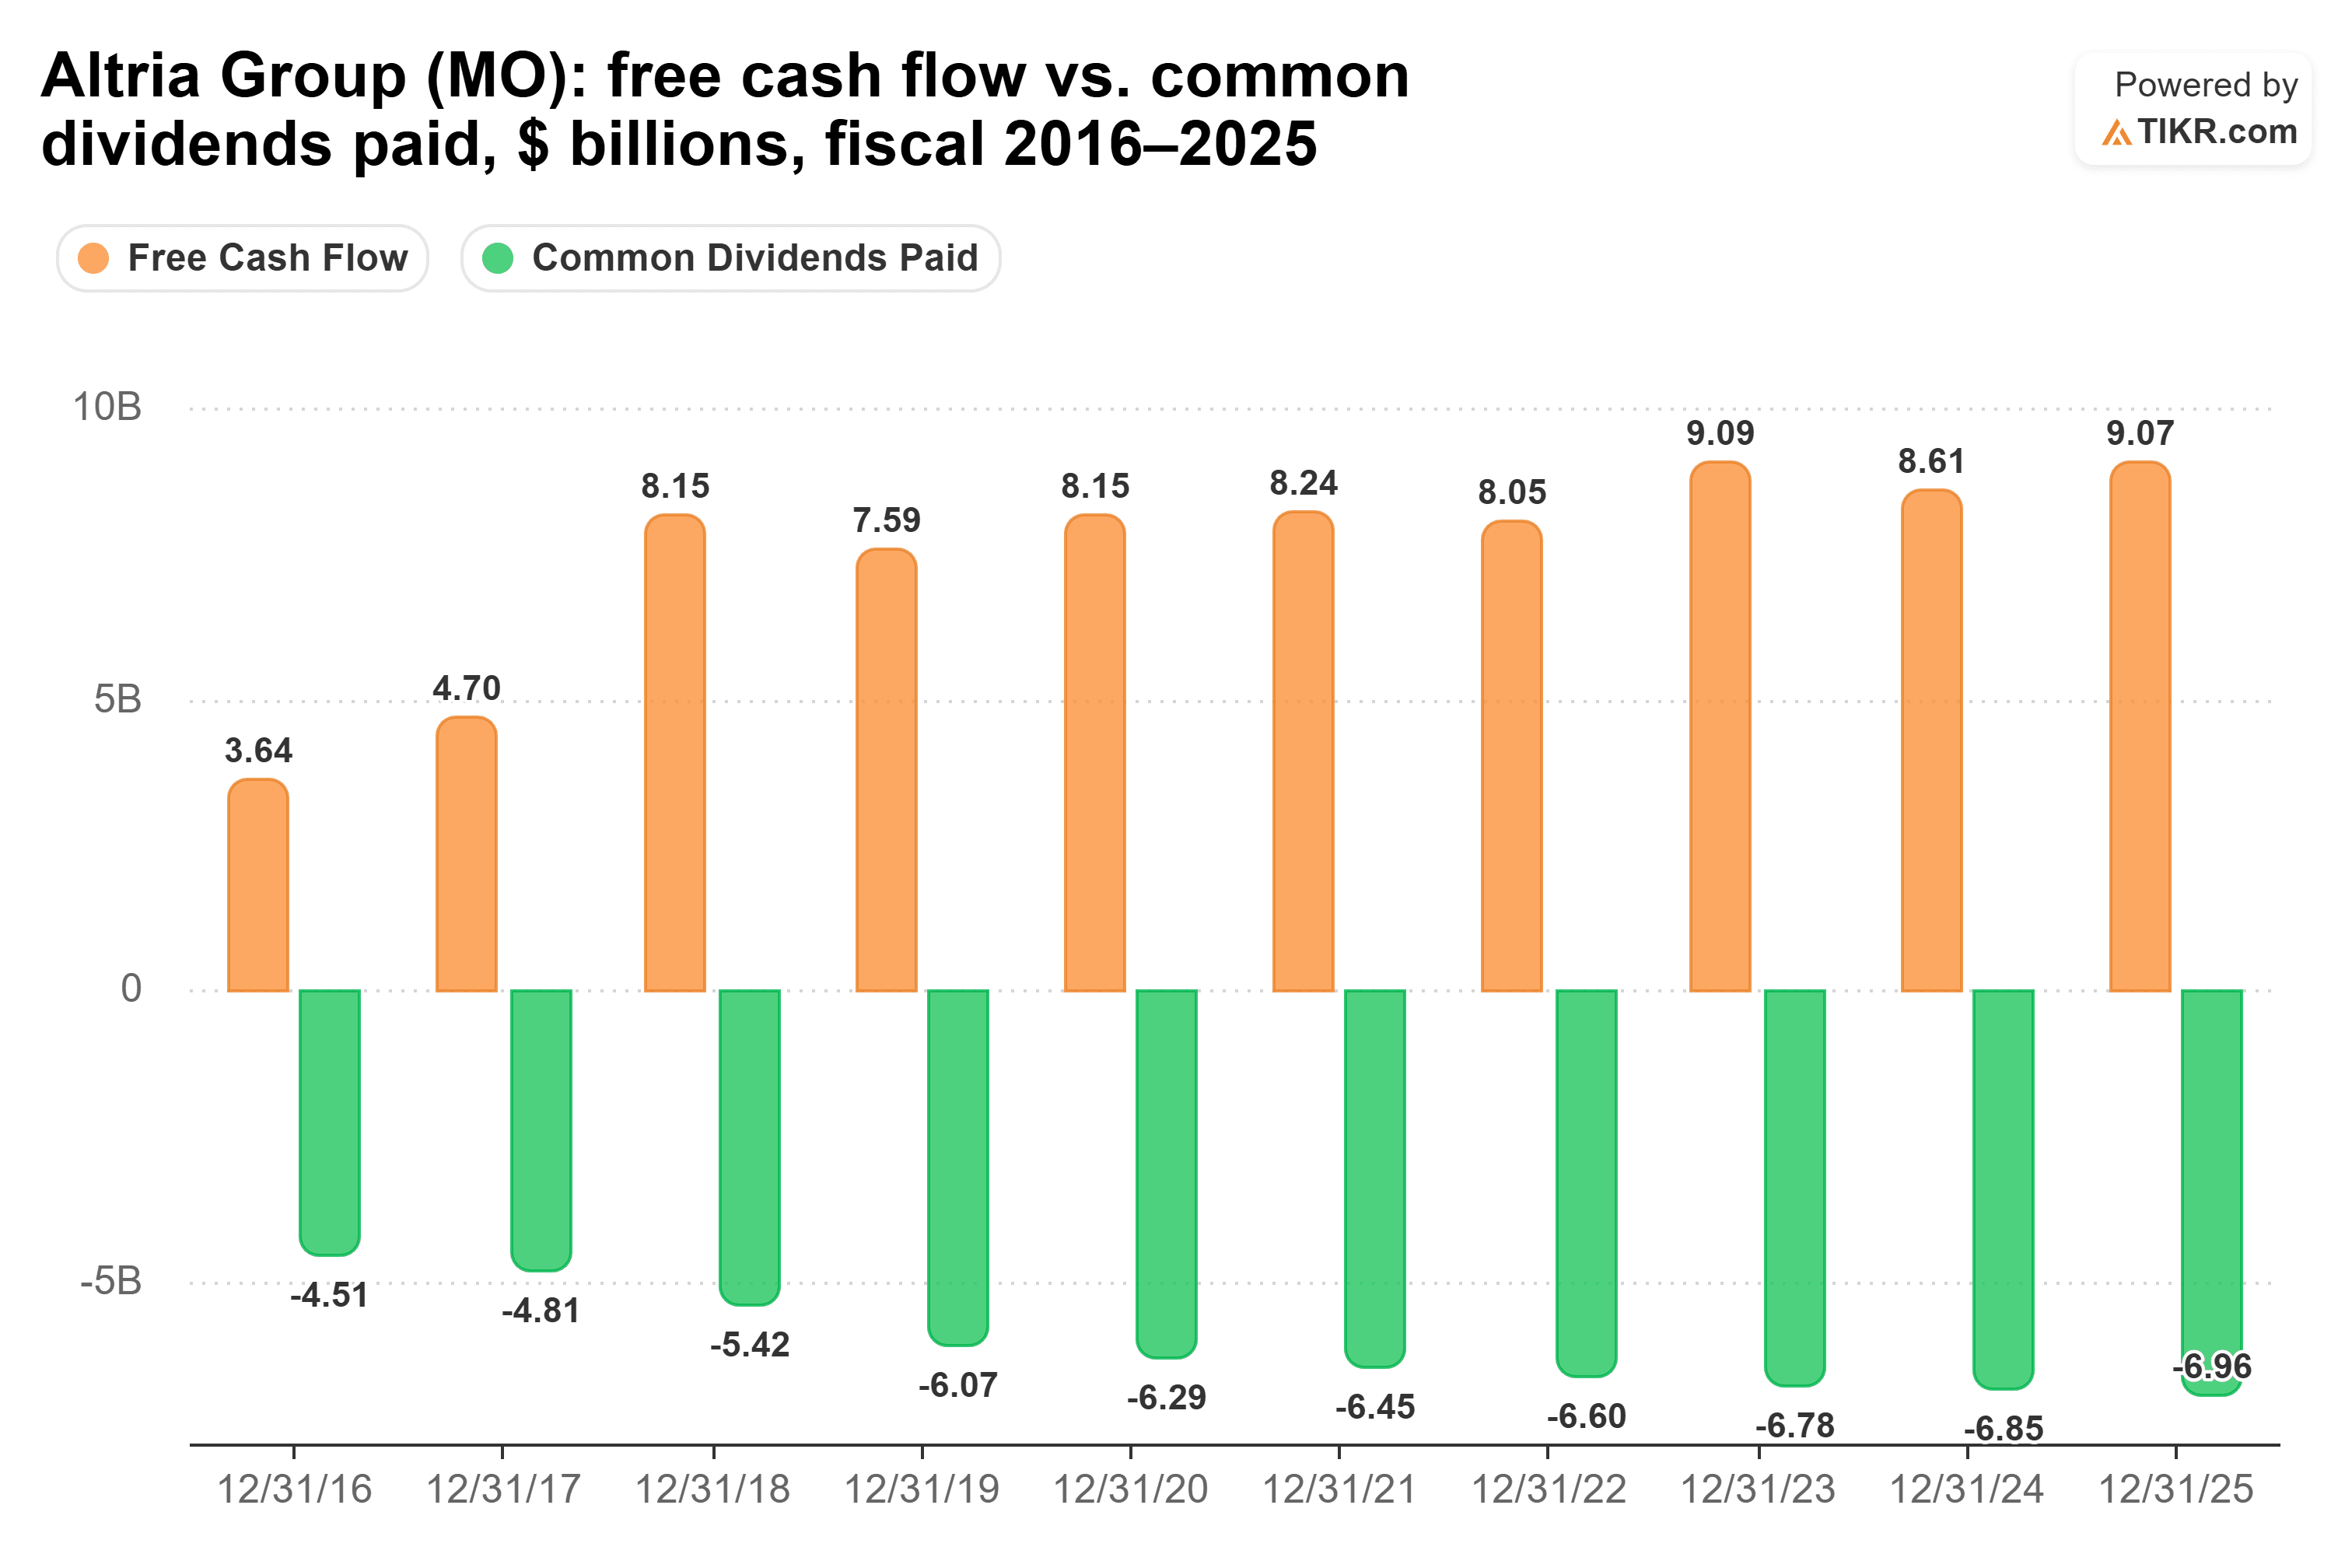
Over the twelve months to Sept. 30, 2026, Altria paid $7.12 billion of dividends from $9.07 billion of free cash flow. That’s a solid 78%, and it left $1.95 billion for buybacks and debt.
Third-quarter adjusted EPS rose 4.8% from a year earlier to $1.52. Altria now expects 2026 adjusted EPS of $5.66-$5.74, which is 4.5% to 6.0% growth and in line with its dividend goal. The shares jumped 7% in premarket trading on the report. Shipments of on! nicotine pouches rose 13.3% in the quarter. The main risk is the core business: domestic cigarette shipments keep falling, and Copenhagen and Skoal are losing users to pouches.
Hormel’s cushion came back, but it’s about to borrow
Hormel’s coverage over its latest twelve months looks close to Altria’s, but the record behind it is bumpier. On Sept. 28, Hormel declared a quarterly dividend of $0.2925 a share, payable Nov. 16. That was its 393rd consecutive quarterly dividend, at the same rate as the quarter before.
Hormel’s dividends paid more than doubled, from $296 million in fiscal 2016 to $633 million in fiscal 2025. Its free cash flow ranged from $629 million to $1.01 billion from fiscal 2016 to fiscal 2024, then fell to $534 million in fiscal 2025:
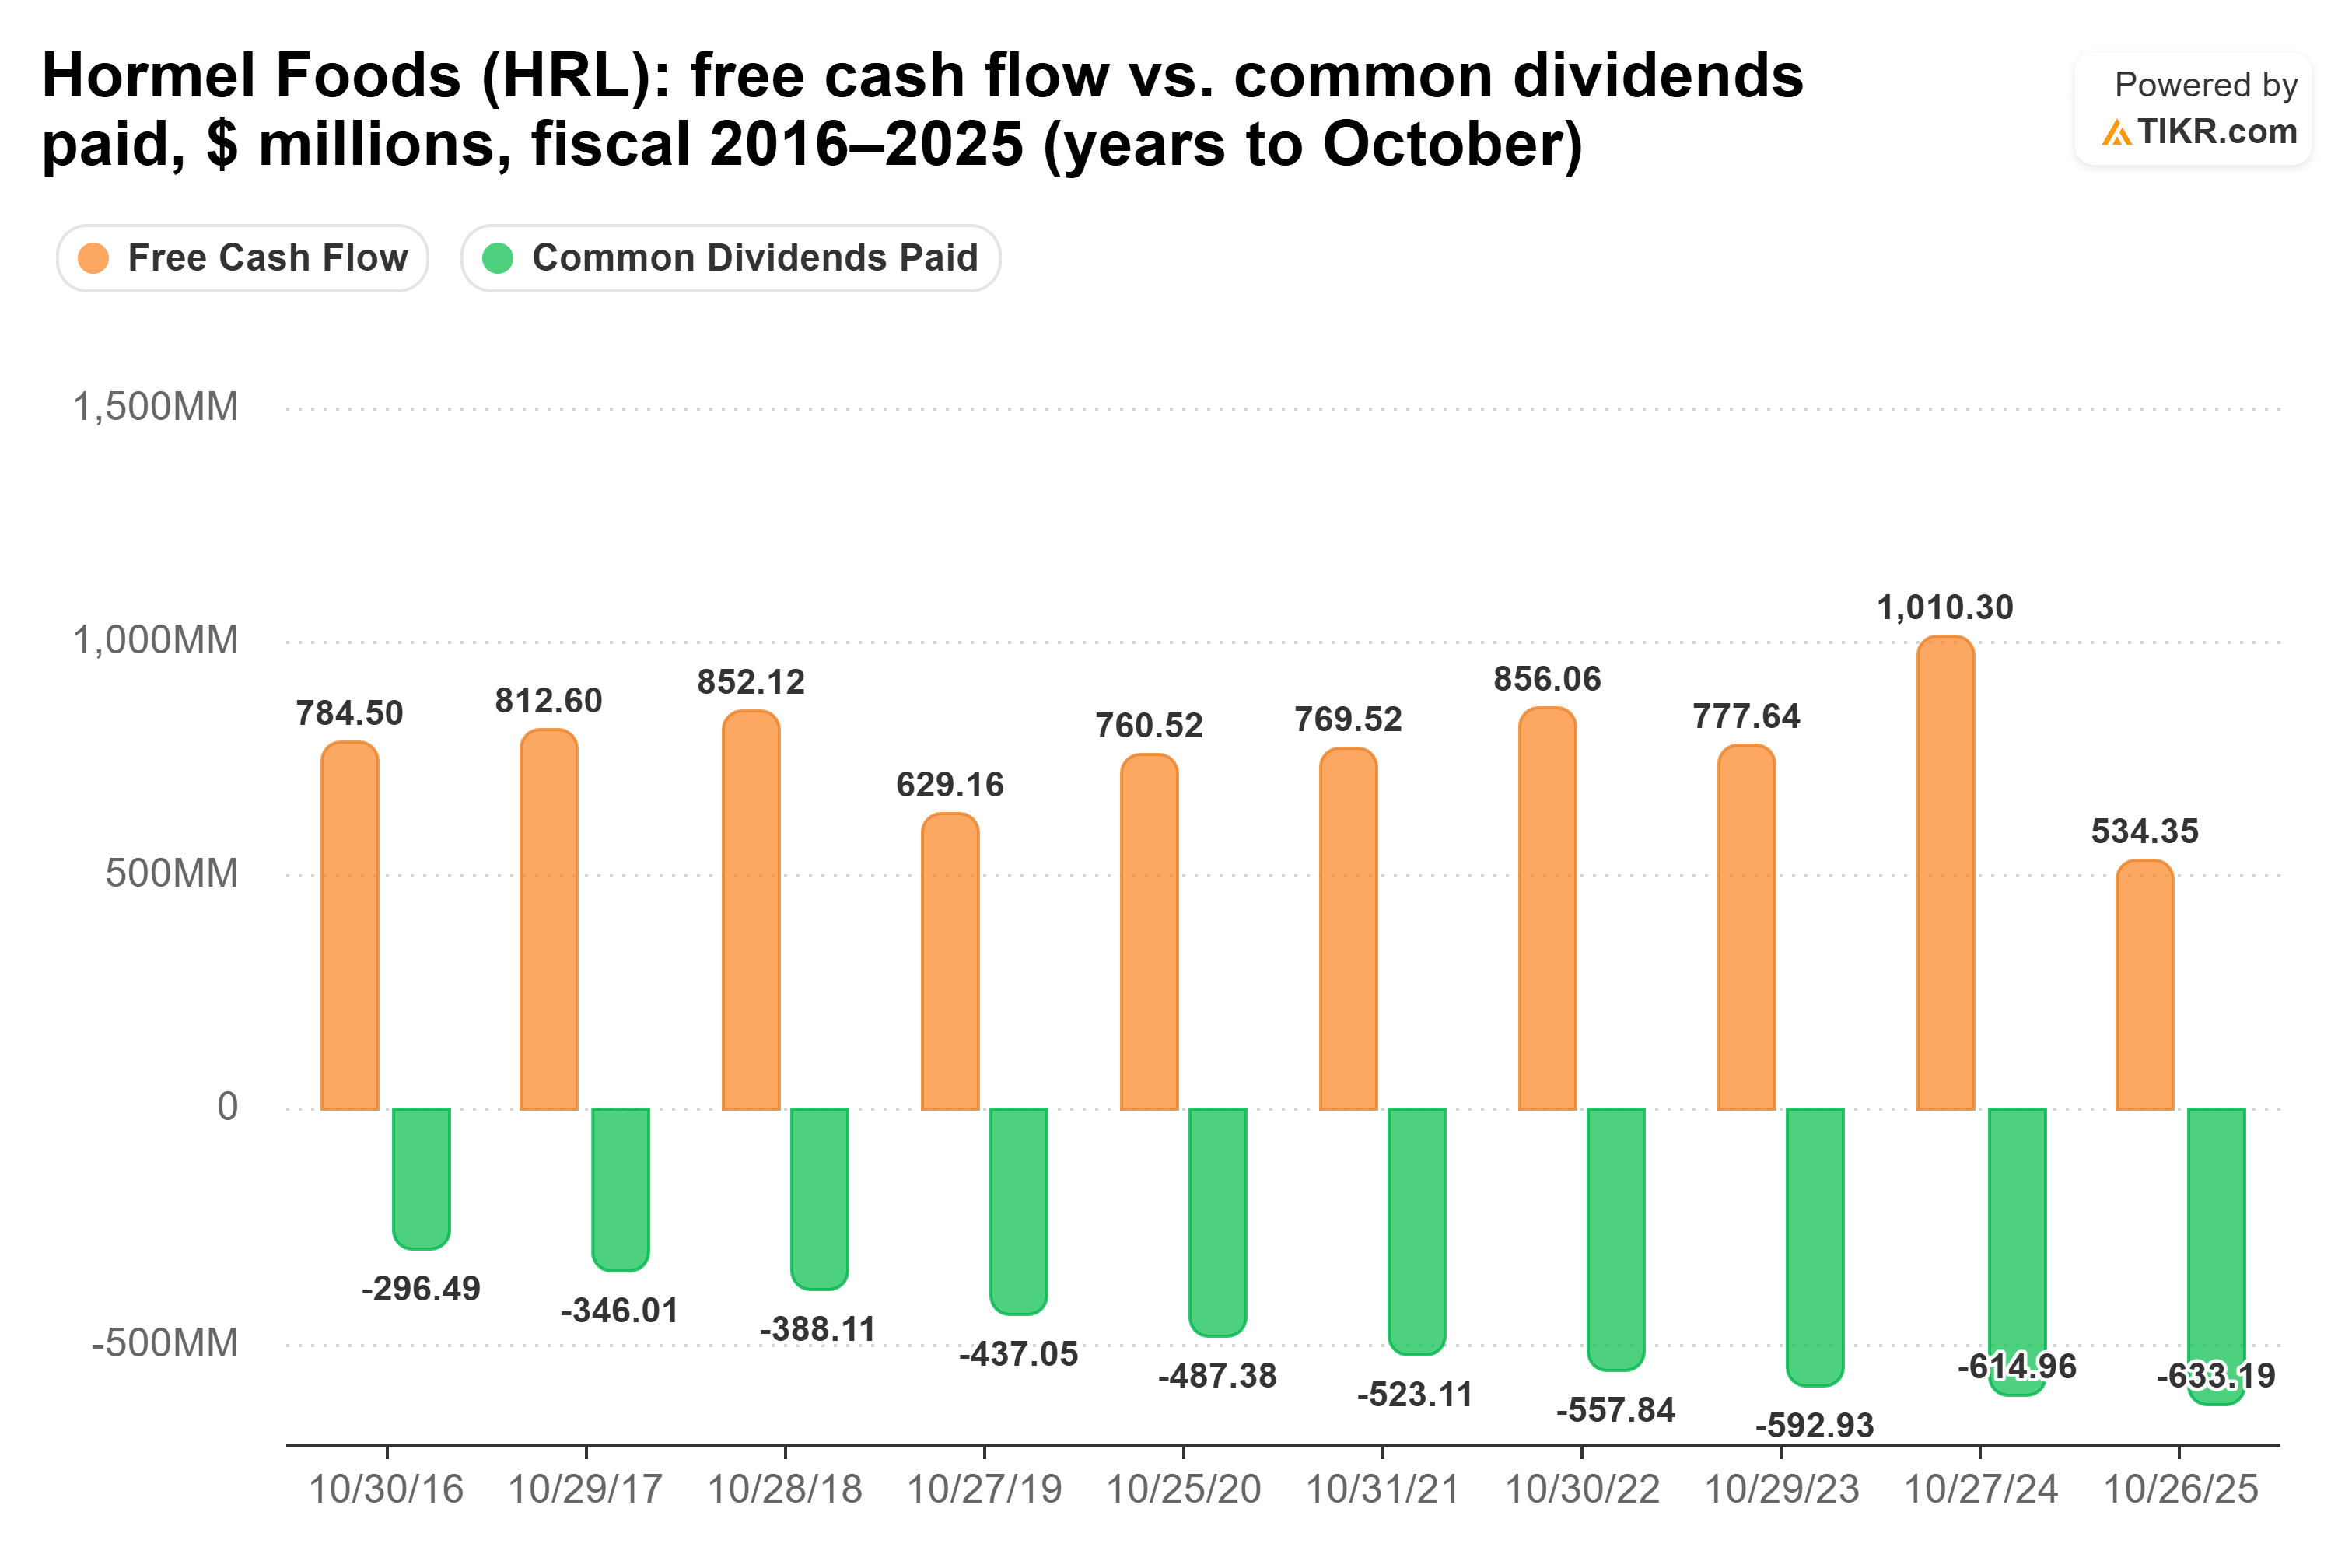
That made fiscal 2025’s payout ratio a risky 118.5%, up from 60.9% in fiscal 2024. Coverage recovered to 82% over the twelve months to July 26, 2026, with $641 million of dividends paid from $781 million of free cash flow. Third-quarter cash from operations rose 54% to $241 million.
Organic sales fell 2% in the third quarter, as Hormel exited whole-bird turkey and private-label snack nuts and consumer spending stayed strained. But foodservice posted its 12th straight quarter of organic growth, and Hormel raised its fiscal 2026 adjusted EPS guidance to $1.45-$1.51. Brakebush should close in Hormel’s fiscal first quarter of 2027, and Hormel expects it to add to adjusted EPS starting in fiscal 2028. Ghingo said on the August call that “the dividend continues to be very important to us,” though fiscal 2025’s cash didn’t cover it.
So which dividend wins?
Altria’s dividend is the safer one now. Its payout ratio held between 75% and 82% for five straight fiscal years, it covers the dividend with $1.95 billion to spare, and it just raised its earnings guidance.
Hormel has real strengths. It carries less debt, at 1.2x EBITDA against Altria’s 1.7x, and covers its interest 12.6x against 10.9x. Foodservice keeps growing, and free cash flow is back above the dividend. But Hormel’s dividends outran its cash only a year ago, its organic sales are shrinking, and it’s borrowing for a deal that won’t add to earnings until fiscal 2028. I’d rather count on Altria’s steadier cash.
Altria pays more today, too: $10,000 at its 5.9% yield pays $590 a year, against $540 for Hormel at 5.4%. Hormel’s dividend has grown faster, at 4.5% a year from fiscal 2020 to fiscal 2025 against Altria’s 4.1%. Even at those rates, Hormel’s income wouldn’t pass Altria’s until around 2049.
Of course, Hormel’s full fiscal 2026 results, for the year that ended in October, will show whether its free cash flow covered the dividend for the whole year before the Brakebush debt arrives.
Forget Altria Group: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Altria Group isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!