Key Takeaways
- Apollo Management Holdings, whose 13F holds $6.43 billion of US stocks, raised its Churchill Downs stake 512% and its Primo Brands stake 121% in the third quarter, and added put options on Apple.
- Churchill Downs trades at about 13x forward earnings, and even its lowest analyst target sits above the latest close.
- Primo Brands’ sales are growing again, but management now expects 2026 adjusted EBITDA at the low end of its range.
- On the numbers, Churchill Downs looks like the best buy of the three.
Apollo Management Holdings made three big moves in the third quarter, according to its 13F for the quarter ended Sept. 30, filed Nov. 16. It raised its stake in Churchill Downs (CHDN) by 512%, more than doubled its Primo Brands (PRMB) position, and picked up put options on Apple (AAPL).
Apollo’s 13F holds $6.43 billion of US stocks, spread across 72 positions.
Churchill Downs got the biggest boost
Apollo held 3.06 million Churchill Downs shares at Sept. 30, worth $232 million and 3.6% of its 13F. The stock is up 22% since the quarter ended.
Growth is slow, but it’s there. Churchill Downs’ Oct. 28 release showed record third-quarter net revenue of $696 million, up 2%, and adjusted EBITDA of $264 million, up 1%. Its Kentucky historical racing machine venues added $11 million of revenue, while its Virginia venues’ adjusted EBITDA fell $6 million.
At about 13x forward earnings, the stock is cheap enough that even the lowest analyst target, $105, sits above the latest close of $92.27. The average target has slipped over the past year, though, from $137 to $126.83:

Even after that slide, the average target is 37% above the latest close.
TIKR tracks 12 analysts on Churchill Downs. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Churchill Downs, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Churchill Downs’ Analyst Ratings
Primo Brands is growing, with a cost problem
Primo Brands is the larger position of the two. Apollo held 15.23 million shares at Sept. 30, worth $290 million and 4.5% of its 13F, after adding 121% to its share count in the quarter. That stake is up 22% since Sept. 30 too.
The bottled-water company’s Nov. 5 release showed third-quarter net sales up 3.1% to $1.82 billion, and gross margin up to 30.4% from 29.9%. Costs are the catch. Chairman and CEO Eric Foss said Primo now expects to deliver “Adjusted EBITDA at the lower end of our previous guidance range for 2026,” citing “macro-cost pressures.”
Wall Street’s average target for the stock hasn’t moved much over the year. It went from $27.77 to $28.36, after peaking at $30.36 in August:
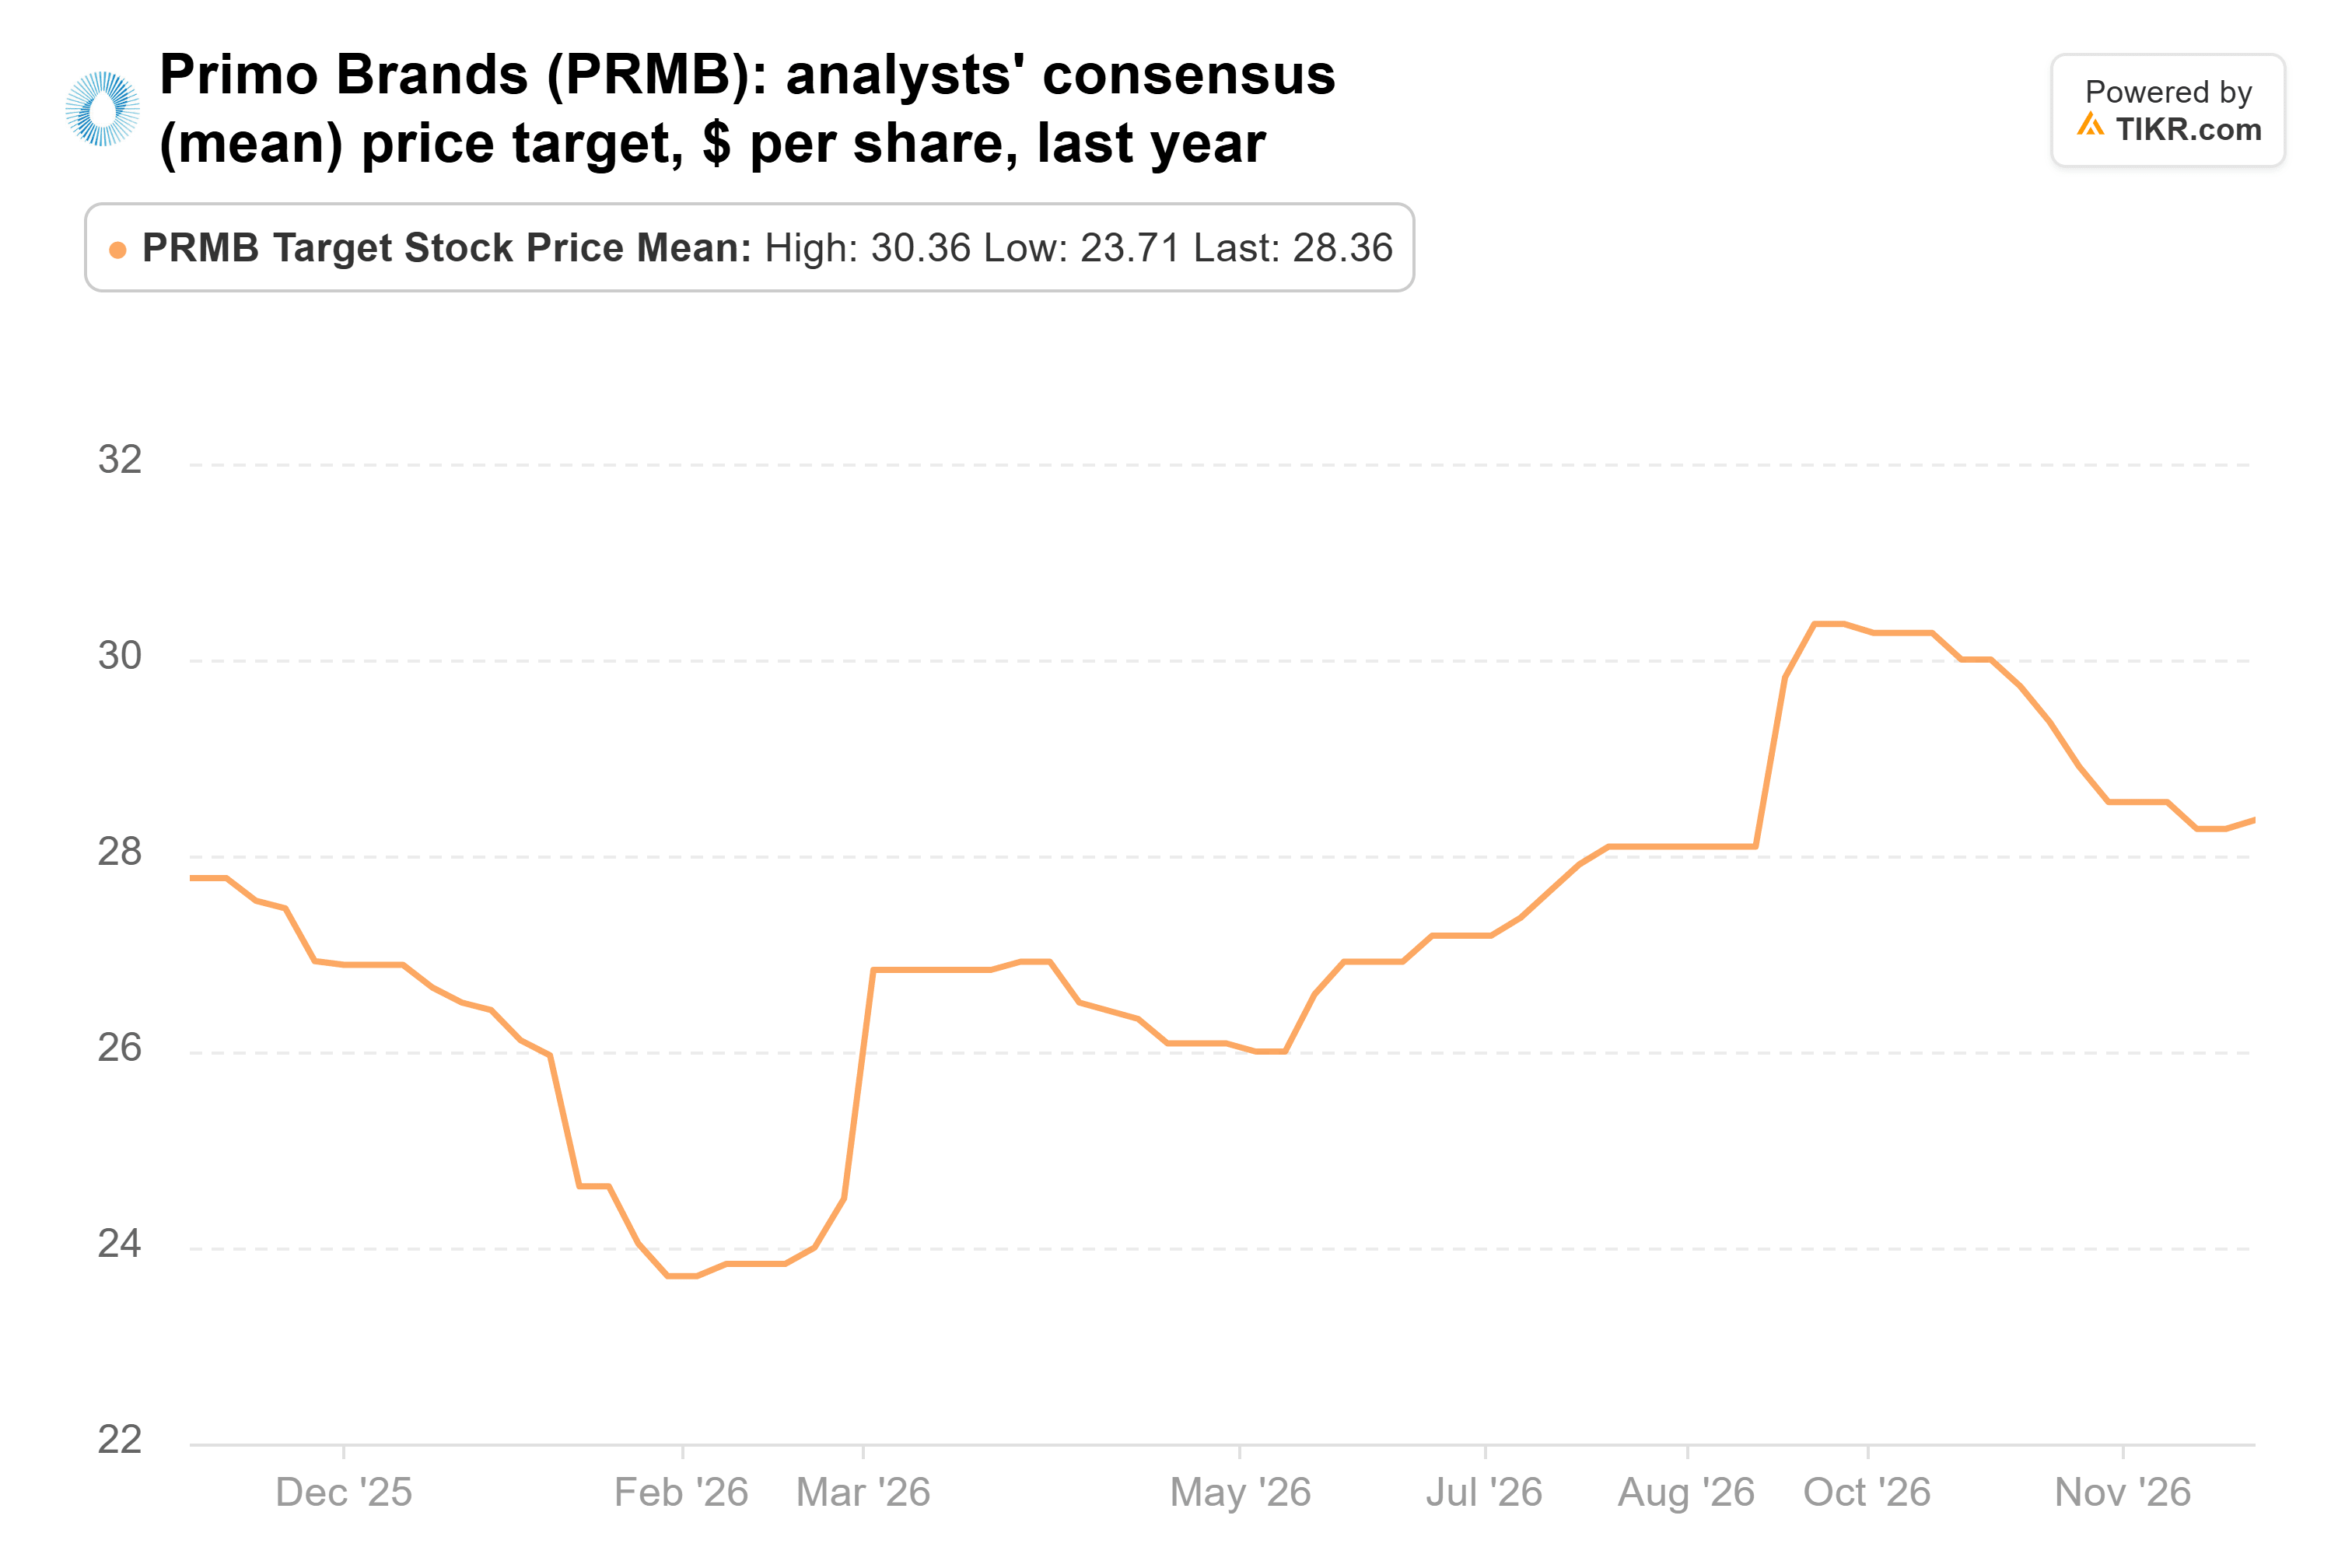
The most bullish analysts have come down, though: the highest target fell from $42 to $32. At about 17x forward earnings, Primo trades 22% below its average target.
Apple is a hedge, or a bet on a drop
Apollo’s Apple position is put options on 1 million shares, with a notional value of $333 million, new in the quarter. A put gains value when the stock falls. Funds buy puts either to bet on a decline or to protect other holdings, and the 13F doesn’t say which this is.
The numbers give a bear plenty to work with. Apple trades at about 36x forward earnings, near the top of TIKR’s quarter-end readings since 2014 and well above its five-year quarter-end average of 29.1x. The 45 analysts who rate it on TIKR have an average target of $345.63, just 0.9% above the latest close. That average climbed from $281.75 over the past year:

Meanwhile, analysts now expect normalized EPS to grow about 5% in fiscal 2027, after 20% in fiscal 2026, as memory costs squeeze Apple’s margins. So far the stock has gone the other way: it’s up 3% since Sept. 30, which works against a put.
Churchill Downs is the one I’d buy
If I could only buy one of these right now, it’d be Churchill Downs. At about 13x forward earnings, with 37% upside to the average target and every analyst’s target above the latest close, the numbers back Apollo’s bet.
It isn’t risk-free. Churchill Downs ended the quarter with net bank leverage of 3.8x, and its average target is still lower than it was a year ago.
Primo has a real case too, with sales growing again. I’d just want to see its cost pressure ease first. On Apple, the numbers back Apollo’s caution: at a multiple near its highest since 2014, the stock has little room for a miss.
Apollo’s next 13F is due in mid-February, and it will show whether the fund kept adding to Churchill Downs. Before that, I’ll be watching Churchill Downs’ fourth-quarter report, due early next year. I’ll want adjusted EBITDA growth faster than the third quarter’s 1% and a smaller drag from Virginia.
So what is Churchill Downs stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Churchill Downs could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Churchill Downs for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!