

Key Takeaways
- Analog Century Management, a $2.7 billion fund, sold all of its Applied Materials, Insight Enterprises and STMicroelectronics shares in the third quarter, its latest 13F shows.
- Applied Materials and STMicroelectronics are down more than 40% since June 30 even though their sales grew, while Insight is up 27%.
- The fund stayed in tech hardware and added to Marvell Technology, which is now one of its four biggest positions.
- At 18x forward earnings, below its five-year average, Applied Materials looks like the best buy of the three stocks the fund sold.
Applied Materials (AMAT), Insight Enterprises (NSIT) and STMicroelectronics (STM) are all gone from Analog Century Management LP’s portfolio, according to its 13F for the quarter ended Sept. 30, filed Nov. 16. The firm manages $2.7 billion, and at the end of June the three stocks made up 12% of its 13F stocks.
A 13F shows only what a fund held on the last day of each quarter, so the filing doesn’t say when it sold, at what price, or why.
Applied Materials trades below its five-year average
Applied Materials was the biggest sale. On June 30, the fund held 219,615 shares worth $159 million, or 5.8% of its 13F stocks. The stock is down 52% from its close that day, but the filing doesn’t show what price the fund sold at. Since then, Applied has reported record revenue of $10.41 billion for its fiscal fourth quarter, up 53%, and guided to $11.1 billion for its 14-week first quarter.
That leaves the stock at about 18x forward earnings, below its five-year average of 21x. Analysts’ average target has more than doubled in the past year to $562, though it’s down from $641 in late September:
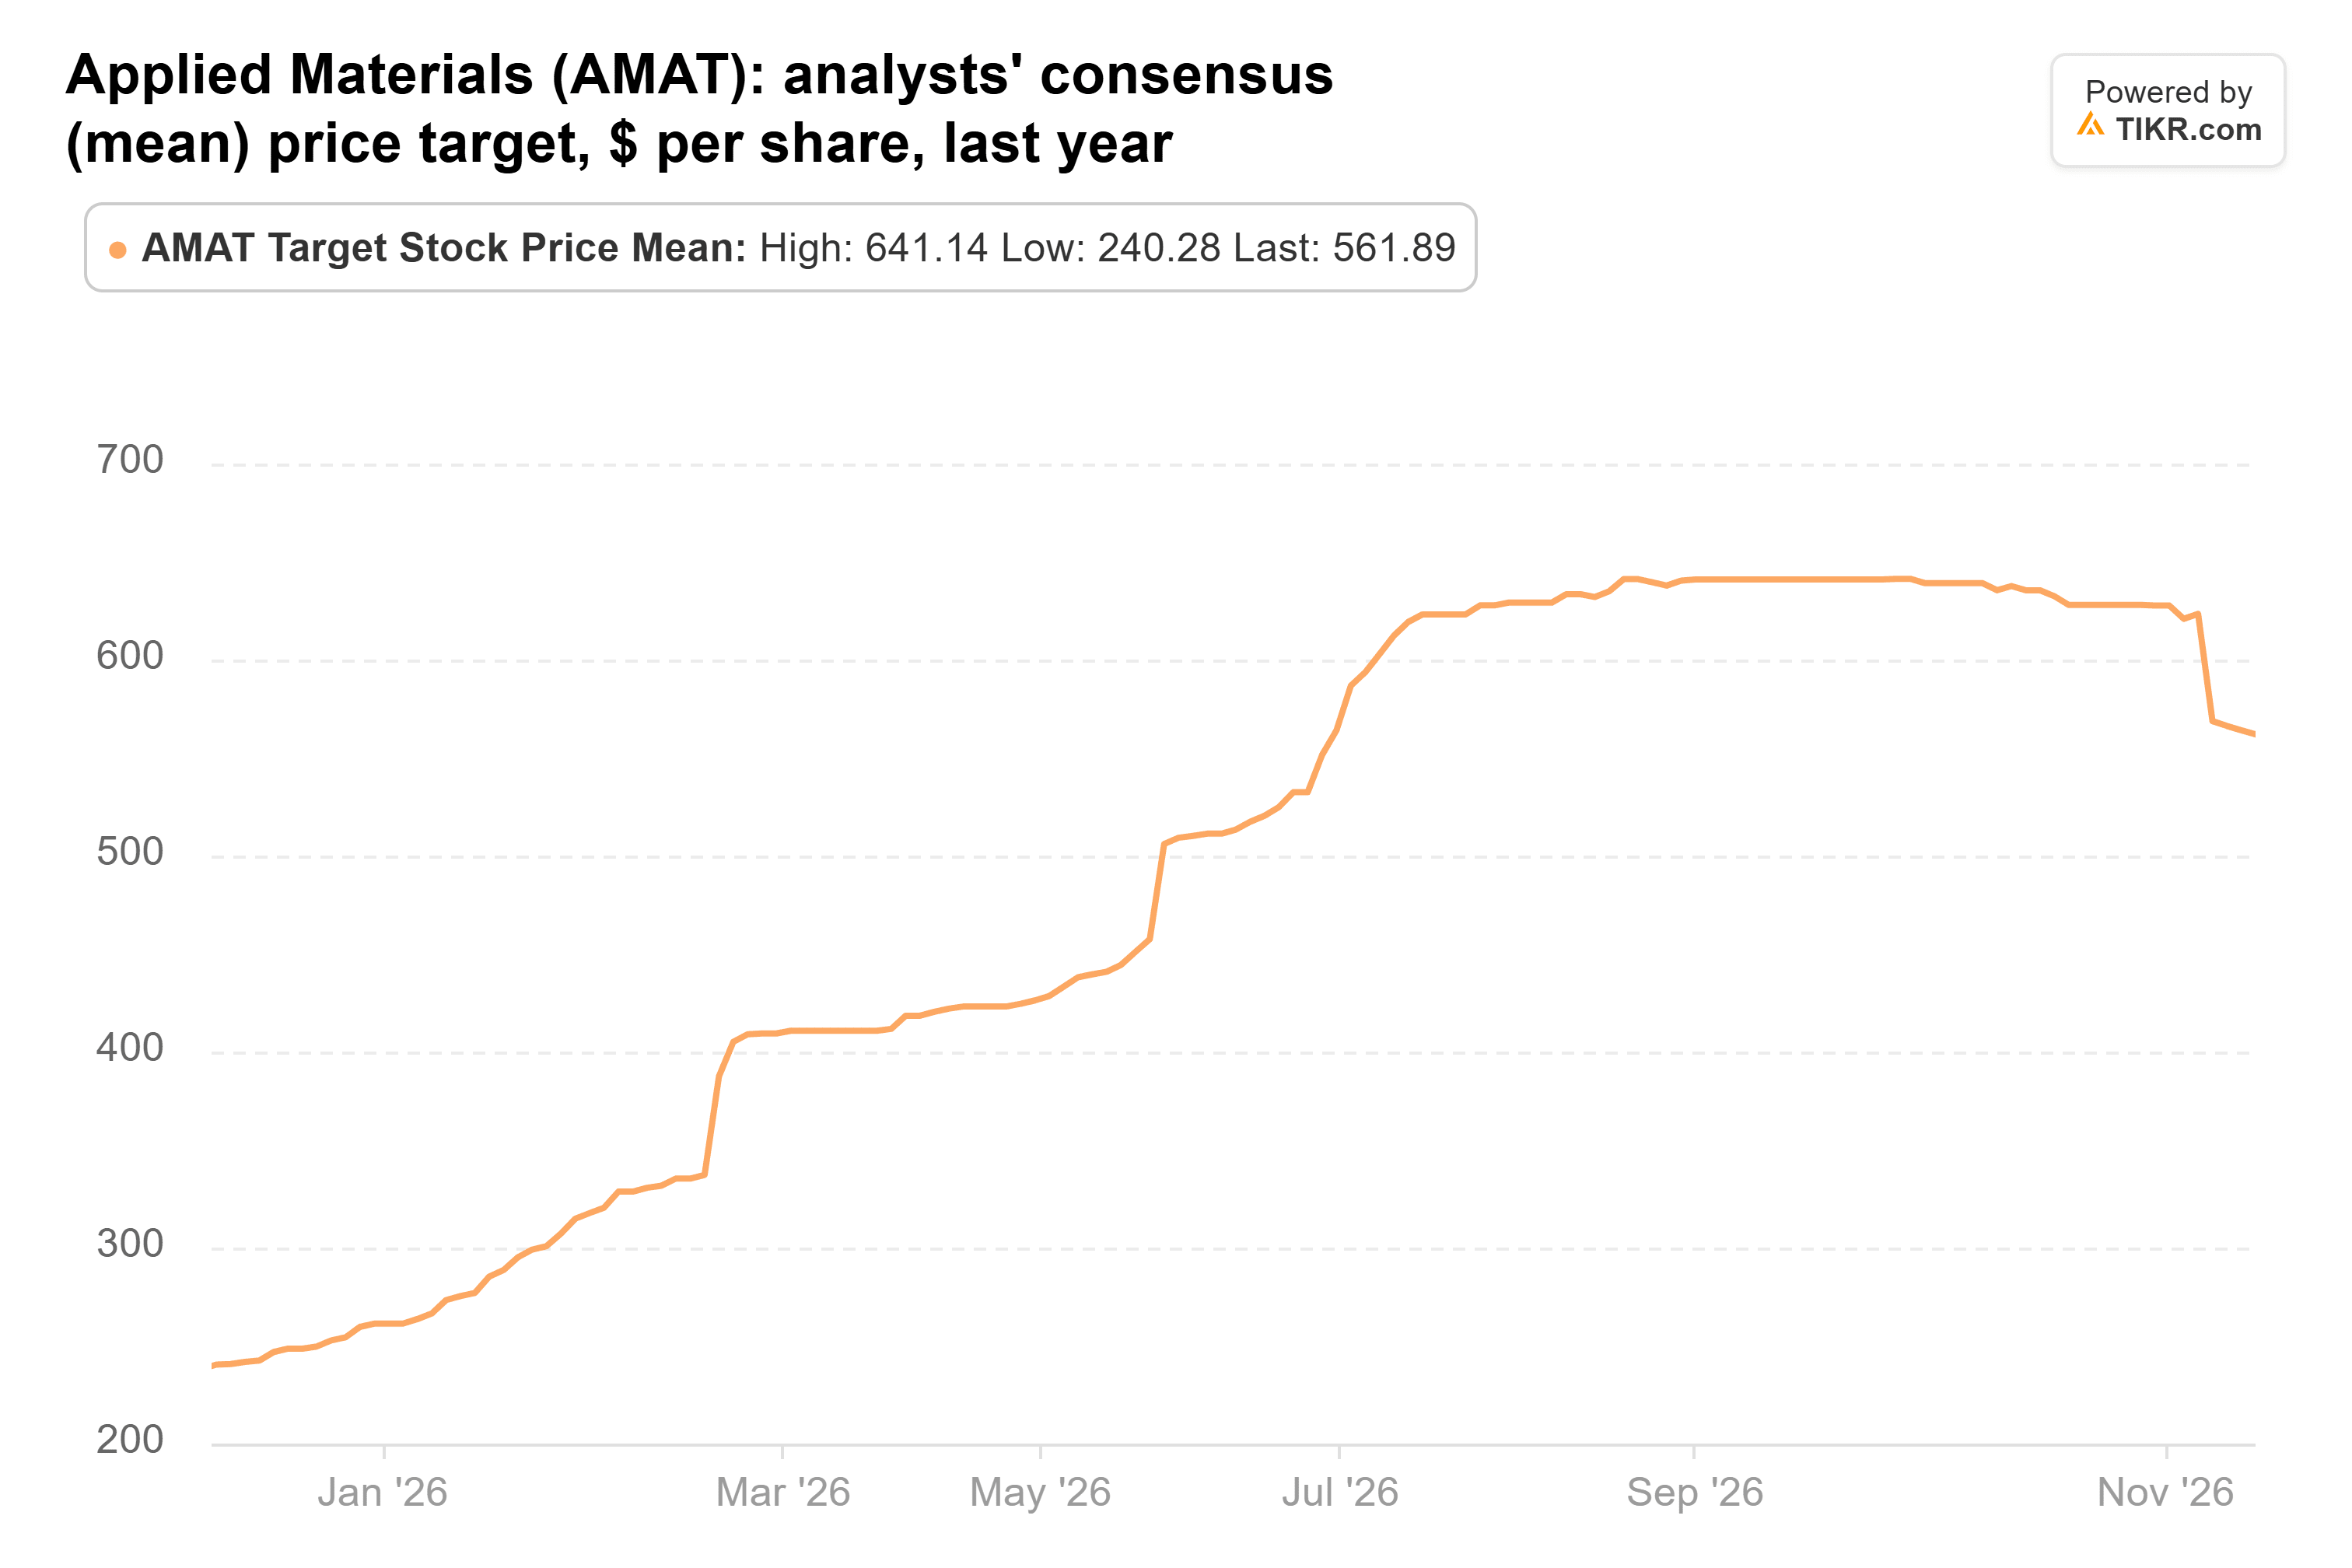
That target is 60% above the latest close, and 40 analysts cover the stock.
TIKR tracks 40 analysts on Applied Materials. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Applied Materials, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Applied Materials’ Analyst Ratings
Insight is the one that kept climbing
On June 30, Insight Enterprises was 3.4% of the fund’s 13F stocks: 771,966 shares worth $94 million. It’s the only one of the three that has risen since then, up 27% from its June 30 close. The business is growing fast too. Third-quarter net sales rose 22% to $2.4 billion, led by a 32% jump in hardware, and adjusted EPS rose 34% to $3.59. GAAP EPS fell 54% to $0.74. The company blames that mainly on a bigger revaluation of earnouts from past acquisitions, plus severance and restructuring costs.
Analysts’ average target has climbed from $128 a year ago to $178, its high for the year:
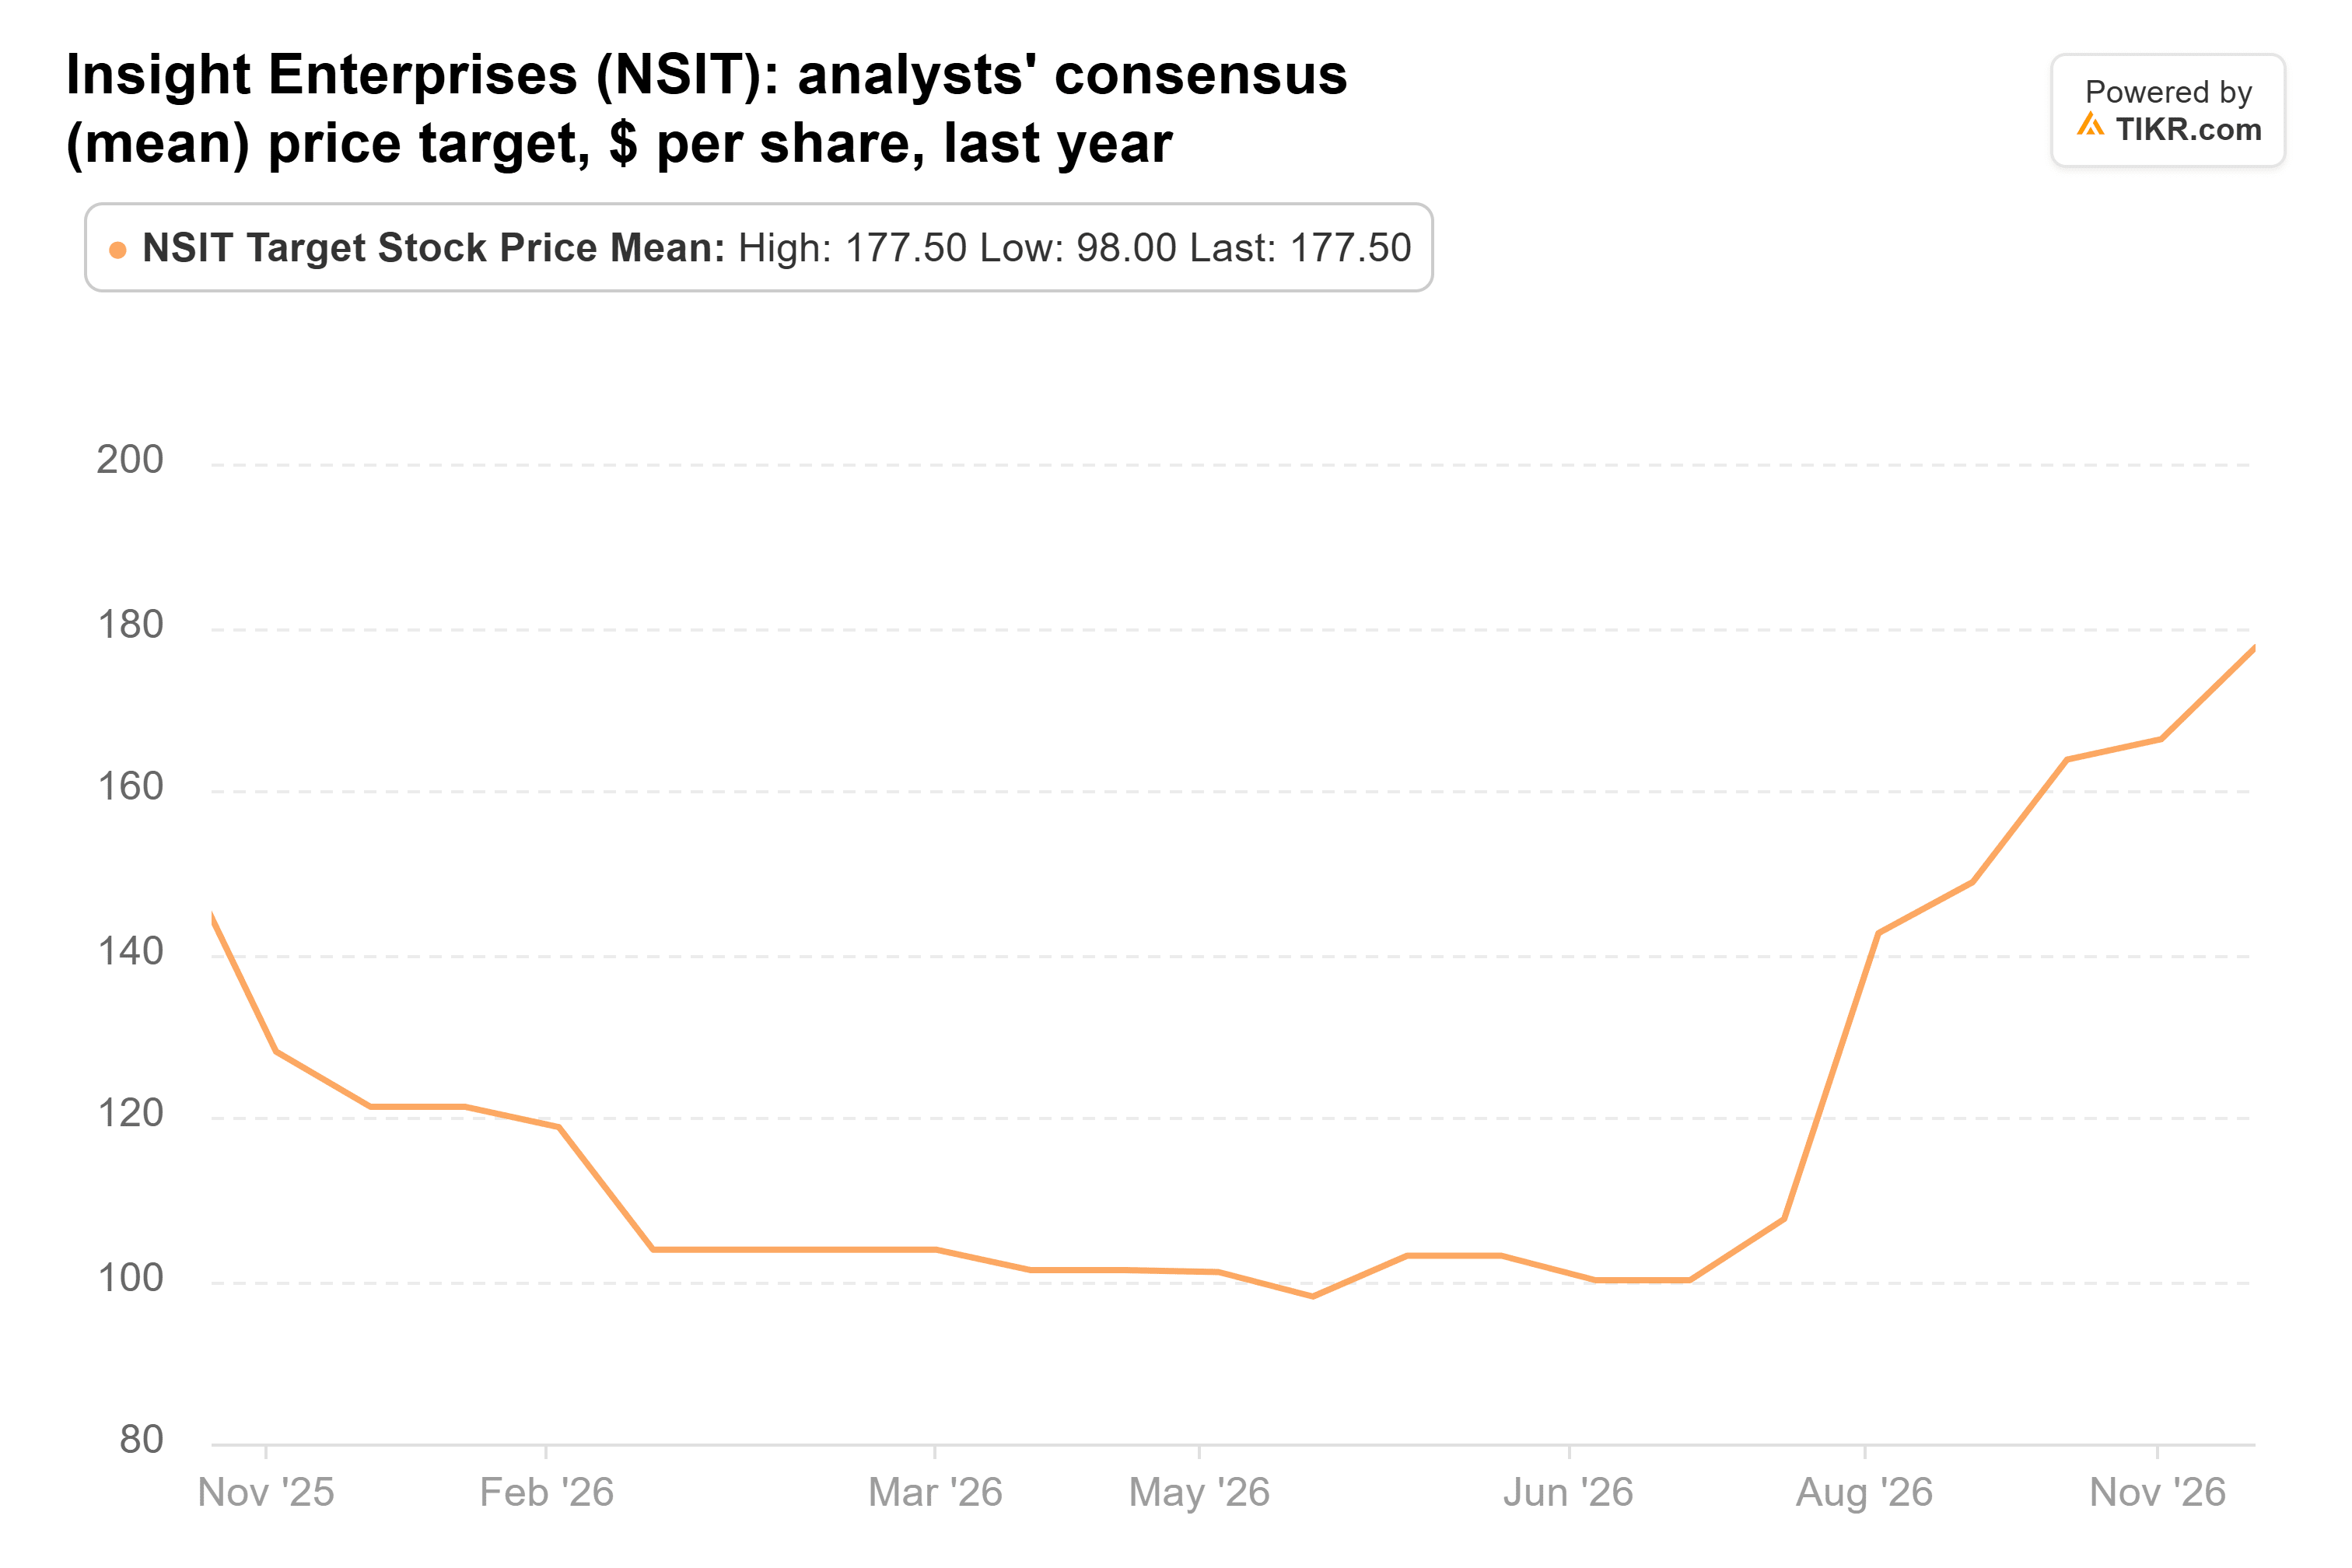
Only 4 analysts cover Insight, though, and their target is just 14% above the latest close. At about 11x forward earnings the stock isn’t expensive, but after the run, Wall Street doesn’t see much room left.
STMicroelectronics’ sales are picking up
STMicroelectronics was the smallest of the three sales: 1.03 million shares worth $77 million, or 2.8% of the fund’s 13F stocks on June 30. The stock is down 41% from its close that day. Over the same stretch, the company reported third-quarter revenue of $3.76 billion, up 17.9% from a year earlier and above the middle of its own guidance. Management guided fourth-quarter revenue to $4.15 billion, up 10.5% from the third quarter. Third-quarter free cash flow rose to $351 million from $130 million a year earlier.
The stock trades at about 18x forward earnings. Analysts’ average target is $71, from 13 analysts, which is 59% above the latest close.
The fund didn’t leave tech hardware
The same 13F shows two stakes the fund built up. At Sept. 30 it held 1.58 million Amphenol (APH) shares, 95% more than at June 30. They were worth $133 million, or 5.0% of its 13F stocks, which makes Amphenol its No. 2 position. Since then, Amphenol has reported a record $10.2 billion quarter, raised its guidance and added a $4 billion buyback. The stock is still down 11% since Sept. 30.
The fund also raised its Marvell Technology (MRVL) stake by 31%, to 456,354 shares worth $121 million. That’s 4.5% of its 13F stocks and its No. 4 position. Marvell is down 45% since Sept. 30. Over that time it agreed to a $115 billion acquisition, and TD Cowen and Bank of America both downgraded it.
Applied Materials is the one I’d buy
Equipment booms do end. When the last one peaked, Applied’s forward P/E fell to 8.2x at the end of October 2018. At least 10 firms also cut their Applied targets after this month’s report, and UBS pointed to multiples shrinking across the chip supply chain.
Still, from June 30 to Oct. 23 analysts raised their fiscal 2027 EPS estimates for Applied by 13%. So the stock fell while the earnings outlook got better. For anyone holding these three today, selling Insight makes the most sense, since the Street’s target is so close to its price. Applied Materials is the one I’d buy, with STMicroelectronics close behind.
The fund’s next 13F is due by mid-February and will show whether it’s still leaning on Amphenol and Marvell. Applied’s report on its 14-week first quarter, guided to $11.1 billion of revenue, will show whether its earnings keep climbing.
So what is Applied Materials stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Materials could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Materials for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





