Key Takeaways
- Fernbridge Capital Management, which manages $2.13 billion, sold its entire stakes in Xylem and NVIDIA in the third quarter, its latest 13F shows.
- In the same quarter it added to PTC and Intuit, which ended it as two of its four biggest positions.
- Xylem has since cut its 2026 outlook, while analysts raised NVIDIA’s earnings estimates this year even as its CEO’s resignation sank the stock.
- The numbers back the Xylem sale better than the NVIDIA one, and NVIDIA’s report next week is the next test.
Xylem (XYL) and NVIDIA (NVDA) have each lost about a fifth of their value since Sept. 30, and Fernbridge Capital Management didn’t own a share of either on that date. Its 13F for the quarter ended Sept. 30, filed Nov. 13, shows it sold out of both.
Out with Xylem and NVIDIA, in with software
On June 30, Fernbridge held 572,614 Xylem shares worth $68 million, 5.0% of its 13F stocks, and 193,818 NVIDIA shares worth $39 million, 2.8%. By Sept. 30, both stakes were gone. Over the same quarter, it bought 57% more PTC (PTC) shares and 84% more Intuit (INTU) shares, ending with stakes worth $242 million and $211 million. That’s 14.6% and 12.7% of the $1.66 billion of US stocks in its 13F, its No. 2 and No. 4 positions. A 13F shows only what a fund held on the quarter’s last day, so it can’t tell us when Fernbridge sold, what it got for the shares, or why.
TIKR tracks 21 analysts on Xylem. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Xylem, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Xylem’s Analyst Ratings
Xylem’s numbers back the exit
Xylem gave investors plenty to rethink in late October, when it cut its 2026 outlook. It now expects revenue of about $8.95 billion, down 1% from 2025, after guiding for 2% growth, and adjusted EPS of $5.40-$5.45, down from $5.55-$5.70. Orders were the bright spot: $2.3 billion in the third quarter, up 10% organically.
Analysts had been lowering their sights well before that. The consensus price target has slid from $167 a year ago to $125:
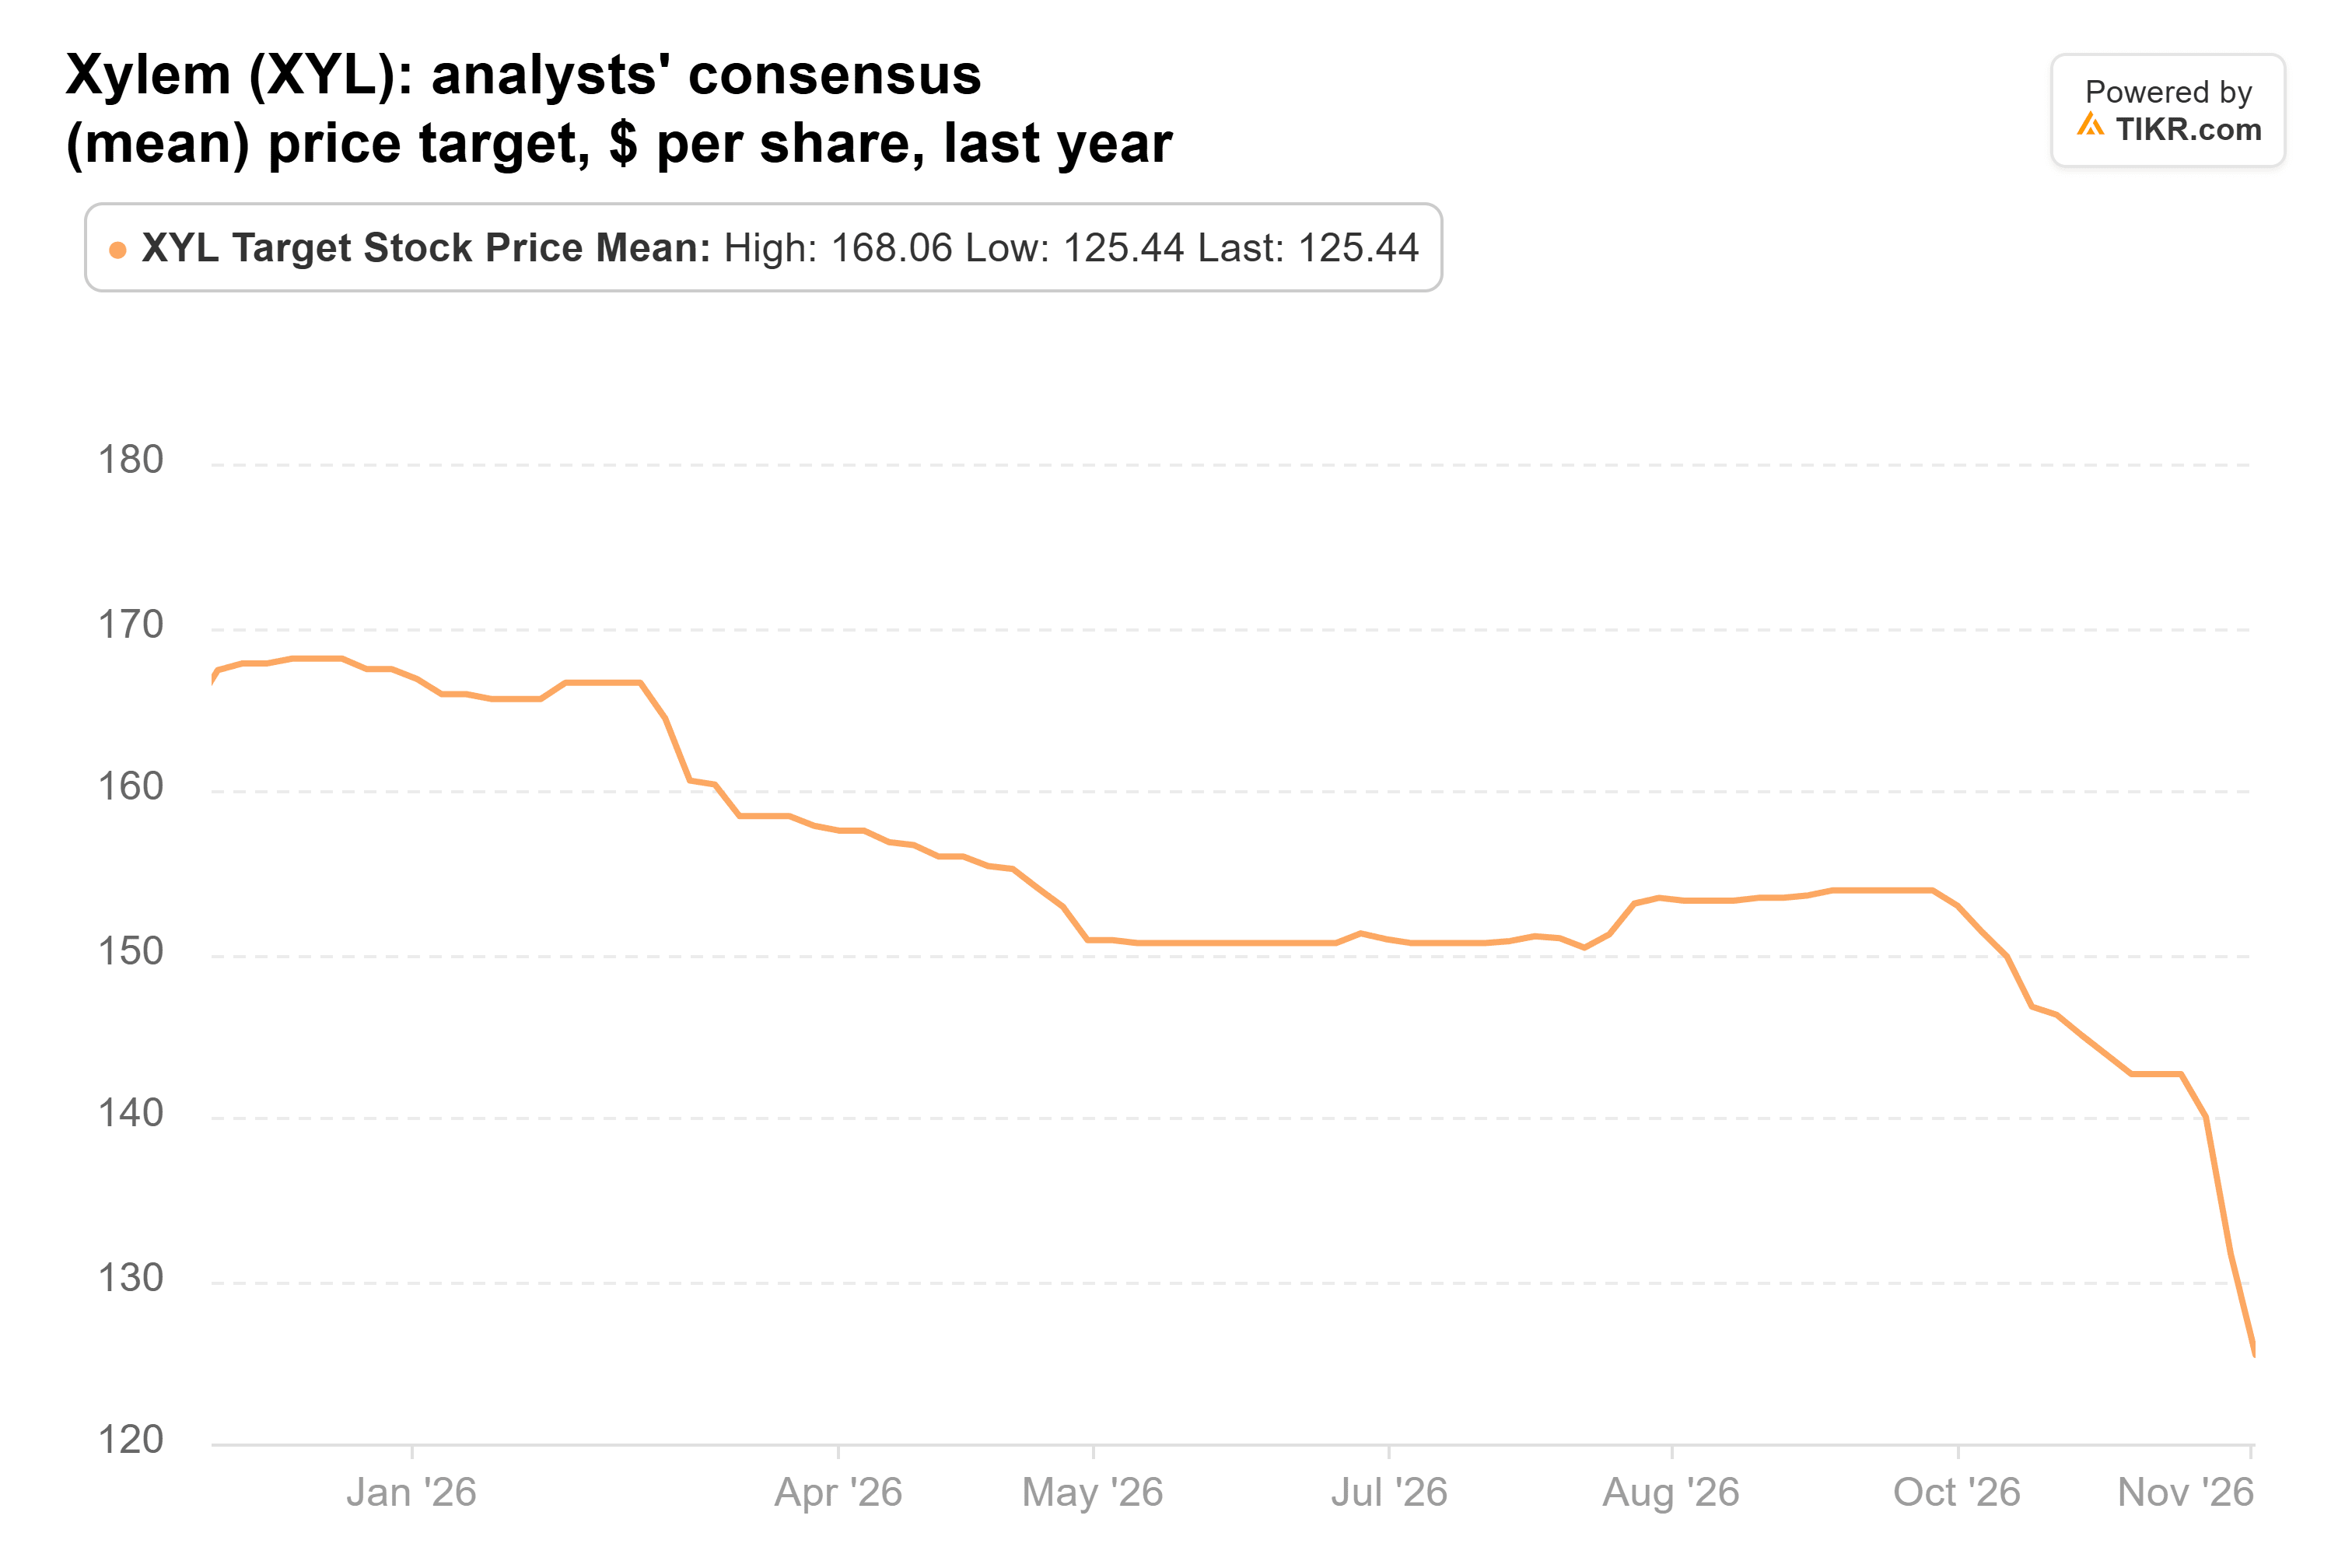
That’s still 33% above the last close of $94.18, and after a 20% drop since Sept. 30, the stock trades at about 17x forward earnings. But a company that just cut its revenue outlook to a flat year organically has to show those orders turning into sales before it looks like a bargain.
NVIDIA’s numbers don’t
NVIDIA is a different story. Its 19% drop since Sept. 30 has a clear cause: Jensen Huang resigned as CEO on Nov. 12, and CFO Colette Kress is interim CEO while the board searches for a permanent one. Six firms downgraded the stock by that day, and HSBC followed with a $170 target.
The business numbers point the other way. Revenue beat the top of NVIDIA’s guidance in each of the last three quarters, and analysts’ EPS estimate for the year ending January 2028 rose 25% from the end of June to late October, to $15.92. The consensus target climbed with it, from $233 a year ago to $305 on Nov. 12:
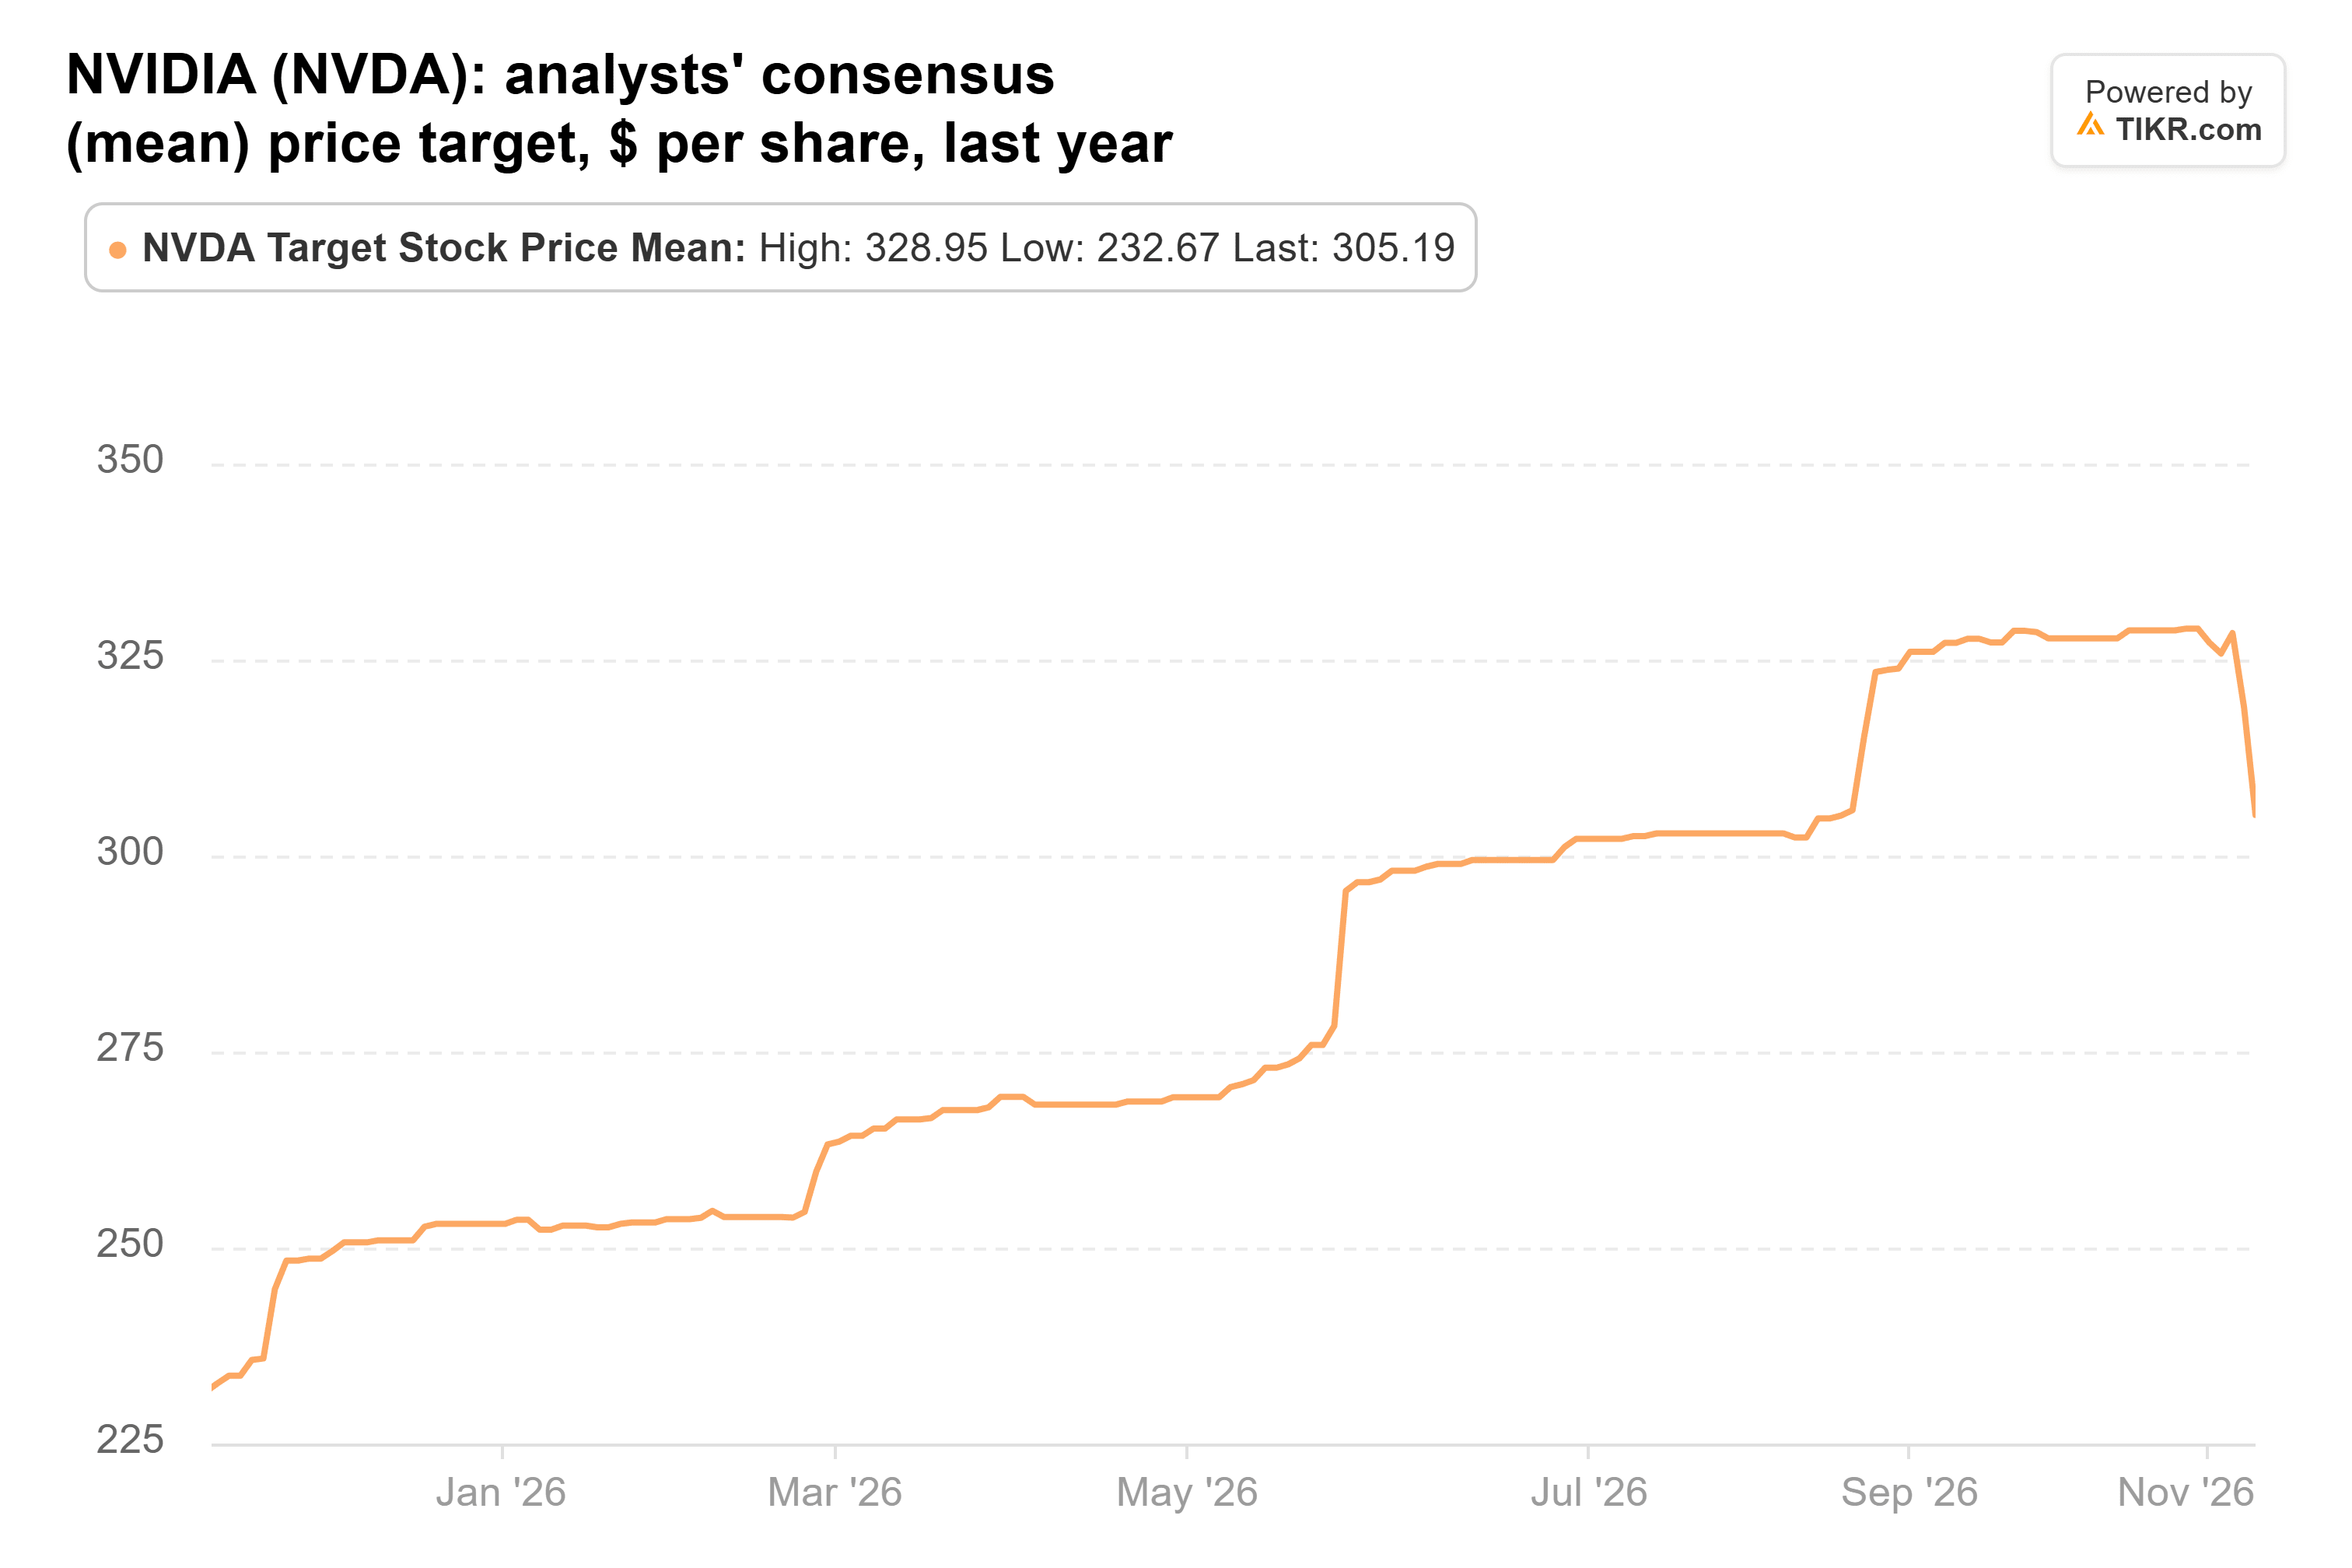
Even HSBC’s bearish target sits above the $162.85 close. At about 13x forward earnings, NVIDIA also trades far below the 30.3x it averaged over the last three years. It has looked cheap for three years, and it looks cheaper still.
Where the money went
The two stocks Fernbridge added to have done far better since the quarter ended. Five days after it, Schneider Electric agreed to buy PTC for $205 a share in cash, a 42% premium, which explains most of PTC’s 40% gain since Sept. 30. At $196, it trades just under the deal price, so most of the upside is already in the stock.
Intuit is up 24% since Sept. 30 but still 50% below its 52-week high. In May it trimmed its TurboTax revenue forecast, and in August it gave fiscal 2027 guidance that fell short of forecasts, both feeding fears that AI will eat into its tax and accounting software. It trades at about 14x forward earnings and reports again around Nov. 19. (Those gains run from the Sept. 30 price. The 13F doesn’t show what Fernbridge paid, or whether it still holds the shares.)
The Xylem sale holds up better
Here’s where I land: the numbers back Fernbridge’s Xylem sale far better than its NVIDIA one. Xylem cut its outlook and the Street cut its targets along with it, while NVIDIA’s earnings estimates climbed and its multiple sank to less than half its three-year average.
NVIDIA without its founder is new territory, though, and management already expects gross margin to dip to 71%-72% in the January quarter as memory costs climb. Its report next week, its first without Huang, is the next real test of this exit. Fernbridge’s next 13F, due in mid-February, will show whether it came back to either stock.
So what is Xylem stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Xylem could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!