


Key Takeaways
- Check Capital Management, which manages $2.37 billion, had 34.2% of its 13F holdings in Berkshire Hathaway (BRK.B) as of Sept. 30, after an increase of 2% in shares during the quarter.
- Its filing also lists Berkshire call options with a notional value of $2.10 billion, more than all the stocks it reports.
- Berkshire bought back $9.6 billion of its own stock in the same quarter, but the shares are up 19% since then and trade near their highest forward P/E in five years.
- With analysts expecting little earnings growth through 2028, I’d wait for a better price before following the fund.
Check Capital Management’s 13F for the quarter ended Sept. 30, filed Nov. 5, has one stock far ahead of the other 16: Berkshire Hathaway.
A third of its stocks, plus a stack of calls
The fund held 1.10 million Berkshire Class B shares worth $547 million at Sept. 30, or 34.2% of the $1.60 billion of US stocks in its 13F. That’s 2% more value of stocks than it held at the end of June.
It also listed call options on Berkshire with a notional value of $2.10 billion, more than its whole stock list put together. (The firm manages $2.37 billion in all, according to its latest Form ADV.) And calls on Berkshire are an old habit here: its 13Fs listed them as far back as 2012.
Since Sept. 30, Berkshire stock has risen 19%.
TIKR tracks 4 analysts on Berkshire Hathaway. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Berkshire Hathaway, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Berkshire Hathaway’s Analyst Ratings
Berkshire was buying, too
The fund had company in the Q3. Berkshire bought back about $9.6 billion of its own stock, more than double the second quarter’s $4.5 billion, it said in its Nov. 7 release.
The rest of that release was mixed. Operating earnings fell 5.8% to $12.7 billion, as insurance underwriting earnings dropped 42.9% and insurance investment income fell 14.1% on lower interest rates.
BNSF, Berkshire Hathaway Energy and the manufacturing, service and retailing businesses all earned more.
Rates matter a lot here, since after-tax investment income made up 36.1% of Berkshire’s 2025 operating earnings.
So the big question for CEO Greg Abel is whether he can put $352.3 billion of cash and Treasury bills (at Sept. 30, down from $359.2 billion in June) to work at better returns than bills pay.
Buying back stock is one answer. The $6.8 billion Berkshire paid for homebuilder Taylor Morrison in July is another, and so is its $10 billion Alphabet stake, which now trades below what Berkshire paid.
Does 26x add up?
Analysts don’t expect much earnings growth from here. TIKR’s consensus has normalized EPS rising from $20.62 in 2025 to $23.15 in 2026, then $22.47 in 2027 and $23.06 in 2028:
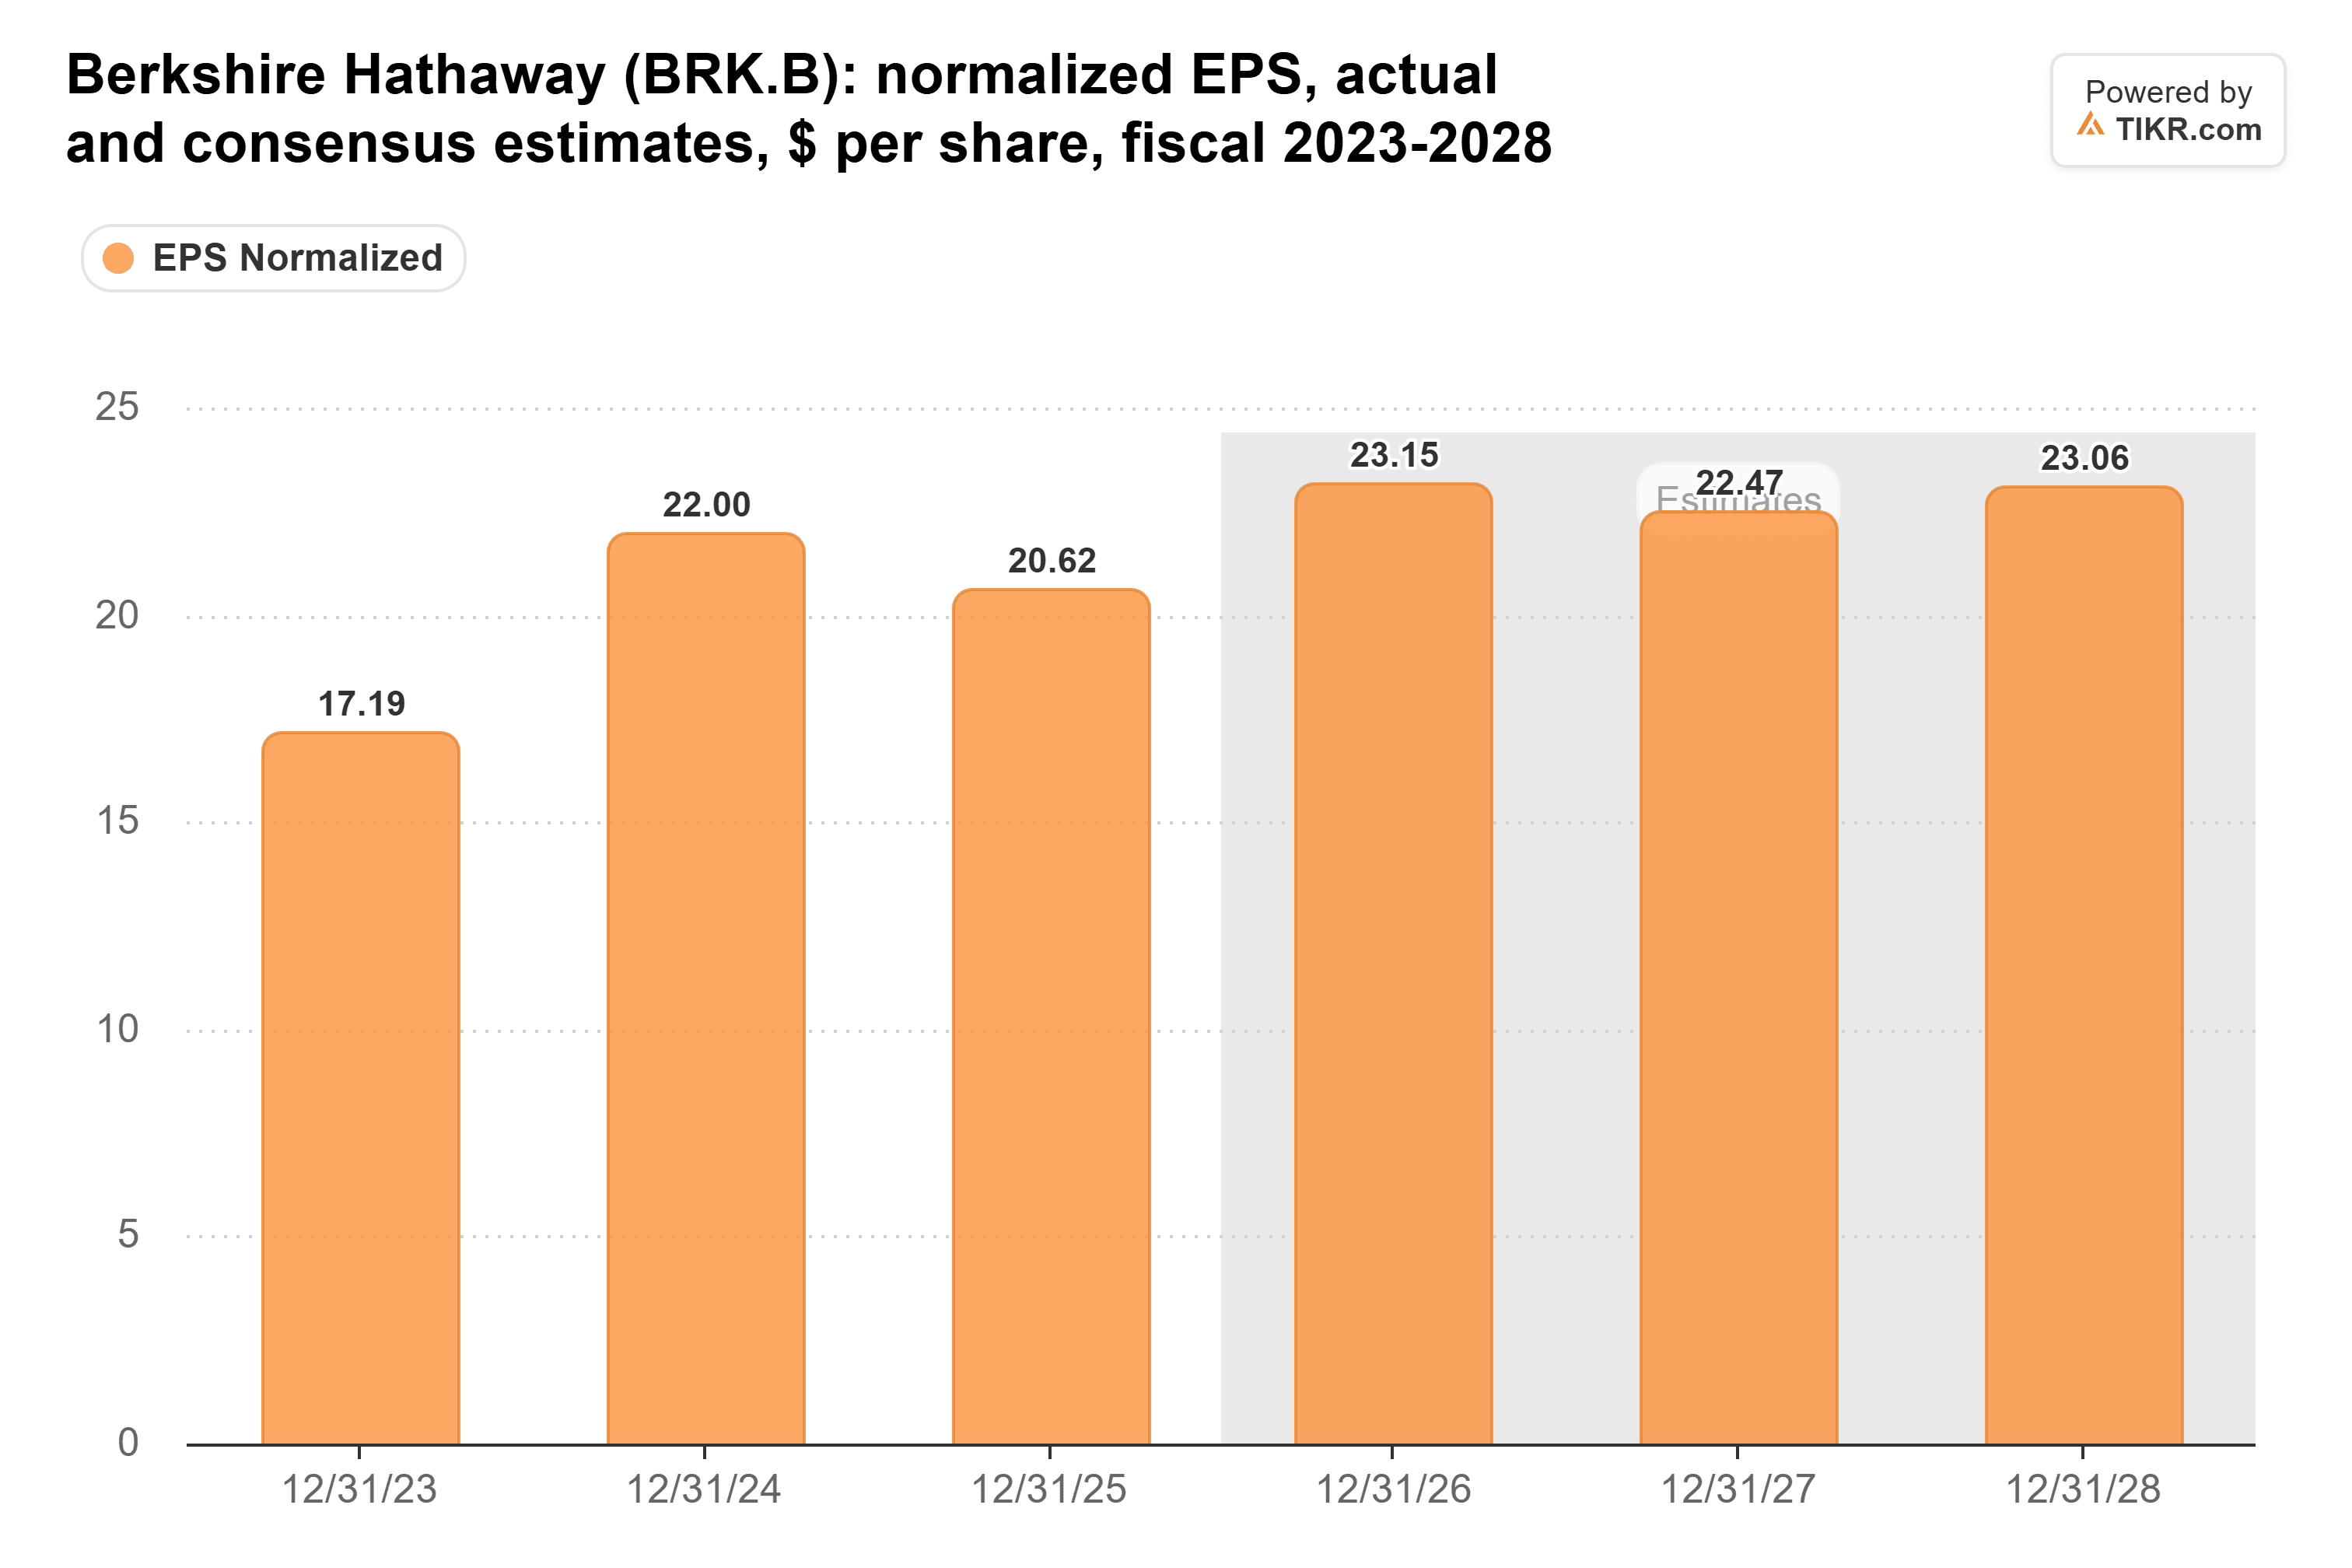
And with Q3 operating earnings down 5.8%, I don’t see much reason for analysts to raise those figures.
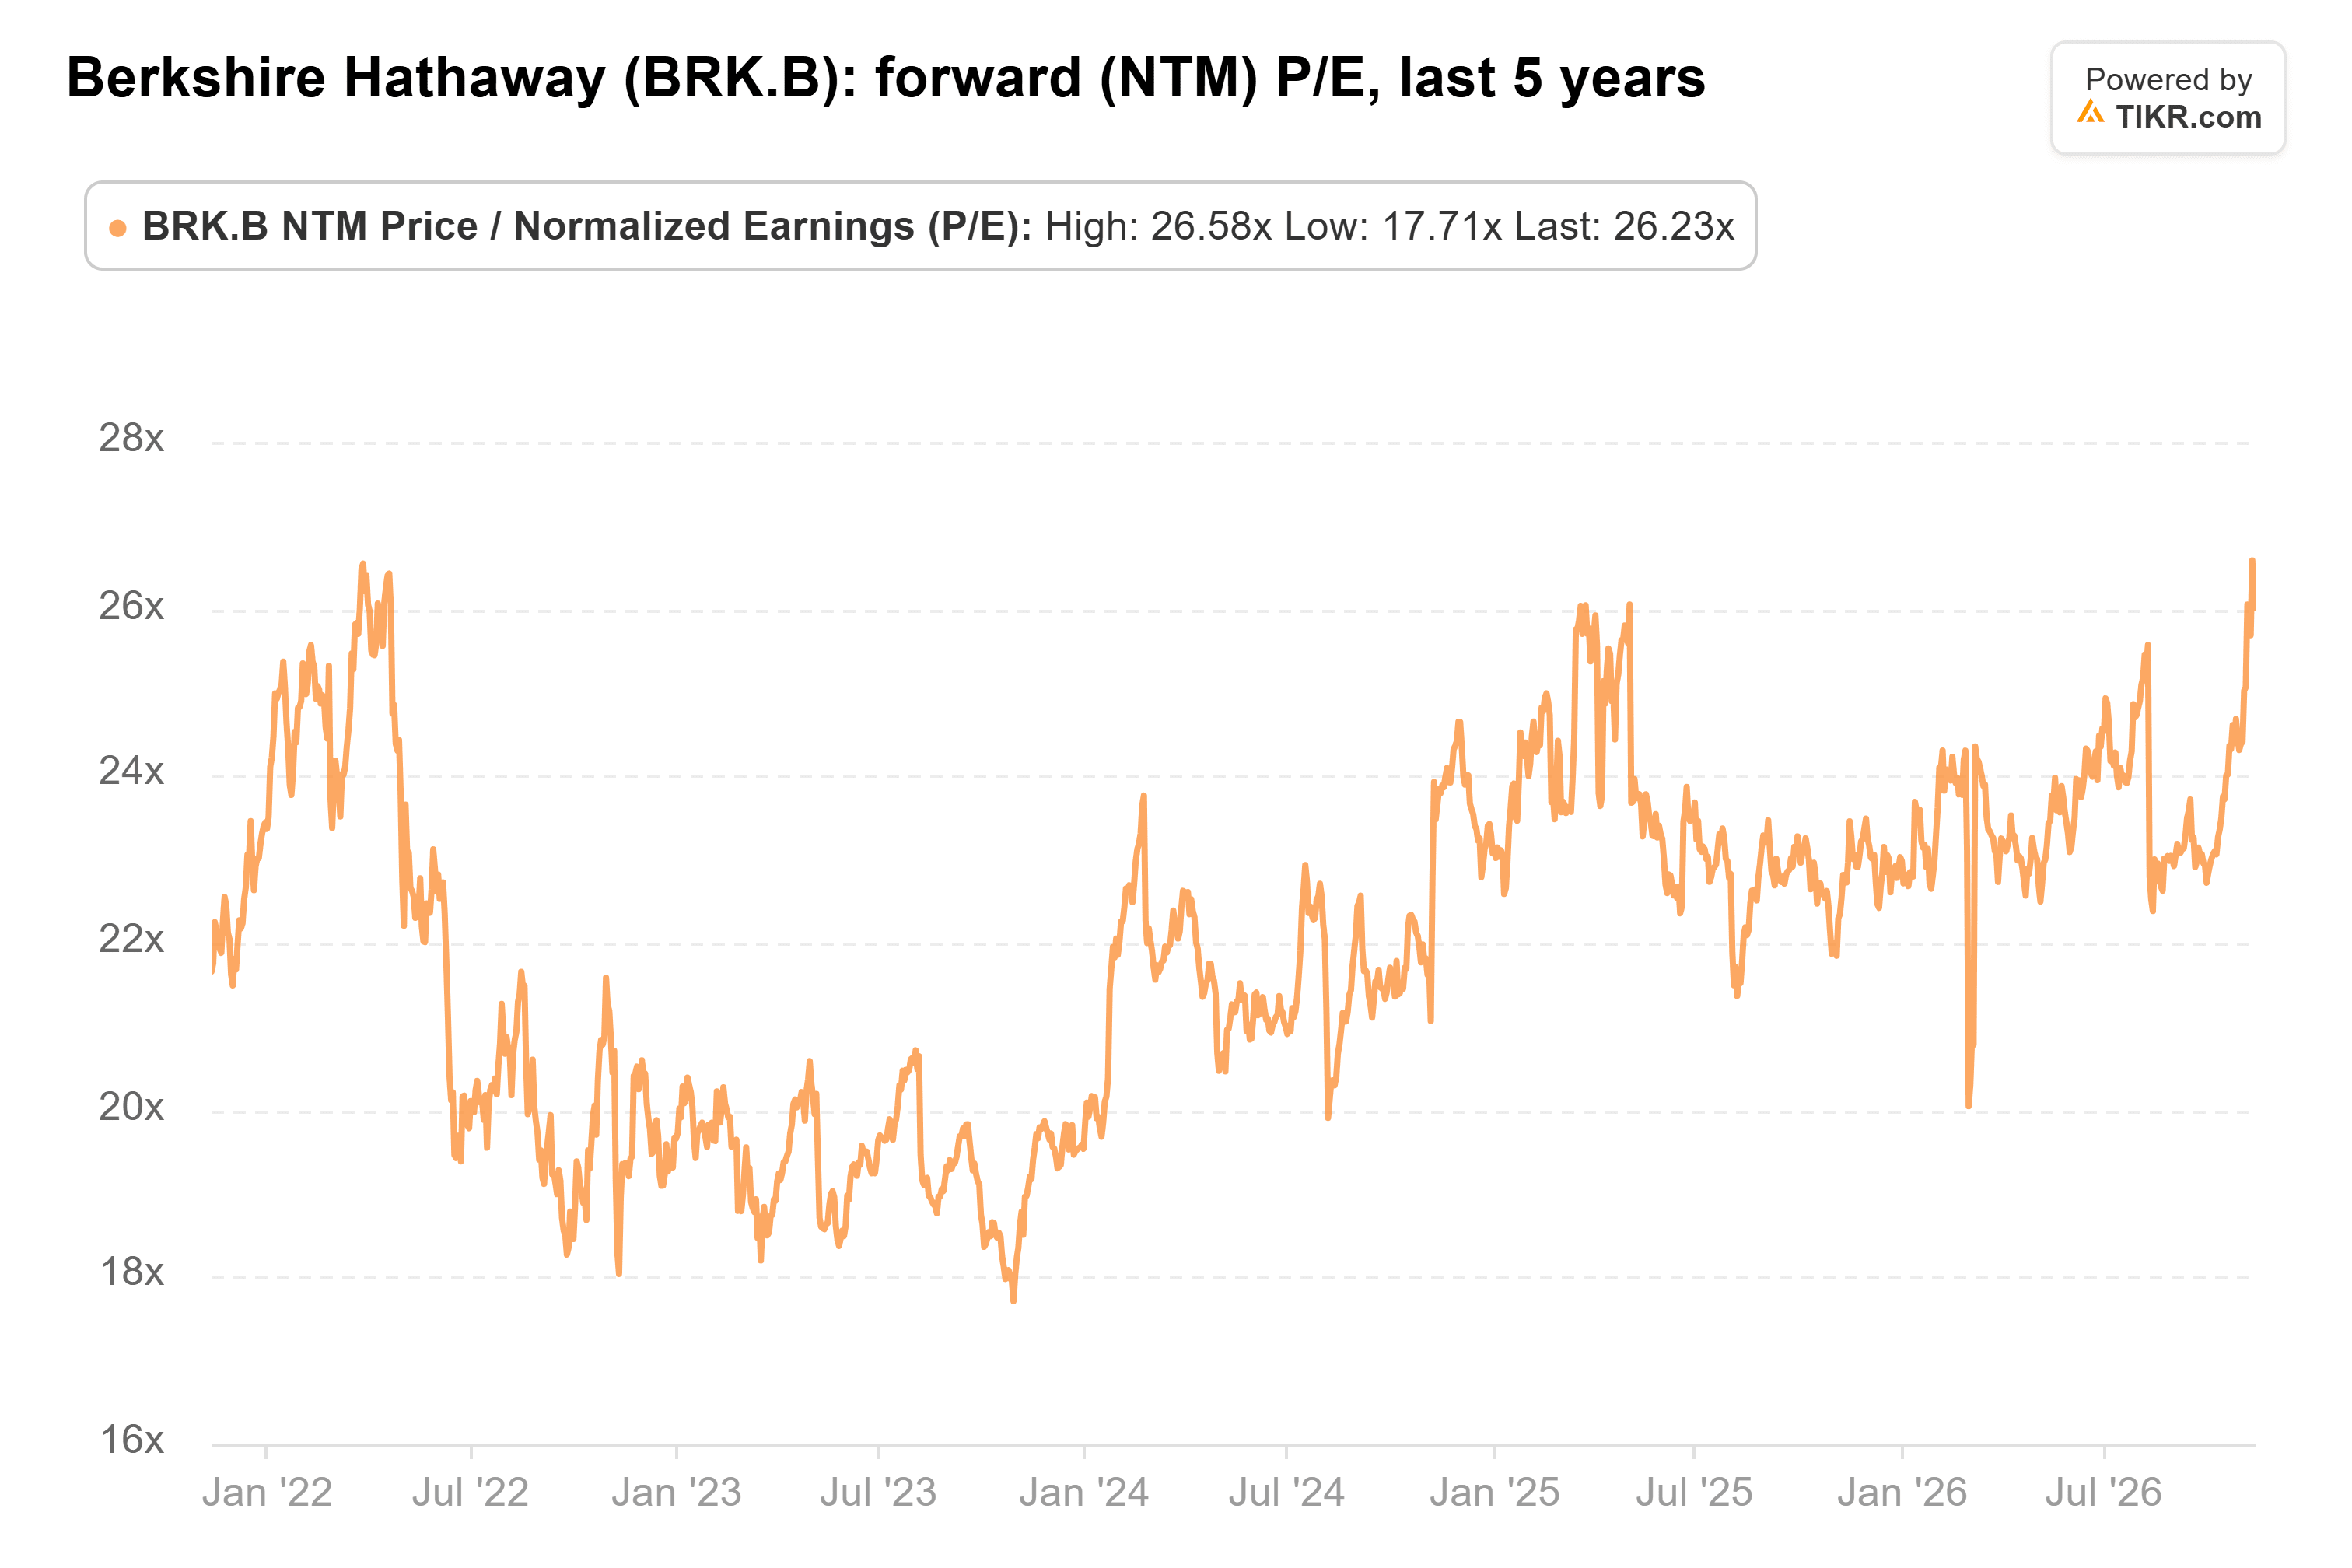
Yet investors are paying more for those earnings than at almost any point in five years. Berkshire trades at 26x forward earnings, just shy of the 27x it hit on Nov. 9, against a five-year average of 22x and a low of 18x in October 2023:
The stock has also run past Wall Street’s targets. The four analysts covering Berkshire have an average target of $556, up from $529 a year ago, and the stock now sits 6% above it at $588:
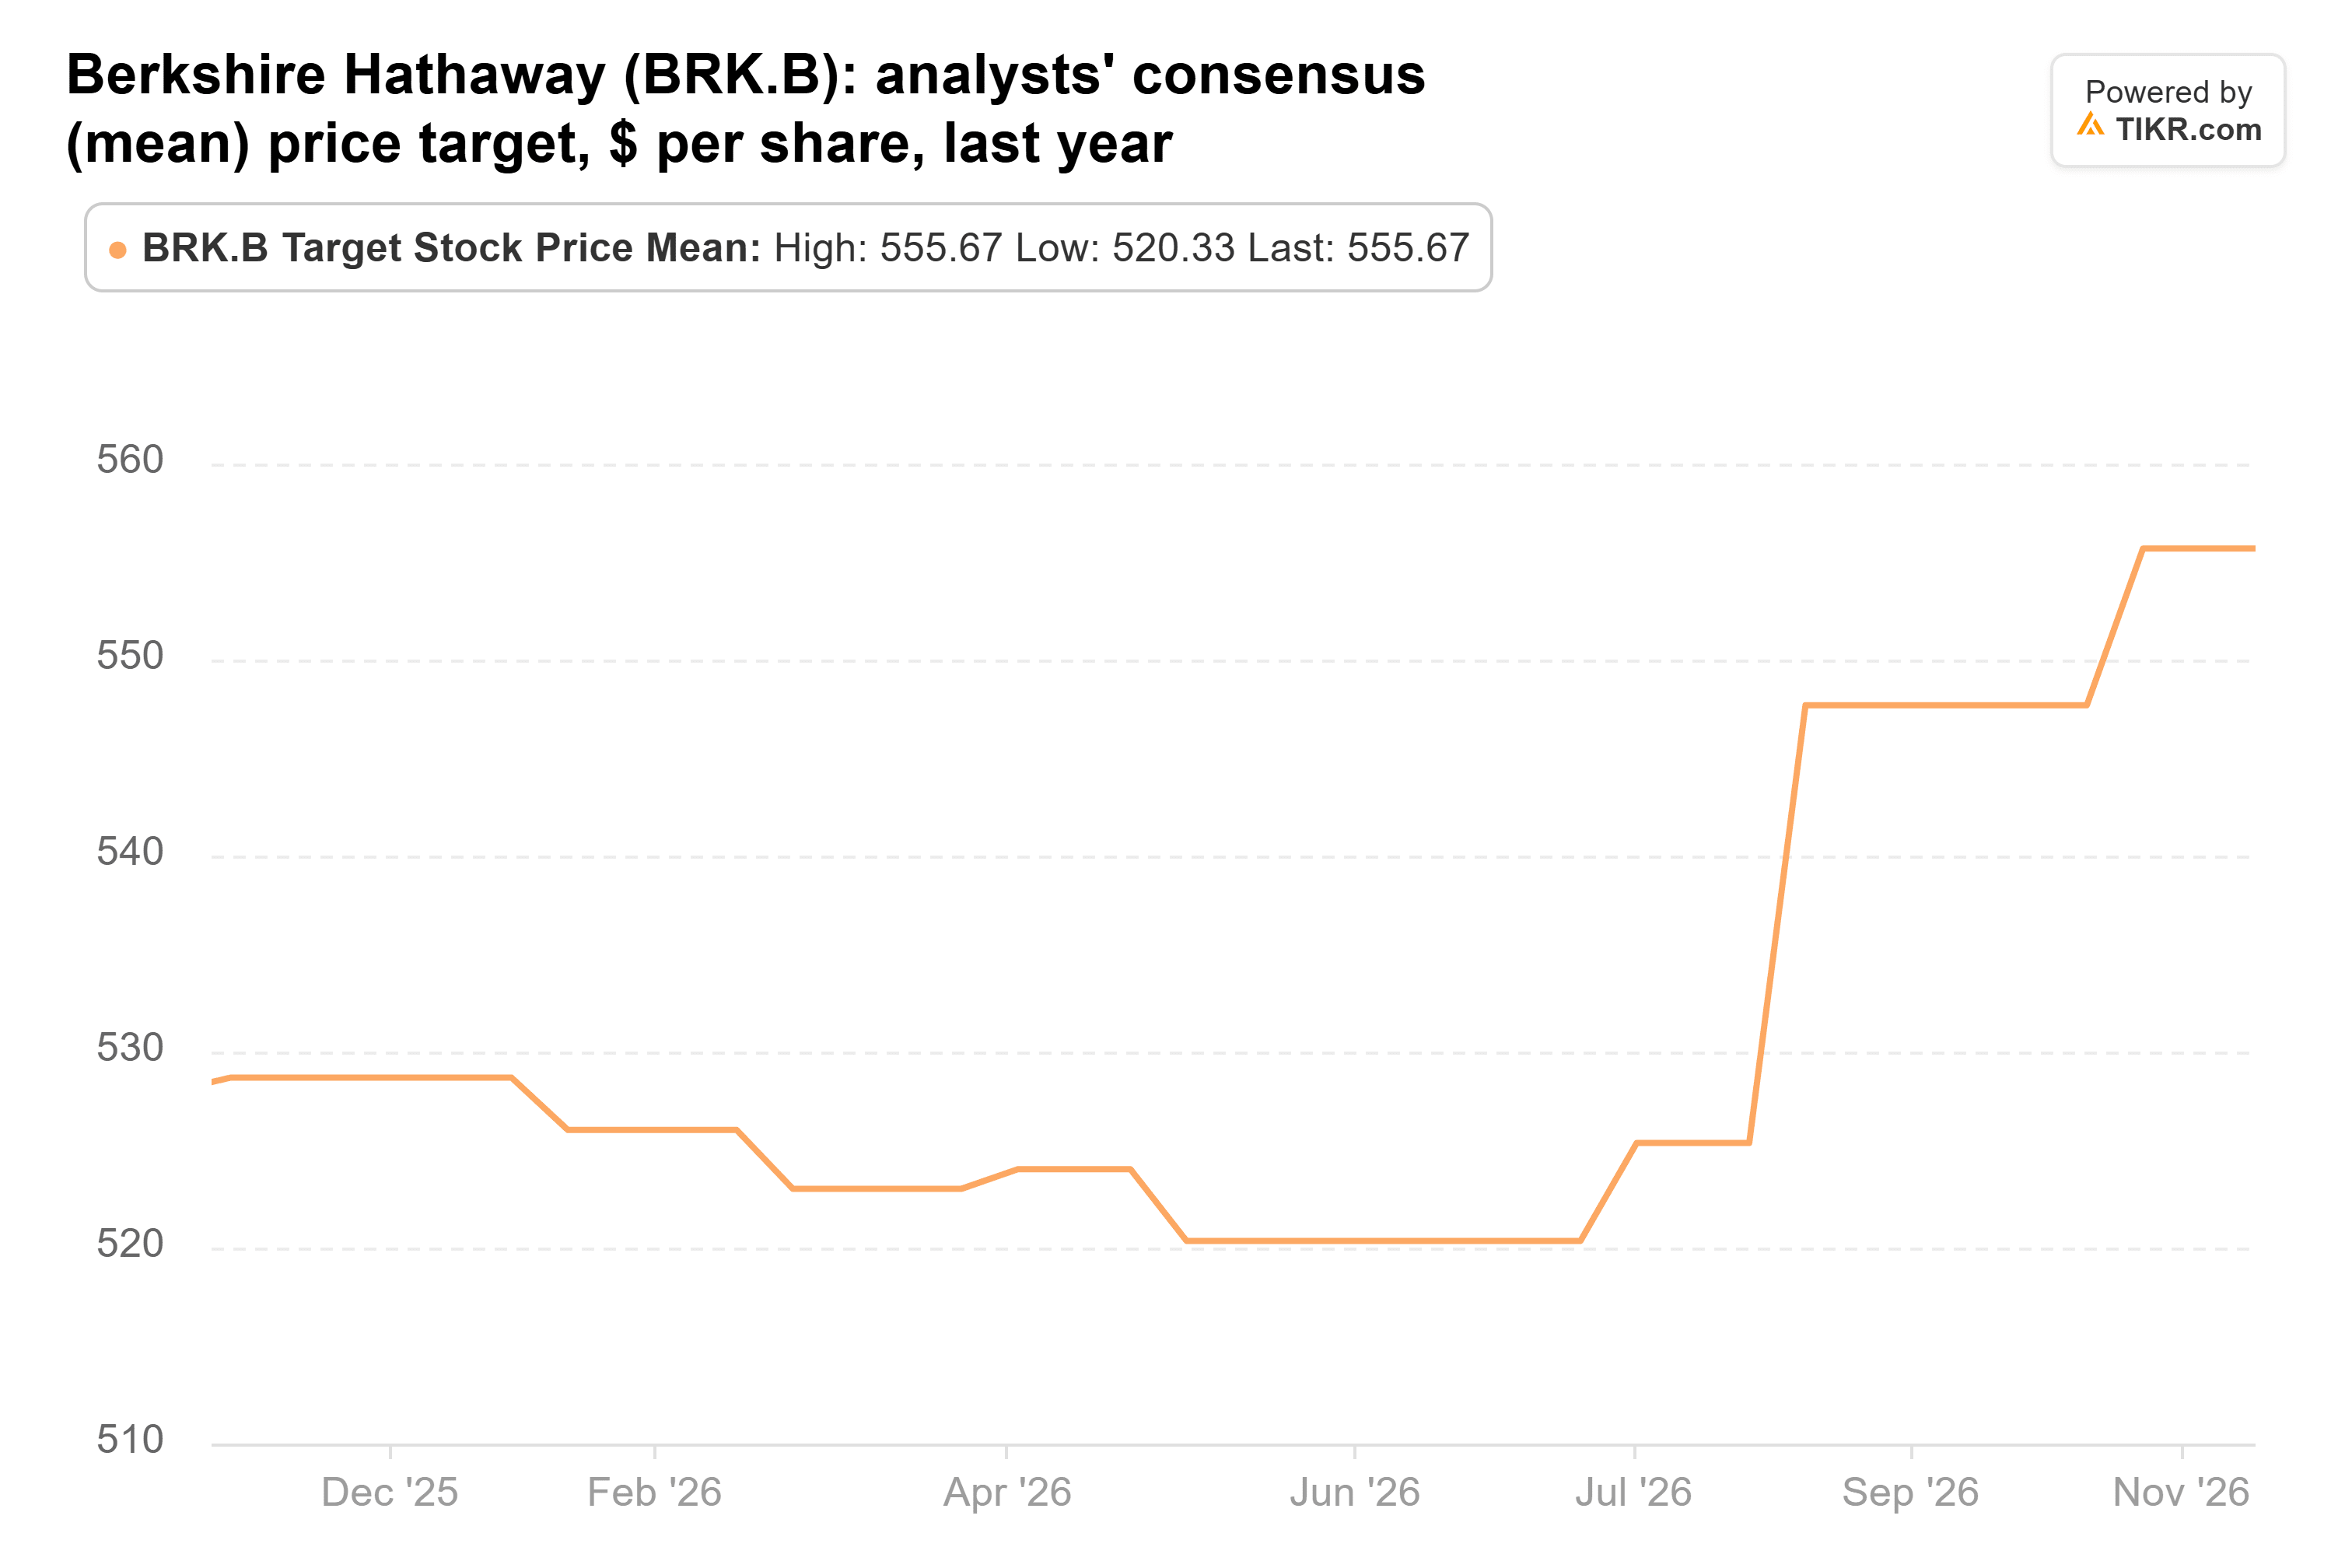
Only the highest target, $628, is above today’s price.
I’d wait for a better price
Insurance is the main risk. GEICO’s combined ratio rose to 91% in the second quarter from 84% a year earlier, and all three of Berkshire’s underwriting groups earned less in Q3.
Adding at Sept. 30’s price looks sensible to me, and Berkshire’s management clearly agreed, buying back stock in the same quarter.
But at 26x, with earnings expected to stay roughly flat through 2028, I wouldn’t follow the fund today. I’d want a pullback toward the stock’s 22x average, or proof that Abel’s deals earn more than Treasury bills, first.
The next clues come in mid-February, when the fund’s next 13F is due, and in late February or early March, when Berkshire reports full-year results, and Abel publishes his second annual letter.
So what is Berkshire Hathaway stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Berkshire Hathaway could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Berkshire Hathaway for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


